ESMA's 2024 Guidelines: Paving the Way for Ethical Investments in ESG Funds
July 24, 2024
•
5 mins read
The name of a fund is often the first and sometimes the only point of contact before investing. Individual investors frequently lack the patience to read through the extensive legal documents that fund managers must produce to ensure transparency. However, fund naming has so far been minimally regulated.
The urgency of climate issues and the growing interest in sustainable and responsible investment have increased the supply of ESG investment funds. Many funds now use terms such as "ESG," "Sustainable," "Transition," and "Net Zero" in their names. Yet, not all of these funds have adopted a sustainable finance label (e.g., French SRI Label, Towards Sustainability, FNG Siegel), which somewhat guarantees alignment with their marketed features. A common and ambitious label is still missing from the sustainable finance directives adopted in the “Green Deal” package.
How can we ensure the integrity of fund names for investors? A recent example is the German manager DWS, fined $19 million for exaggerating the ESG characteristics of its investment funds. To prevent such issues, the European Securities and Markets Authority (ESMA) published its final report on the names of ESG funds in May 2024, incorporating feedback from stakeholders. Key points include:
Each category must comply with minimum standards to use these keywords based on European legislative guidelines. The main criteria are:
80% of investments must meet social or environmental characteristics (based on the European taxonomy and indicators in Annex II and III of the SFDR directive).
Exclusions from the Paris Aligned Benchmark (PAB) directive:
Controversial weapons
Tobacco production
Violation of UNCG or OECD guidelines
Coal extraction (1%)
Oil extraction (10%)
Gas extraction (50%)
Carbon-intensive electricity production (+100gCO2/kWh)
Exclusions from the Climate Transition Benchmark (CTB), equivalent to points a, b, and c above, also known as "minimum safeguards."
Generalist funds, “S” funds, and “G” funds must apply only the minimum safeguards. "Transition" and "Impact" funds, in addition to the minimum safeguards, must meet the 80% investment threshold with social or environmental characteristics. "Transition" funds must demonstrate a clear and measurable social/environmental trajectory, while "Impact" funds must show that their investments generate a measurable positive impact alongside financial returns.
Funds with an environmental emphasis, including terms like ESG and SRI, must meet all these criteria simultaneously and exclude fossil fuels.
In conclusion, these guidelines will provide investors, especially individual ones, with certain guarantees to select more sustainable investments. Managing controversies will be a crucial challenge for any fund manager offering a range of ESG funds.
Reach out to SESAMm
TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.
Denmark's Danske Bank has announced a sweeping divestment from fossil fuel investments, cutting its portfolio from 2,000 companies to just 270, representing an over 85% reduction in the number of companies in its fossil fuel investment universe. However, its overall exposure to the fossil fuel industry remains stable, thanks to increased investments in some fossil fuel companies. This move, implemented through its Danske Invest fund management unit and Danica pension and insurance business, marks one of the most significant climate-related portfolio adjustments by a major European financial institution.
Assessment Framework
The bank's new methodology centers on a dual evaluation approach. First, it examines management quality, analyzing how companies handle emissions and assess transition risks. Second, it evaluates carbon performance, scrutinizing emissions reduction targets and their alignment with Paris Agreement goals. This comprehensive framework ensures a thorough assessment of companies' climate commitments and actions.
Strategic Approach
Rather than implementing a complete divestment strategy, Danske Bank has adopted a more nuanced approach. While significantly reducing the number of investee companies, the bank has maintained its overall sector exposure by increasing investments in selected companies demonstrating strong transition plans. This strategy focuses particularly on businesses actively working to future-proof their operations against climate-related challenges.
Leadership Perspective
Erik Eliasson, Head of Responsible Investment at Danske Bank, emphasizes the customer-centric approach: "Our new fossil fuels investment approach aligns with the preferences of the majority of our customers while underscoring our commitment to achieving competitive returns on a responsible basis.” Thomas Otbo, CIO at Danske Bank Asset Management, reinforces this position, noting their commitment to maintaining investments in fossil fuel companies that reflect global economic realities while becoming more selective in their choices.
Implementation Flexibility
The bank has designed its strategy to accommodate diverse customer preferences. Some funds remain exempt from the new methodology, while others offer complete fossil fuel exclusion. This flexible approach allows Danske Bank to serve varying client needs while maintaining its broader commitment to sustainable finance. "We firmly believe this to be in the best long-term interest of our investment customers," adds Otbo.
Market Implications
This development signals a sophisticated evolution in how financial institutions approach fossil fuel investments. Rather than implementing blanket exclusions, Danske Bank's approach demonstrates how major financial institutions can balance climate responsibilities with financial returns. The strategy could set a new standard for the industry, showing how banks can significantly reduce fossil fuel exposure while maintaining strategic investments in energy transition leaders.
Looking Forward
As financial institutions face mounting pressure to address climate change, Danske Bank's approach offers a practical template for others in the industry. It demonstrates that major banks can significantly reduce fossil fuel exposure while maintaining their role in financing the global energy transition. This balanced strategy could become a model for other institutions seeking to align their portfolios with climate goals while ensuring continued financial performance.
The bank's innovative approach to fossil fuel investment suggests a new phase in sustainable finance, where sophisticated evaluation methods and flexible implementation strategies replace simple exclusion policies. This development may well shape the future of institutional investment in the energy sector.
SESAMm’s AI Technology Reveals ESG Insights
Discover unparalleled insights into ESG controversies, risks, and opportunities across industries. Learn more about how SESAMm can help you analyze millions of private and public companies using AI-powered text analysis tools.
The secondaries market has tripled in size since 2019, now representing roughly $240 billion in annual volume. LP expectations around diligence - on exclusions, sanctions, mandate compliance, and reputational risk - have risen in lockstep. The window to screen a 300-company portfolio has not. For deal teams operating in an auction environment, the question is no longer how much to screen, but how to do it without becoming the reason a deal slips.
It covers how screening requirements differ by transaction type, what investors are actually screening for, why private market data makes this hard, and what a workflow looks like that can realistically fit inside a 48-hour timeline.
The OECD Guidelines for Multinational Enterprises on Responsible Business Conduct are built into EU sustainable finance rules. The EU Taxonomy's minimum safeguards are based on them, and investors reporting under the Sustainable Finance Disclosure Regulation (SFDR) must show how much of their portfolio contains companies that break them. But the organization behind these Guidelines is better known for its economic forecasts and international education rankings.
The Organization for Economic Co-operation and Development (OECD) is a forum where governments compare policies, review each other's work, and agree on shared standards. This overview covers how the OECD works, what it does, and why its responsible business conduct rules matter for ESG screening and due diligence.
What the OECD is
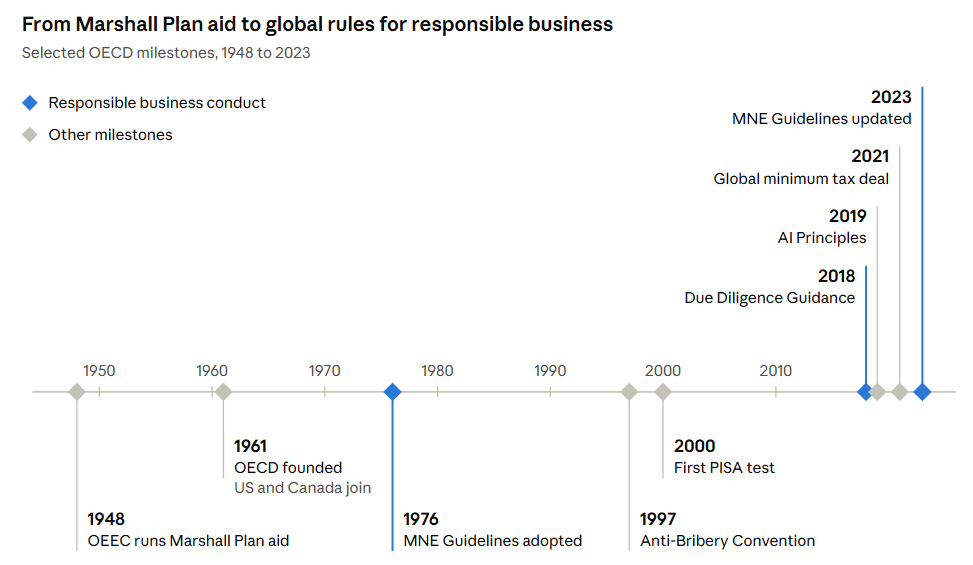
The OECD is based in Paris and has 38 member countries. Rather than lending money or enforcing laws, its role is to set standards that countries agree to follow. It began in 1948 as the Organization for European Economic Co-operation (OEEC), set up to manage Marshall Plan aid. In 1961, it became the OECD, added the United States and Canada as full members, and took on a wider, global economic role. Membership is still growing: Argentina, Brazil, Bulgaria, Croatia, Indonesia, Peru, Romania and Thailand are in the process of joining, with Romania and Bulgaria furthest along as of early 2026.
Three features explain how it has influence:
Decisions by consensus. Decisions are made by the OECD Council, where every member government has a seat, usually by mutual agreement.
Soft law. Most OECD instruments are recommendations, guidelines and declarations, not binding treaties. Their power comes from governments, regulators and markets choosing to adopt them.
Data and peer review. The OECD publishes statistics that can be compared across countries and regularly reviews members' policies. Peer pressure is its main tool for getting countries to comply.
Mathias Cormann has been Secretary-General since 2021. The Council renewed his mandate for a second and final five-year term starting 1 June 2026.
The responsible business conduct framework dates back to 1976, but much of its practical detail is newer, including the 2018 Due Diligence Guidance and the 2023 update of the Guidelines.
What it does
The OECD's work follows the same pattern. Committees of government officials, supported by OECD analysts, first gather comparable data on a policy problem. They then compare how countries deal with it and, when they agree, turn the best approaches into formal instruments. Countries outside the OECD, groups like the G20, and companies often adopt these instruments too, so their reach goes well beyond OECD members. Four flagship instruments show how this works:
Agreed through the OECD/G20 Inclusive Framework and backed by more than 130 jurisdictions. It moves some taxing rights between countries and sets a minimum tax rate, so companies can't shift profits to low-tax places
Education
PISA (Programme for International Student Assessment)
2000
Tests 15-year-olds in reading, maths and science every few years. Countries compare results, and many have reformed their schools because of them
Requires signing countries to make bribing foreign officials in international business a crime. Countries check each other's progress through strict peer review
The first standard agreed between governments on trustworthy AI. Updated in 2024, it has shaped many national and regional AI policies
Behind these instruments is a steady stream of economic analysis: the twice-yearly Economic Outlook, country economic surveys, and statistical databases that governments, central banks and investors all rely on.
Why it matters for ESG Investors
For ESG professionals, the OECD's most important contribution is its framework for responsible business conduct. It sets out what companies are expected to do and how they should show they are doing it. Key elements include:
The MNE Guidelines. First adopted in 1976 and last updated in June 2023, the Guidelines cover human rights, labor relations, the environment, bribery, consumer interests, disclosure and taxation. The 2023 update added clearer expectations on climate change, biodiversity, technology, business integrity and supply chain due diligence, and changed the rules for National Contact Points.
National Contact Points (NCPs). Every government that signs up to the Guidelines runs an NCP. It is a non-judicial complaints process where trade unions, NGOs and others can file a "specific instance" claiming a company has not followed the Guidelines. These cases are public, so they often become ESG controversies themselves. Under the EU Taxonomy's minimum safeguards, an NCP finding against a company counts as a sign of failure.
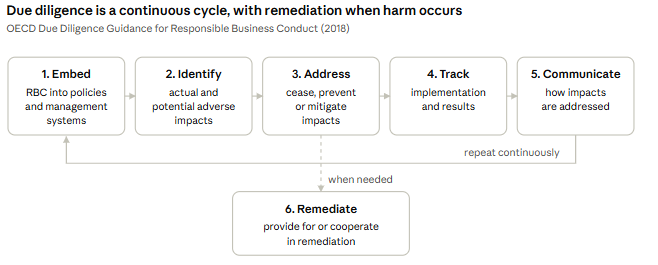
The Due Diligence Guidance. Published in 2018, the OECD Due Diligence Guidance for Responsible Business Conduct turns the Guidelines into a six-step, risk-based process. Companies, and by extension their investors, are expected to follow it.
From soft law to legal requirement. More and more, the framework is the basis for binding rules. The EU Taxonomy's minimum safeguards are directly based on the Guidelines. Two of the SFDR's social principal adverse impact indicators cover breaches of the Guidelines and the lack of processes to check compliance with them (Nordea). The EU Corporate Sustainability Due Diligence Directive also builds on the OECD framework, though OECD Watch says the two only partly match (OECD Watch).
Where controversy data fits. Good due diligence means seeing what is really happening inside a company and its value chain, not just relying on what the company says about itself. AI-driven analysis of public web content at scale can provide that view. SESAMm uses AI on news, NGO reports, blogs and forums to spot ESG controversies as they are reported. This helps investors find adverse impacts (step 2). Its UNGC violation screening is also aligned with SFDR PAI 10, which covers violations of both the UN Global Compact principles and the OECD Guidelines.
Takeaway
The OECD rarely makes headlines, but its standards shape how responsible business conduct is defined, assessed and, more and more, regulated. As the Guidelines become part of EU sustainable finance rules, investors need to back up their assessments with evidence, not just company policy statements. Ongoing, systematic controversy monitoring is one practical way to get that evidence.
Coming soon: OECD Guidelines screening. SESAMm is extending its violation screening to flag controversies linked to the OECD Guidelines for Multinational Enterprises. Request a demo to see it in action.