Insights & Updates

Analysis, market trends, regulation updates and SESAMm news.

Blog thumbnail
Product Updates

Is It the Company or the Sector? Introducing the Sector CES

November 4, 2026
•
5 mins read

Ford’s Controversy Exposure Score (CES) stands at 80 out of 100, in the High Risk band. That tells you how exposed Ford is to ESG controversies in absolute terms. What it doesn’t tell you is whether that exposure is unusual for a large manufacturer, or whether a recent rise is about Ford or about its whole sector.

Until now, answering those questions meant relying on experience or building your own peer group.

Today we’re launching the Sector Controversy Exposure Score (Sector CES), a daily benchmark that shows the typical level of controversy exposure in each sector. It sits right next to a company’s CES on the entity page, for every company mapped to a sector. The CES itself doesn’t change: it remains an absolute score, and the Sector CES adds the sector context alongside it.

A quick refresher: the CES is SESAMm’s ESG rating of a company’s exposure to its highest-impact ESG controversies over up to 24 months. It is expressed on an absolute 0 to 100 scale with five risk bands, from Very Low (0 to 20) to Very High (above 80), and updated every 24 hours. Each controversy’s impact combines its severity, its media coverage (rebased against the company’s own usual coverage), and how recent it is.

What the Sector CES Shows

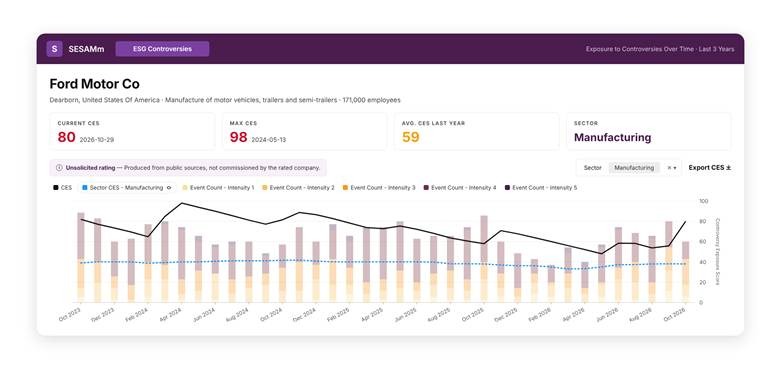
Back to Ford. Over the past three years, its CES has swung from a peak of 98 in spring 2024, down to 48 in May 2026, and back up to 80 today. Over the same period, the Manufacturing Sector CES has held steady at around 40, between roughly 33 and 42.

Two conclusions follow at a glance. Ford has been more exposed to controversies than a typical manufacturer throughout the period. And both its long decline through 2025 and its sharp rebound since May 2026 are specific to Ford: the sector line barely moved.

Ford’s CES (solid line) against the Manufacturing Sector CES (dashed line) on the SESAMm entity page. The CES is an unsolicited rating, produced from public sources and not commissioned by the rated company.

Three Questions, Answered in Seconds

●    Above or below its peers? The gap between the solid and dashed lines shows how a company’s exposure compares with what is typical for its sector.

●    Company or sector? If the company line rises while the sector line stays flat, the issue is company-specific. If both rise together, you are looking at sector-wide pressure.

●    Where is the sector heading? The dashed line on its own tracks how controversy exposure across a whole sector evolves over time.

How It’s Built

The Sector CES is not a new score, and it does not adjust, normalize or re-rate any company’s CES. It is built entirely from the published company-level CES, in three steps:

  1. Classify. Companies are mapped to 21 sectors under the UN’s ISIC Rev. 4 standard. A company active in several sectors can be mapped to more than one.
  2. Select. For each sector, we take the 100 largest companies by number of employees.
  3. Average. Each day, the Sector CES is the simple average of those companies’ published CES. No extra weighting, adjustment, or analyst judgment is applied.

Because it uses the same data, the same scoring, and the same 0 to 100 scale as the company-level CES, a company’s CES and its Sector CES are directly comparable.

Built for Your Workflow

●    Ongoing monitoring: Separate company-specific alerts from sector-wide noise, so your team focuses on what matters.

●    Private markets due diligence: Benchmark a target that has no listed peer group.

●    KYC and supplier onboarding: Use “above sector norm” as a clear, defensible trigger for enhanced review.

The Sector CES is live now in the SESAMm platform. Book a demo to see it on the companies you follow.

About the CES: The Controversy Exposure Score (CES) is an ESG rating issued by SESAMm on an unsolicited basis. Rated companies do not commission the rating or take part in its production. Ratings are produced exclusively from public and licensed public-domain sources.The Sector CES is a contextual benchmark calculated from published company-level CES and does not alter any company’s rating. The full methodology is available here. 

Read More
Regulation

The OECD: An Overview for Investors

October 28, 2026
•
5 mins read

Introduction

The OECD Guidelines for Multinational Enterprises on Responsible Business Conduct are built into EU sustainable finance rules. The EU Taxonomy's minimum safeguards are based on them, and investors reporting under the Sustainable Finance Disclosure Regulation (SFDR) must show how much of their portfolio contains companies that break them. But the organization behind these Guidelines is better known for its economic forecasts and international education rankings.

The Organization for Economic Co-operation and Development (OECD) is a forum where governments compare policies, review each other's work, and agree on shared standards. This overview covers how the OECD works, what it does, and why its responsible business conduct rules matter for ESG screening and due diligence.

What the OECD is

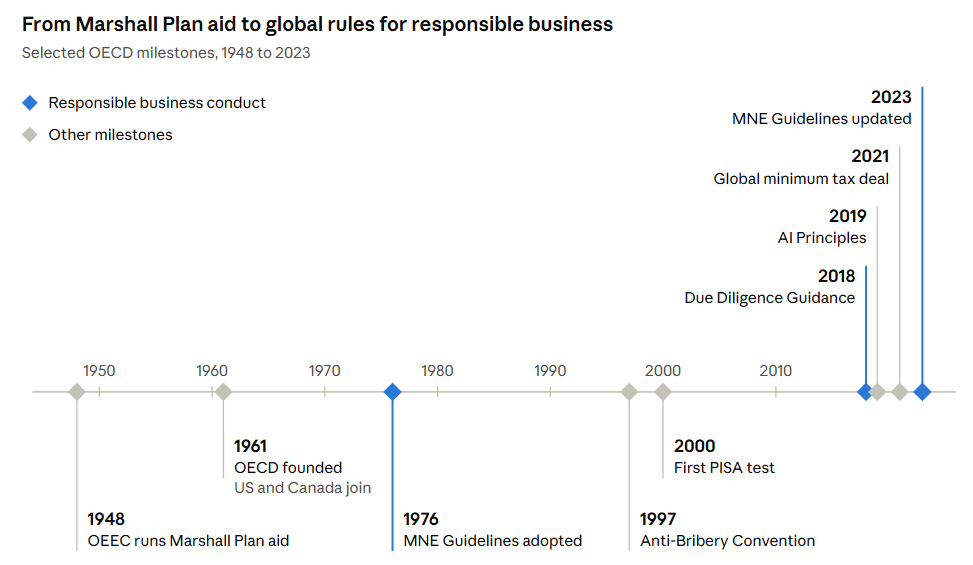
The OECD is based in Paris and has 38 member countries. Rather than lending money or enforcing laws, its role is to set standards that countries agree to follow. It began in 1948 as the Organization for European Economic Co-operation (OEEC), set up to manage Marshall Plan aid. In 1961, it became the OECD, added the United States and Canada as full members, and took on a wider, global economic role. Membership is still growing: Argentina, Brazil, Bulgaria, Croatia, Indonesia, Peru, Romania and Thailand are in the process of joining, with Romania and Bulgaria furthest along as of early 2026.

Three features explain how it has influence:

  • Decisions by consensus. Decisions are made by the OECD Council, where every member government has a seat, usually by mutual agreement.
  • Soft law. Most OECD instruments are recommendations, guidelines and declarations, not binding treaties. Their power comes from governments, regulators and markets choosing to adopt them.
  • Data and peer review. The OECD publishes statistics that can be compared across countries and regularly reviews members' policies. Peer pressure is its main tool for getting countries to comply.

Mathias Cormann has been Secretary-General since 2021. The Council renewed his mandate for a second and final five-year term starting 1 June 2026.

The responsible business conduct framework dates back to 1976, but much of its practical detail is newer, including the 2018 Due Diligence Guidance and the 2023 update of the Guidelines.

What it does

The OECD's work follows the same pattern. Committees of government officials, supported by OECD analysts, first gather comparable data on a policy problem. They then compare how countries deal with it and, when they agree, turn the best approaches into formal instruments. Countries outside the OECD, groups like the G20, and companies often adopt these instruments too, so their reach goes well beyond OECD members. Four flagship instruments show how this works:

Area Flagship instrument Since What it does and why it matters
Tax Two-pillar solution, including a 15% global minimum corporate tax 2021 Agreed through the OECD/G20 Inclusive Framework and backed by more than 130 jurisdictions. It moves some taxing rights between countries and sets a minimum tax rate, so companies can't shift profits to low-tax places
Education PISA (Programme for International Student Assessment) 2000 Tests 15-year-olds in reading, maths and science every few years. Countries compare results, and many have reformed their schools because of them
Integrity Anti-Bribery Convention 1997 Requires signing countries to make bribing foreign officials in international business a crime. Countries check each other's progress through strict peer review
Technology OECD AI Principles 2019 The first standard agreed between governments on trustworthy AI. Updated in 2024, it has shaped many national and regional AI policies

‍

Behind these instruments is a steady stream of economic analysis: the twice-yearly Economic Outlook, country economic surveys, and statistical databases that governments, central banks and investors all rely on.

Why it matters for ESG Investors

For ESG professionals, the OECD's most important contribution is its framework for responsible business conduct. It sets out what companies are expected to do and how they should show they are doing it. Key elements include:

The MNE Guidelines. First adopted in 1976 and last updated in June 2023, the Guidelines cover human rights, labor relations, the environment, bribery, consumer interests, disclosure and taxation. The 2023 update added clearer expectations on climate change, biodiversity, technology, business integrity and supply chain due diligence, and changed the rules for National Contact Points.

National Contact Points (NCPs). Every government that signs up to the Guidelines runs an NCP. It is a non-judicial complaints process where trade unions, NGOs and others can file a "specific instance" claiming a company has not followed the Guidelines. These cases are public, so they often become ESG controversies themselves. Under the EU Taxonomy's minimum safeguards, an NCP finding against a company counts as a sign of failure.

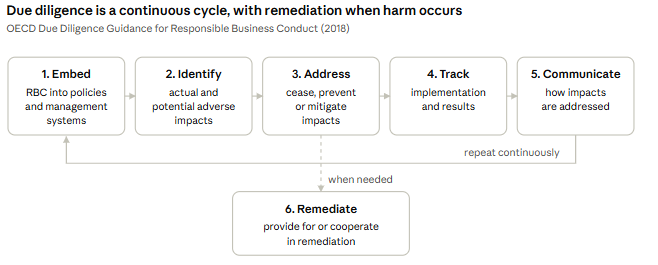
The Due Diligence Guidance. Published in 2018, the OECD Due Diligence Guidance for Responsible Business Conduct turns the Guidelines into a six-step, risk-based process. Companies, and by extension their investors, are expected to follow it.

From soft law to legal requirement. More and more, the framework is the basis for binding rules. The EU Taxonomy's minimum safeguards are directly based on the Guidelines. Two of the SFDR's social principal adverse impact indicators cover breaches of the Guidelines and the lack of processes to check compliance with them (Nordea). The EU Corporate Sustainability Due Diligence Directive also builds on the OECD framework, though OECD Watch says the two only partly match (OECD Watch).

Where controversy data fits. Good due diligence means seeing what is really happening inside a company and its value chain, not just relying on what the company says about itself. AI-driven analysis of public web content at scale can provide that view. SESAMm uses AI on news, NGO reports, blogs and forums to spot ESG controversies as they are reported. This helps investors find adverse impacts (step 2). Its UNGC violation screening is also aligned with SFDR PAI 10, which covers violations of both the UN Global Compact principles and the OECD Guidelines.

Takeaway

The OECD rarely makes headlines, but its standards shape how responsible business conduct is defined, assessed and, more and more, regulated. As the Guidelines become part of EU sustainable finance rules, investors need to back up their assessments with evidence, not just company policy statements. Ongoing, systematic controversy monitoring is one practical way to get that evidence.

‍

Coming soon: OECD Guidelines screening. SESAMm is extending its violation screening to flag controversies linked to the OECD Guidelines for Multinational Enterprises. Request a demo to see it in action.

Sources

At SESAMm Day 2026 in Paris, CEO and co-founder Sylvain Forté closed the morning with what SESAMm shipped this year and what comes next. One idea ran through the whole session: controversy data is moving out of dashboards and into the places where decisions are made, from AI assistants to automated reports and day-to-day risk workflows.

Investment, credit and compliance teams increasingly draft their analysis in ChatGPT, Claude or Copilot, and assemble their final memo there. "We need platforms and graphical interfaces less and less," Sylvain told the audience. "More and more, everything happens in AI agents and AI conversations." This year's launches follow from that view.

Bring SESAMm data into your AI assistant

One of the most important launches of the year was the SESAMm MCP server, released in May 2026. MCP (Model Context Protocol) lets AI assistants call external data sources directly. With it, teams query SESAMm controversy data in natural language from ChatGPT, Claude or Copilot, without leaving the conversation.

Unlike an API integration, it needs no IT project. Users connect the server from their interface and start asking questions, and they can combine SESAMm data with the other sources their assistant already reaches, such as company financials.

A typical case comes from credit. A bank's credit committee expects a report in a fixed structure, which the analyst can define once in their assistant. What was missing was the controversy information. When the report is drafted, the assistant now pulls it straight from the SESAMm MCP server.

Screen and assess in minutes, not days

SESAMm puts its AI expertise to work in ready-to-use reports. Built with clients and partners around market best practice, they cover what a complete analysis should contain:

  • ESG due diligence,
  • legal,
  • compliance and M&A reviews,
  • good governance assessments under SFDR,
  • exclusion screening across around 30 criteria, from tobacco to controversial weapons.

This year, reports became 2.5 times faster, enabling faster due diligence and business involvement screening.

That speed matters most where volumes are high. Exclusion screening has become one of the most used modules in the platform, with thousands of transactions screened every week as private equity secondaries grow.

Answer go or no-go at the scale of a large corporate

Beyond finance, SESAMm increasingly works with large corporates and banks on supply chain and counterparty risk. The need is lighter but much larger in volume: a go or no-go before onboarding a new supplier, client or insured party, across hundreds of thousands of transactions.

For these teams, an AI module fills in the client's own risk questionnaire. A typical question is whether a company has been involved in a human rights issue in the past three years, under the client's risk criteria. The module returns the answer, the level of risk and its justification, with the underlying controversy data attached.

Allianz Commercial uses this approach in its underwriting. Underwriters enter a company identifier and, in under a minute, get answers to predefined sustainability and reputational due diligence questions directly in their existing interface. Each answer comes with a yes or no, its justification and evidence that meets Allianz Commercial's audit trail requirements, and the setup supports the assessment of hundreds of thousands of companies a year. Read the Allianz Commercial case study.

Regulation is driving this demand. Germany's Supply Chain Due Diligence Act is a major driver today, and the EU Corporate Sustainability Due Diligence Directive (CS3D) points the same way.

Read company risk at a glance

Teams screening large portfolios need to see where risk sits without reading every controversy. The platform's risk indicator now uses the Max CES, the peak of a company's Controversy Exposure Score, so a serious controversy from a few years ago stays visible even after the score has declined. Controversy summaries add the main themes for each company, giving LPs and funds of funds a fast go or no-go across tens of thousands of holdings. And when a committee needs the full picture, a company's complete controversy page can be exported as a PDF in about 10 seconds.

Build regulation into the product

The EU regulation on ESG ratings kept SESAMm busy this year. SESAMm notified the European Securities and Markets Authority (ESMA) directly and built the requirements into its systematic processes rather than treating them as a one-off project.

In practice, that means millions of companies were notified. Each receives access to the platform to review its controversies and scores. Automating this step let SESAMm keep its full coverage without a matching rise in costs.

For clients, the result is transparency and stability. The methodology is public on the SESAMm website. Major changes will be announced in advance and go through public consultation, so scores will not shift overnight.

What comes next

Three developments are coming to the platform in the months ahead:

  • Portfolio and sector CES. The portfolio CES, now available, rates the risk of a specific portfolio or investment universe. The sector CES compares a company with its peers. It answers a frequent request in sectors where every player is exposed, and where the question is whether a company does better or worse than the rest.
  • OECD screening. Alongside the existing screening for UN Global Compact violations, a screening against the OECD Guidelines for Multinational Enterprises is coming in the next few months.
  • MCP in AI marketplaces. The SESAMm MCP server will be listed in the ChatGPT and Claude marketplaces, so any SESAMm license holder can add it in one click.

To see these features in action or connect the MCP server to your AI assistant, request a demo or contact us at contact@sesamm.com.

‍

Analysis

From Signal to Rating: A Q&A with Inrate and SESAMm

October 14, 2026
•
5 mins read

On September 30, we co-hosted an executive breakfast with Inrate in Zurich. The discussion kept coming back to one idea. Double materiality is no longer held back by a lack of data. It is held back by the judgment needed to make sense of data that is vast, contradictory, and often late. We asked Saurabh Srivastava, Managing Director at Inrate, and Sylvain Forté, CEO of SESAMm, to pick up where they left off. How does a controversy become a rating? How fast should that happen? And what can AI do along the way, and what can it not?

Saurabh, you split the data problem into three: contradiction, fragmentation and contested data. What does each look like for a rating agency?

Saurabh Srivastava, Inrate: All three come up every day. Contradiction is when the same emissions figure differs between a company's sustainability report, its CDP response and its local filings. Fragmentation is subtler: financed emissions, for example, are spread across asset classes, so no single source gives you the full picture. Contested data is the hardest of all. A supplier dispute is reported differently by each party, and a court may only settle it years later.

Each of these needs a judgment call, and each judgment has to be traceable and auditable. That's why we use AI for triangulated quality assurance, checking every data point against several independent sources, while an analyst makes the final call and documents it.

Sylvain, which of those can AI actually solve today, and which still need a human?

Sylvain Forté, SESAMm: 

Fragmentation is where AI helps most, because it's a problem of scale. Pulling scattered information together across millions of companies and around 100 languages is not something a team can do by hand, and no one should be writing summaries by hand anyway.

On contradiction, AI gives you an independent view. Companies often report much later than what is already visible in the public domain, so what journalists and NGOs are saying is a useful check on what a company discloses.

Contested data is where the story keeps moving. Take a local NGO accusing a factory of polluting a river. The story may only appear in the local press, and it isn't always clear which company the factory belongs to. AI finds it, links it to the right company and keeps following it as it develops: whether a fine is imposed, whether a court rules, how many people are affected. All of that feeds a first severity score.

Throughout this process, humans stay in the loop at two levels. Every day, our ESG analysts conduct quality control and use what they find to keep refining the algorithms. Reviewing everything by hand would be impossible, and that's the whole point of AI at scale. And the final judgment call stays with the people using the data. A secondaries investor that inherits 500 companies can use AI to narrow the list down to five, then make the call on those five itself. Our principle is AI for scale, humans for validation. 

Saurabh, Inrate sources its controversy data from SESAMm. What happens once a signal reaches you?

Saurabh: What we receive from SESAMm is the events flow: controversies picked up across a huge range of sources, often in the local language, matched to the right company, classified by risk type, and given a first severity score. Our job is to translate those signals into what they mean for our rating, and that's where our own controversy framework comes in. We look at how severe and credible an event is, how long-lasting it is, and whether the company has taken corrective action. 

A controversy is also never assessed in isolation. It's one of three pillars in our rating, alongside our business activity analysis and our disclosure analysis. Controversies matter because they show what's happening outside of what a company reports. You can trust disclosures, but you need to verify them. Put simply, SESAMm tells us what is happening, and we decide what it means for the company's impact and risk. 

Sylvain, controversy signals tend to move before ratings do. Is that a problem for ratings?

Sylvain: The evidence does point that way. Several studies by our quantitative clients found that controversy signals tend to anticipate ESG rating downgrades, with statistically significant results.

But I wouldn't read that as ratings being slow. Ratings are built to be stable because investors use them to allocate capital, and some facts stay contested for years. The value is in having both: an early signal for monitoring, and a stable rating you can build a portfolio on. What matters is that a serious controversy reaches the people making the rating quickly, so they can decide whether it warrants a review.

Saurabh, you called the falling cost of assembling impact evidence "the most interesting thing happening for us today." Why?

Saurabh: Because of the contrast with financial materiality. There, we were already well served by AI and machine learning: the information was structured, and there was always a strong P&L reason to use it. Impact is different. No company publishes its externalities, and none ever will, so you have to piece that picture together from local-language filings, trade documents and many other sources. Not long ago, much of that was collected and analyzed by hand. Now a lot of it reaches us already indexed and ready for an analyst to use, so the cost of assembling that evidence has come right down. Add growing access to geospatial data, and we can back an impact claim with far more evidence, and far more confidence, than we could a few years ago. 

Sylvain, where does local-language data add the most to that picture?

Sylvain: Inrate's ratings start from what companies do, not only from what they disclose, and that's where local-language data adds the most. A dispute at a supplier or a protest against a project is usually reported first in the local press, and sometimes only there. 

It matters even more where there's no disclosure at all. Private companies and infrastructure projects often publish no sustainability report. For due diligence on them, outside-in data is usually enough, even if it isn't enough for a full score. Infrastructure is a good example of demand running ahead of supply: insurers in particular want to understand underwriting risk on projects that traditional coverage barely reaches.

Saurabh, disclosure is shrinking, with the EU Omnibus narrowing reporting and some Swiss large caps disclosing less. Can providers close the gap?

Saurabh: Partly. The duty is shifting to providers, and better estimation, for example, on scope 3 categories, and growing access to geospatial data make up for part of what's being lost. But there are limits. Biodiversity and physical risk are local by nature, and an estimate can't fully replace information about a specific site.

The further down the value chain you go, the darker it gets. Tier-3 and tier-4 suppliers are still largely opaque, for investors and often for the companies themselves.

Sylvain, can AI shed light on those deeper tiers?

Sylvain: It's the only realistic way. A company with 1,000 suppliers already has over a million relationships by tier 3, and risk travels through those chains, from private suppliers into public portfolios. No team can map that by hand. It takes AI-assisted coverage and navigation. 

And it's happening at an odd moment. Corporate sustainability reporting is being scaled back, while ESG rating providers now face new authorization and transparency rules. Providers are being asked to fill more gaps and, at the same time, to be more open about how they fill them. That makes the combination we've described, AI for scale with accountable human judgment on top, more important, not less.

‍

About SESAMm. SESAMm is an AI company specializing in controversy monitoring and ESG risk. It analyzes over 35 billion documents in around 100 languages to cover 5 million companies and infrastructure projects across public and private markets. sesamm.com

About Inrate. Inrate is an independent Swiss sustainability rating agency. Its impact ratings, screening, regulatory and thematic datasets, and stewardship services start from what companies do, not only what they disclose. inrate.com

‍

Fill out the form to get a full recap of the event

Over the past years, the for-profit childcare sector in France and the United States has moved from a largely quiet corner of the healthcare and social assistance industry into a subject of sustained public, regulatory, and investor scrutiny. Criminal convictions, government inspectorate findings, parliamentary inquiries, securities litigation, and a wave of investigative journalism ask the same question: Does the ownership and financing model that now dominates the sector come at the direct expense of child safety and care quality?

To help answer that question, we took a look at the controversies surrounding the industry and examined that question through media and ESG-controversy data, tracking mention volume and controversy-tagged coverage across five major operators spanning both French and US Markets, from January 2019 through August 2026:

This article combines whole-market trends with a narrower, controversy-specific signal to distinguish genuine escalation in safety and governance failures from routine growth in industry coverage, studying the case of one of the sector's most heavily implicated operators: People & Baby.

For-profit Childcare Market ESG Controversies

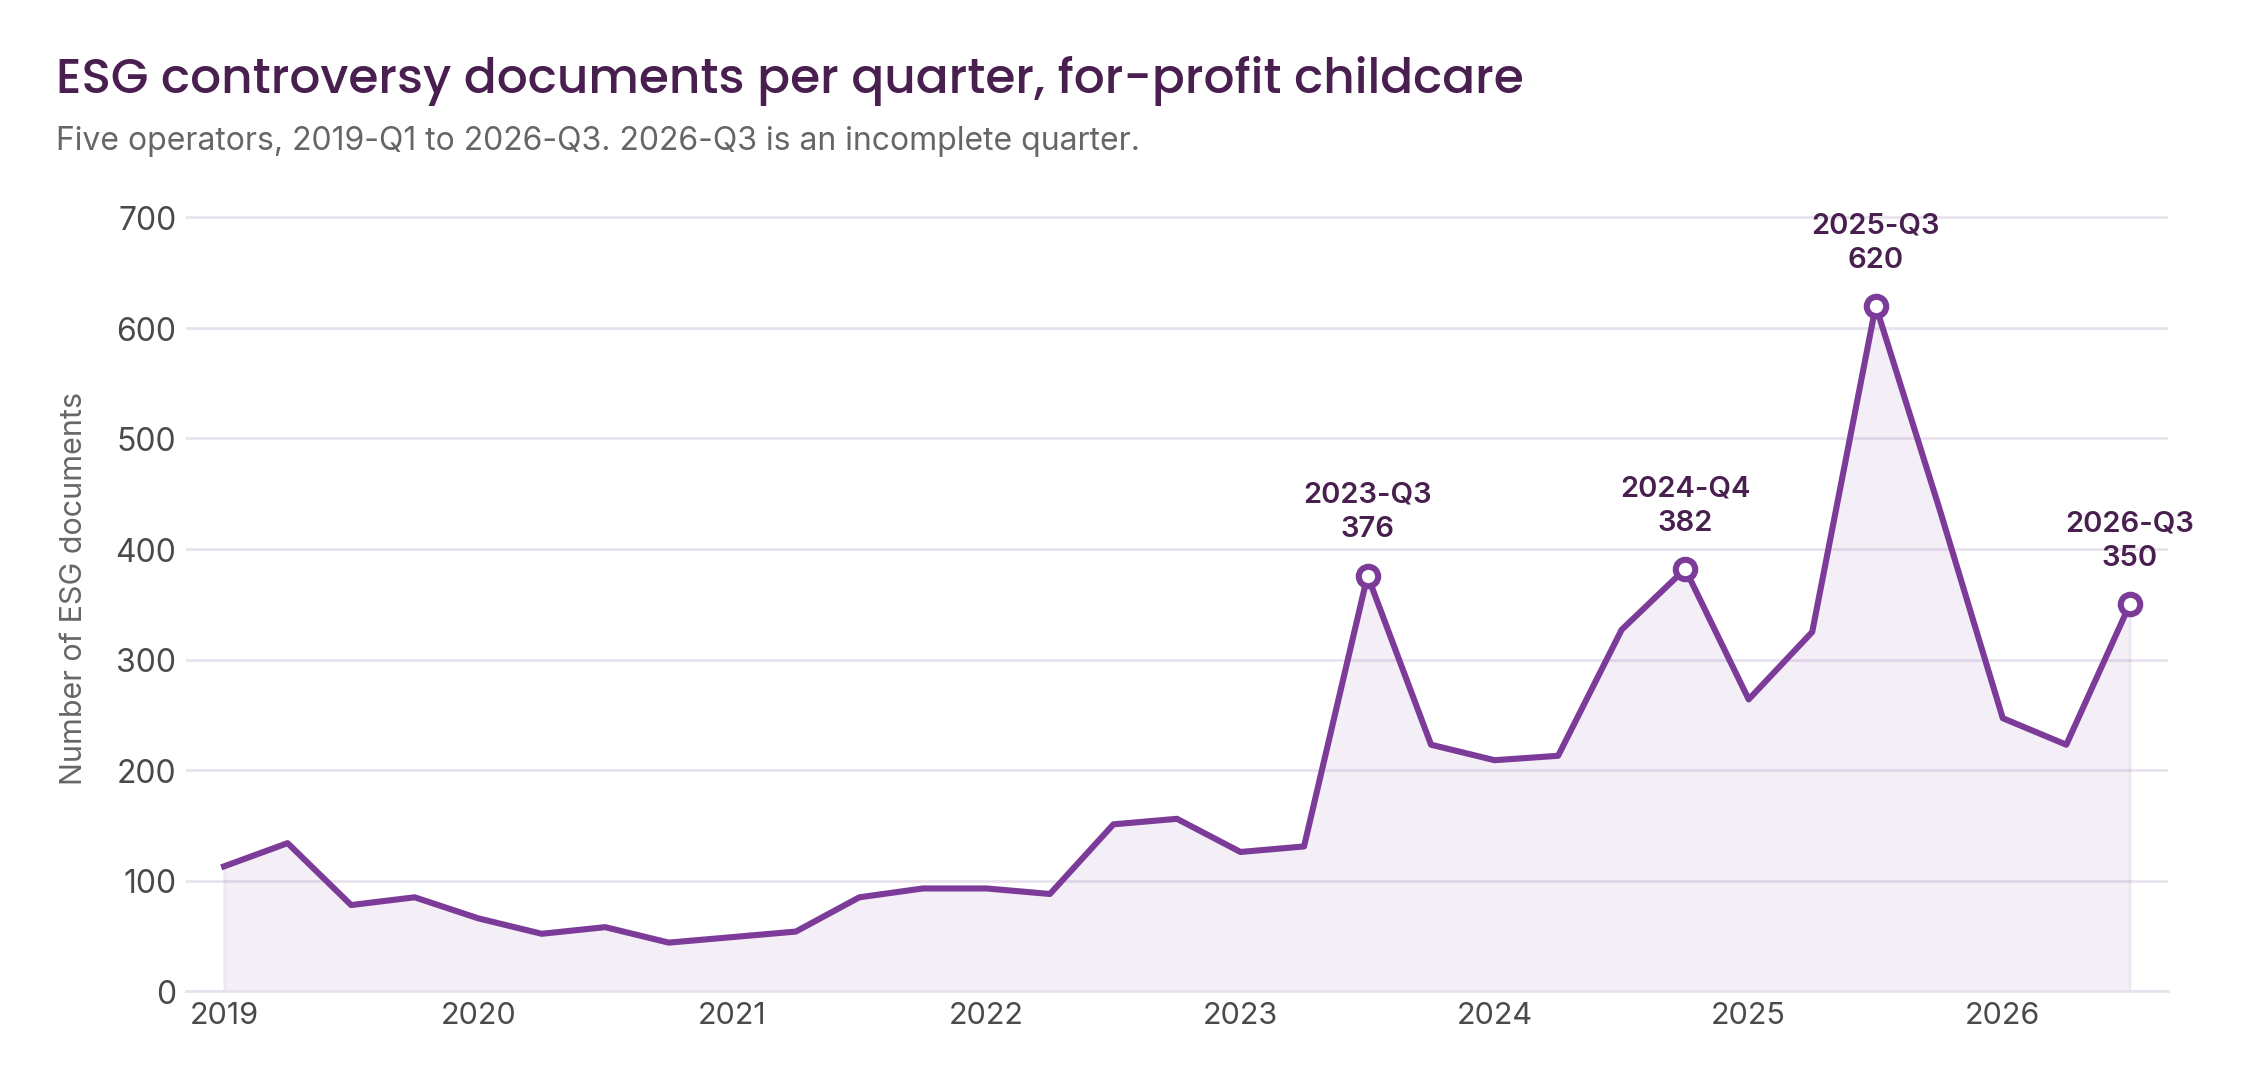
Figure 1 - ESG controversy documents per quarter across the five operators, 2019-Q1 - 2026-Q3. 2026-Q3 is an incomplete quarter.

Mention volume holds flat from 2019 into early 2022, when pandemic closures and suspended inspections suppressed the incidents that generate coverage, though not the underlying risk. The break came in June 2022, when an infant died at a People & Baby crèche in Lyon, France after an employee gave her caustic drain cleaner. A staff member received a 25-year criminal sentence, and the government commissioned a sector-wide review. From 2023 onward, the pattern stops reverting, and each cycle peaks higher than the one before it.

In 2023, a sector-wide IGAS report concluded that the industry showed "institutionalized mistreatment" and called for a "cultural change." Five months later, in September, two investigative books appeared in the same week: Le Prix du Berceau and Babyzness, each documenting understaffing, restricted meals, and abuse. Their reach was sectoral rather than targeted, and the parliamentary hearings and regulatory crackdowns that followed pulled in operators with no incident of their own.

The following year compounded the effect on both sides of the Atlantic. Les Ogres (Victor Castanet, September 18, 2024), a 416-page investigation built over two and a half years on 200 witnesses and internal whistleblowers, centered on People & Baby but alleged complicity from municipalities and senior government officials who looked the other way. It triggered government-wide nursery reviews, and its ripple effect continued to build through the quarter. Within the same period, a Wisconsin television investigation found that an Oak Creek KinderCare location where an 11-month-old had tested positive for cocaine earlier that year had accumulated more than two dozen prior violations, including staff aggression and undocumented injuries. The state suspended the center's license, then revoked it. KinderCare had listed that October.

The largest spike of the period lands in 2025, and it is where two operators' exposure changes character. KinderCare faces a wave of securities fraud lawsuits, consolidated in Gollapalli v. KinderCare, which alleges that SEC registration filings promised "the highest quality care possible" while the Oak Creek violations were accumulating. Once an operator is listed, a safety failure becomes a disclosure failure. In France, an IGAS audit of La Maison Bleue, distinct from the 2023 sector report, documented systemic quality-of-care issues, accounting anomalies, and payroll optimizations designed to maximize public subsidy payments at the expense of staffing ratios. State auditors characterized some findings as potentially criminal, regulators referred the operator to a prosecutor, and the report prompted demands for further audits.

For People & Baby the consequences moved from reputational to structural: the group entered court-supervised accelerated safeguard proceedings, handing majority ownership to creditor fund Alcentra and slating dozens of locations for closure. The sequence runs into 2026 with KinderCare's $33M lawsuit over a child abuse cover-up, prosecutors seeking an investigation into People & Baby, and Babilou sued for negligence over a child's injury.

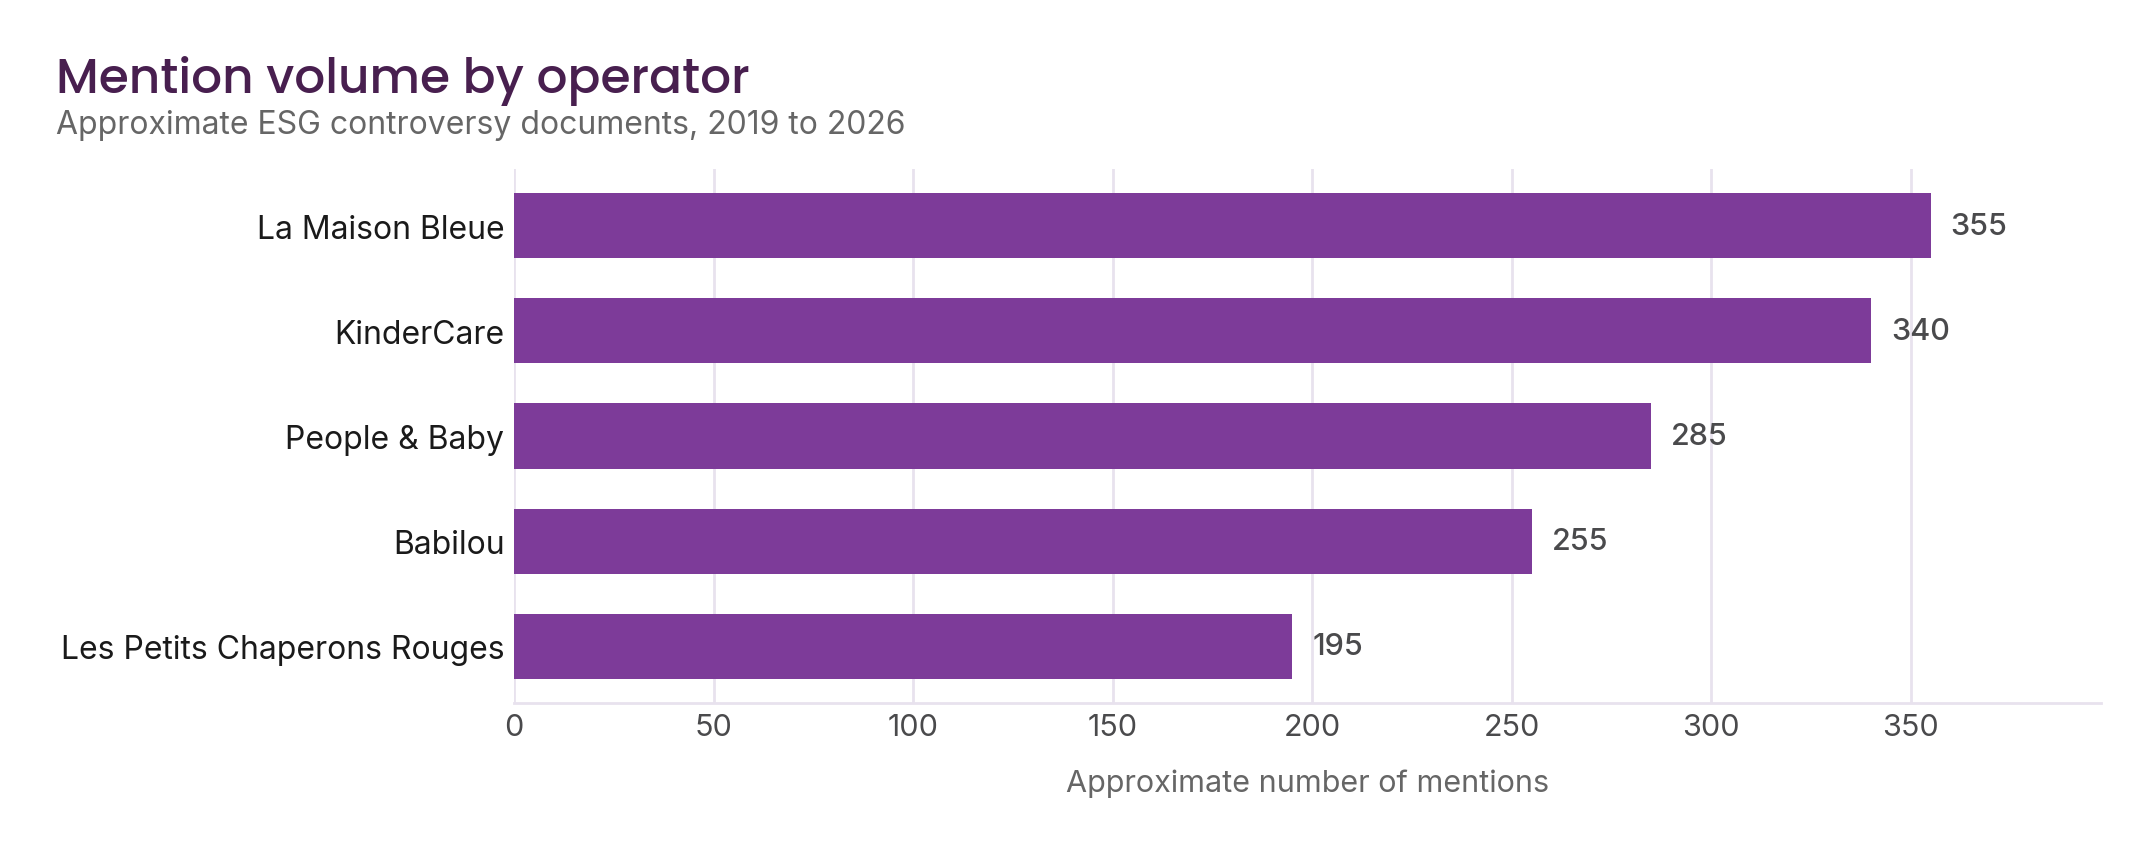
Figure 2. Mention volume by operator, 2019 to 2026 (approximate).

The signal is the floor, not the peaks. Baseline mention volume rose two to three times over and never returned to its prior level, and that elevated floor separates the five operators into two groups. People & Baby, La Maison Bleue, and KinderCare each triggered an event that radiated outward, and each carries a different kind of exposure: an ownership change, an unresolved regulatory referral, and investor litigation.

Babilou and Les Petits Chaperons Rouges never appear on that timeline, which is the point. Babilou carries scrutiny of its own over micro-crèche operating margins and the strikes in Montauban, but no corporate-level criminal indictment. Les Petits Chaperons Rouges draws enforcement at the site level rather than the group level, through the state-ordered emergency closure and admitted operational "dysfunctions" in National Assembly testimony, while remaining cited for the gap between parent company Grandir's expansion and site-level compliance. Neither has restructured, and both sit above the floor anyway.

Top Subrisks

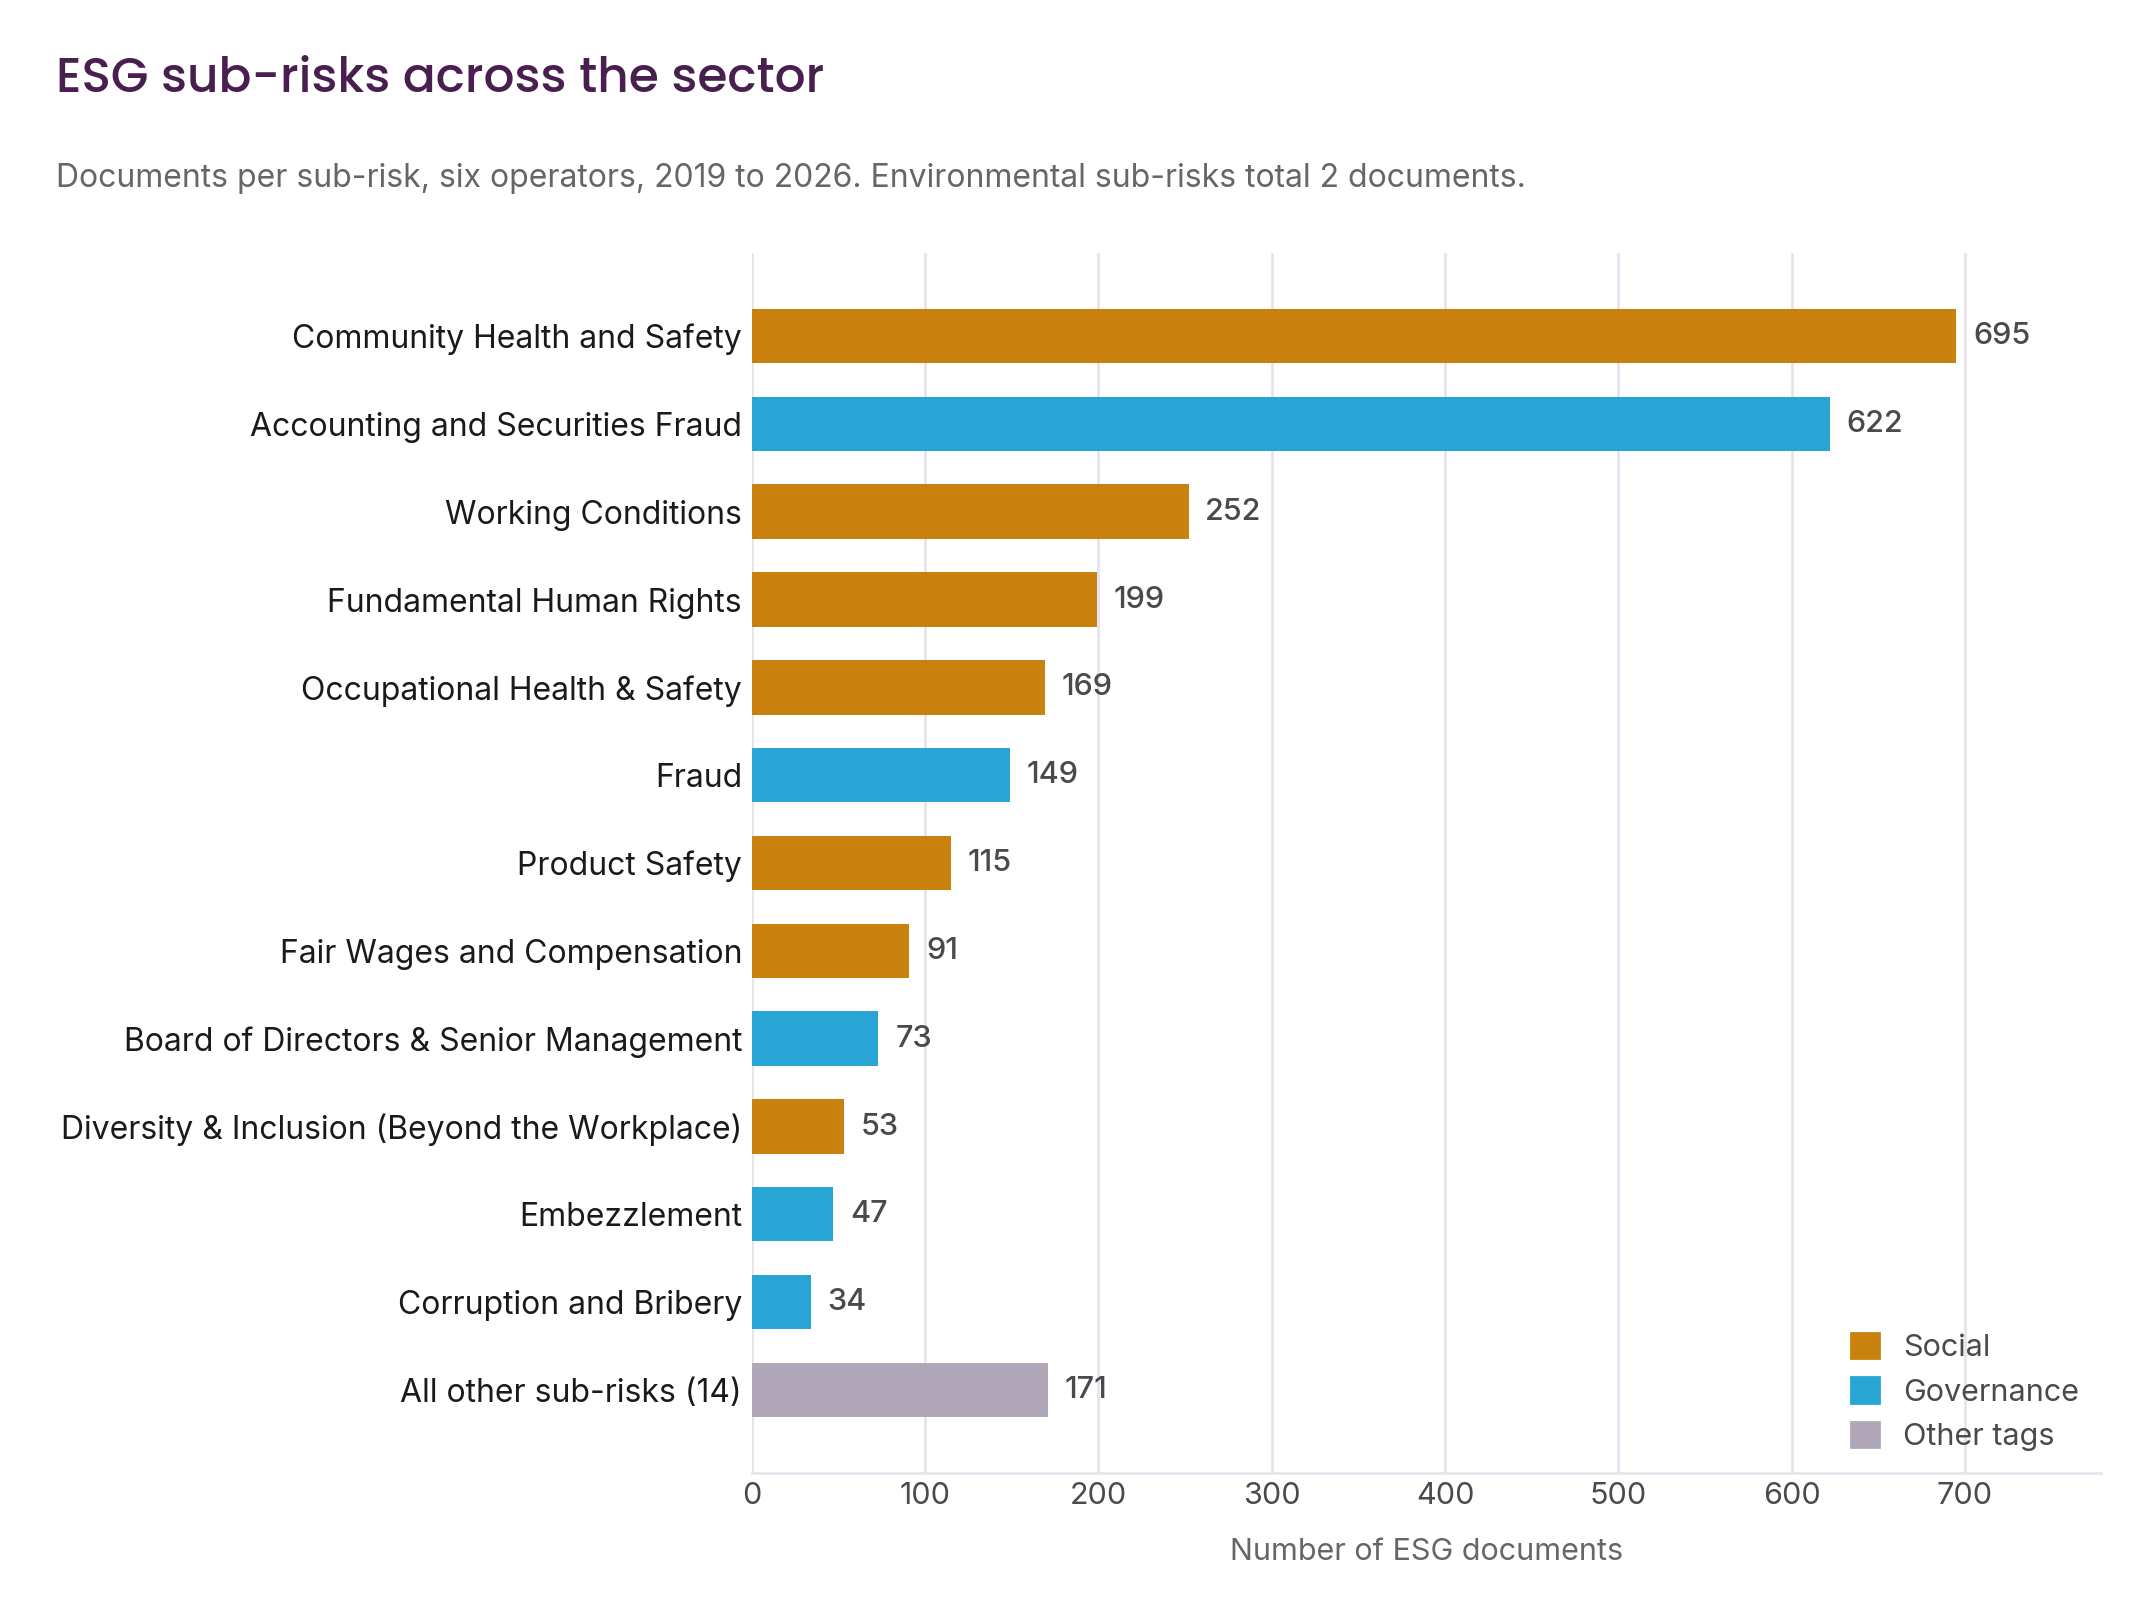
Figure 3 - ESG sub-risk distribution across the five operators (approximate document counts).

ESG risk exposure in the for-profit childcare sector concentrates almost entirely in the social pillar, with a minor governance exposure and an absence of environmental risks. This reflects a business model in which labor practices and care quality directly determine commercial and reputational viability.

Case Study: People & Baby

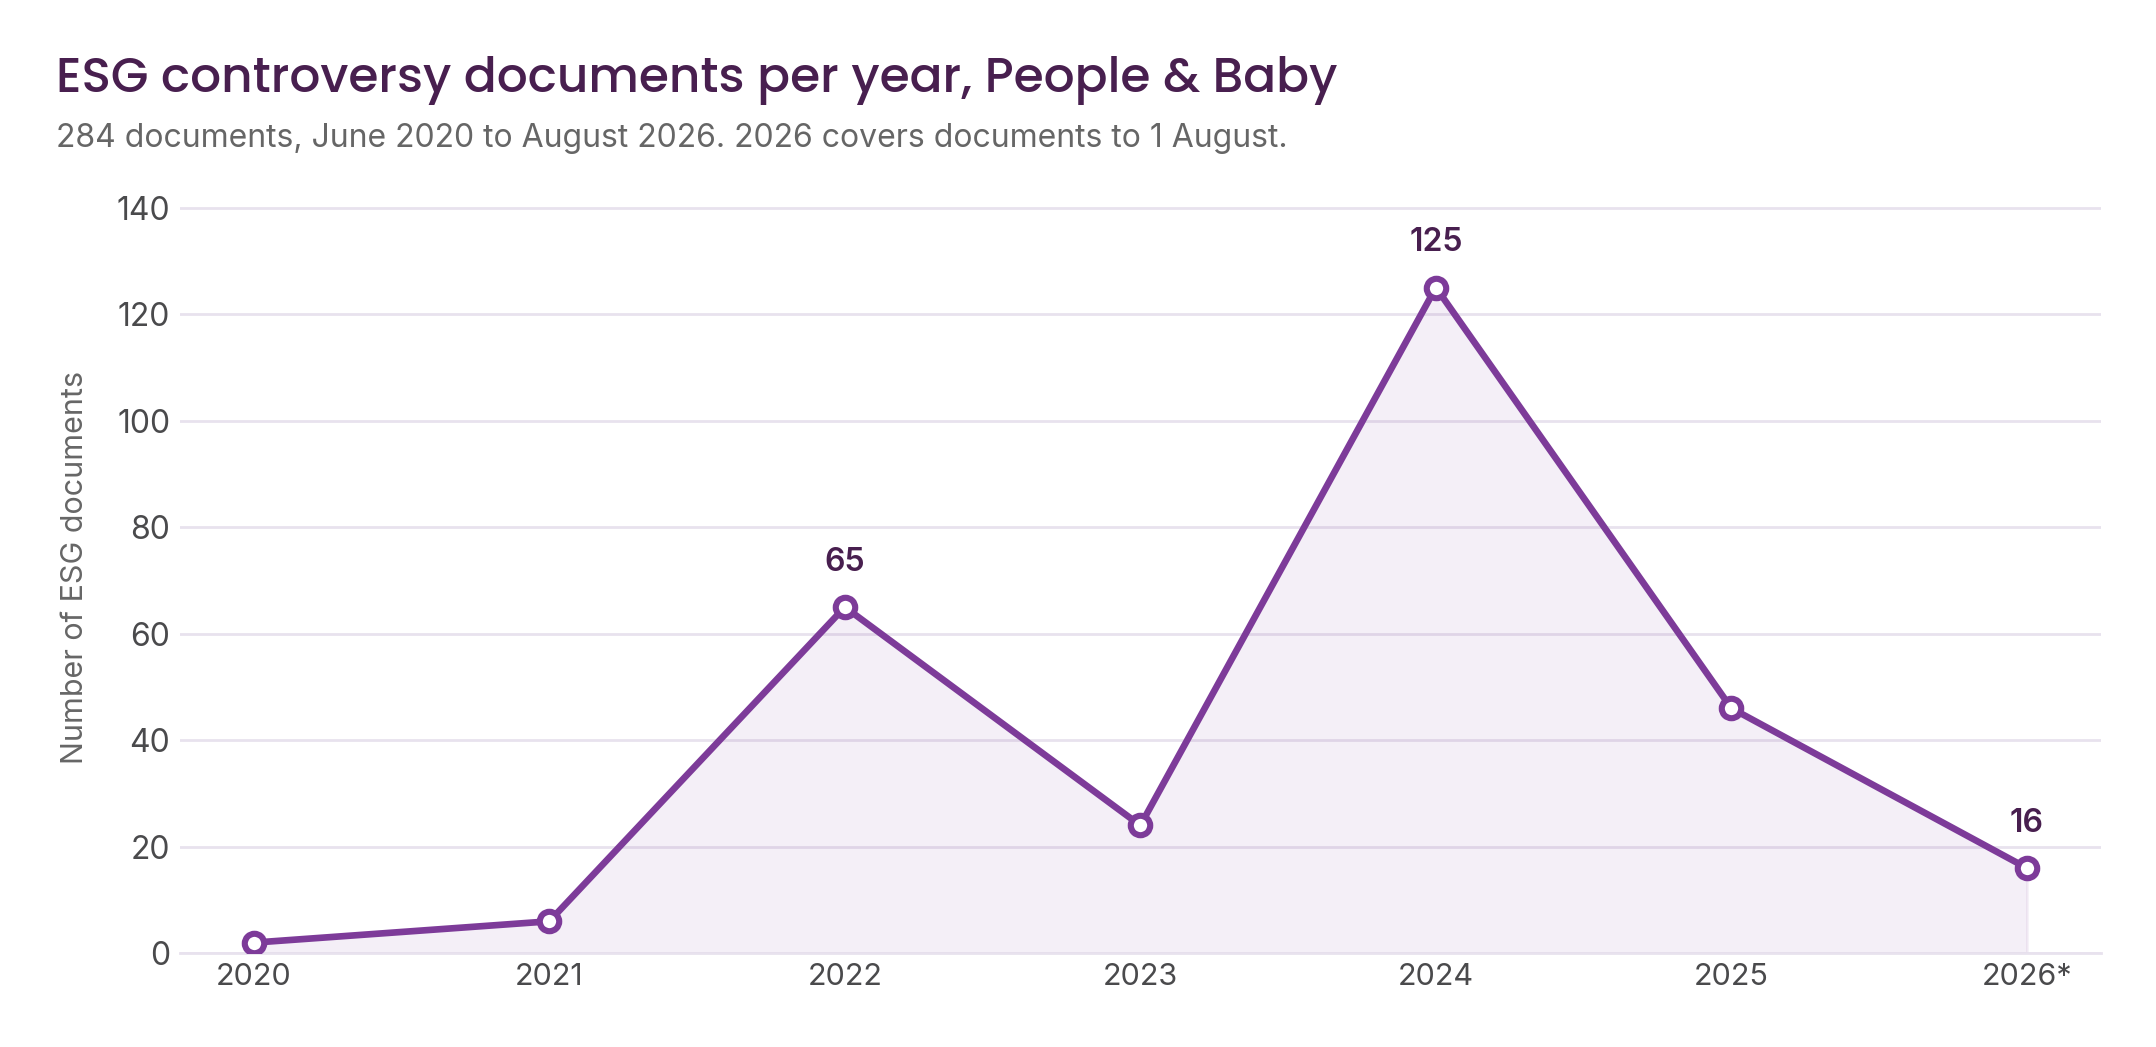
Figure 4 - ESG controversy documents per year, People & Baby (284 documents, June 2020 – August 2026).

People & Baby is a France-based childcare provider headquartered in Paris, operating approximately 600 crèches and reporting revenue of about USD 119 million.

People & Baby’s ESG exposure is defined above all by repeated child-safety and regulatory-compliance failures, including abuse allegations, a child death, and inspections identifying significant deficiencies, while financial restructuring and sustained labor disputes add pressure to the company’s operating and governance profile.

The mention curve describes a company hit by two distinct crises rather than one continuous controversy. Through 2020 and 2021, the exposure was latent, visible only in local and union-press labor and discrimination litigation reported by outlets such as anti-k.org and rapportsdeforce.fr, none of which were high-authority sources. The company's own peak arrives a year before the sector's, which is the point of the case: People & Baby was the operator whose crisis set the wave that the other four were later caught in.

The first spike came in 2022 as a child-safety crisis, built on the death of an infant in a Lyon crèche and the temporary closure of a Bordeaux facility, and accompanied by government sanction threats and staff testimony on conditions. Coverage receded through 2023, then overtook that peak in 2024 on a crisis of a different character, financial and legal rather than clinical: Victor Castanet's Les Ogres, the Anticor complaint over misappropriated public funds, the opening of a Paris prosecutor's investigation, and the accelerated safeguard procedure. What remains through the first half of 2026 is thinner and still declining, though none of it has been resolved. 

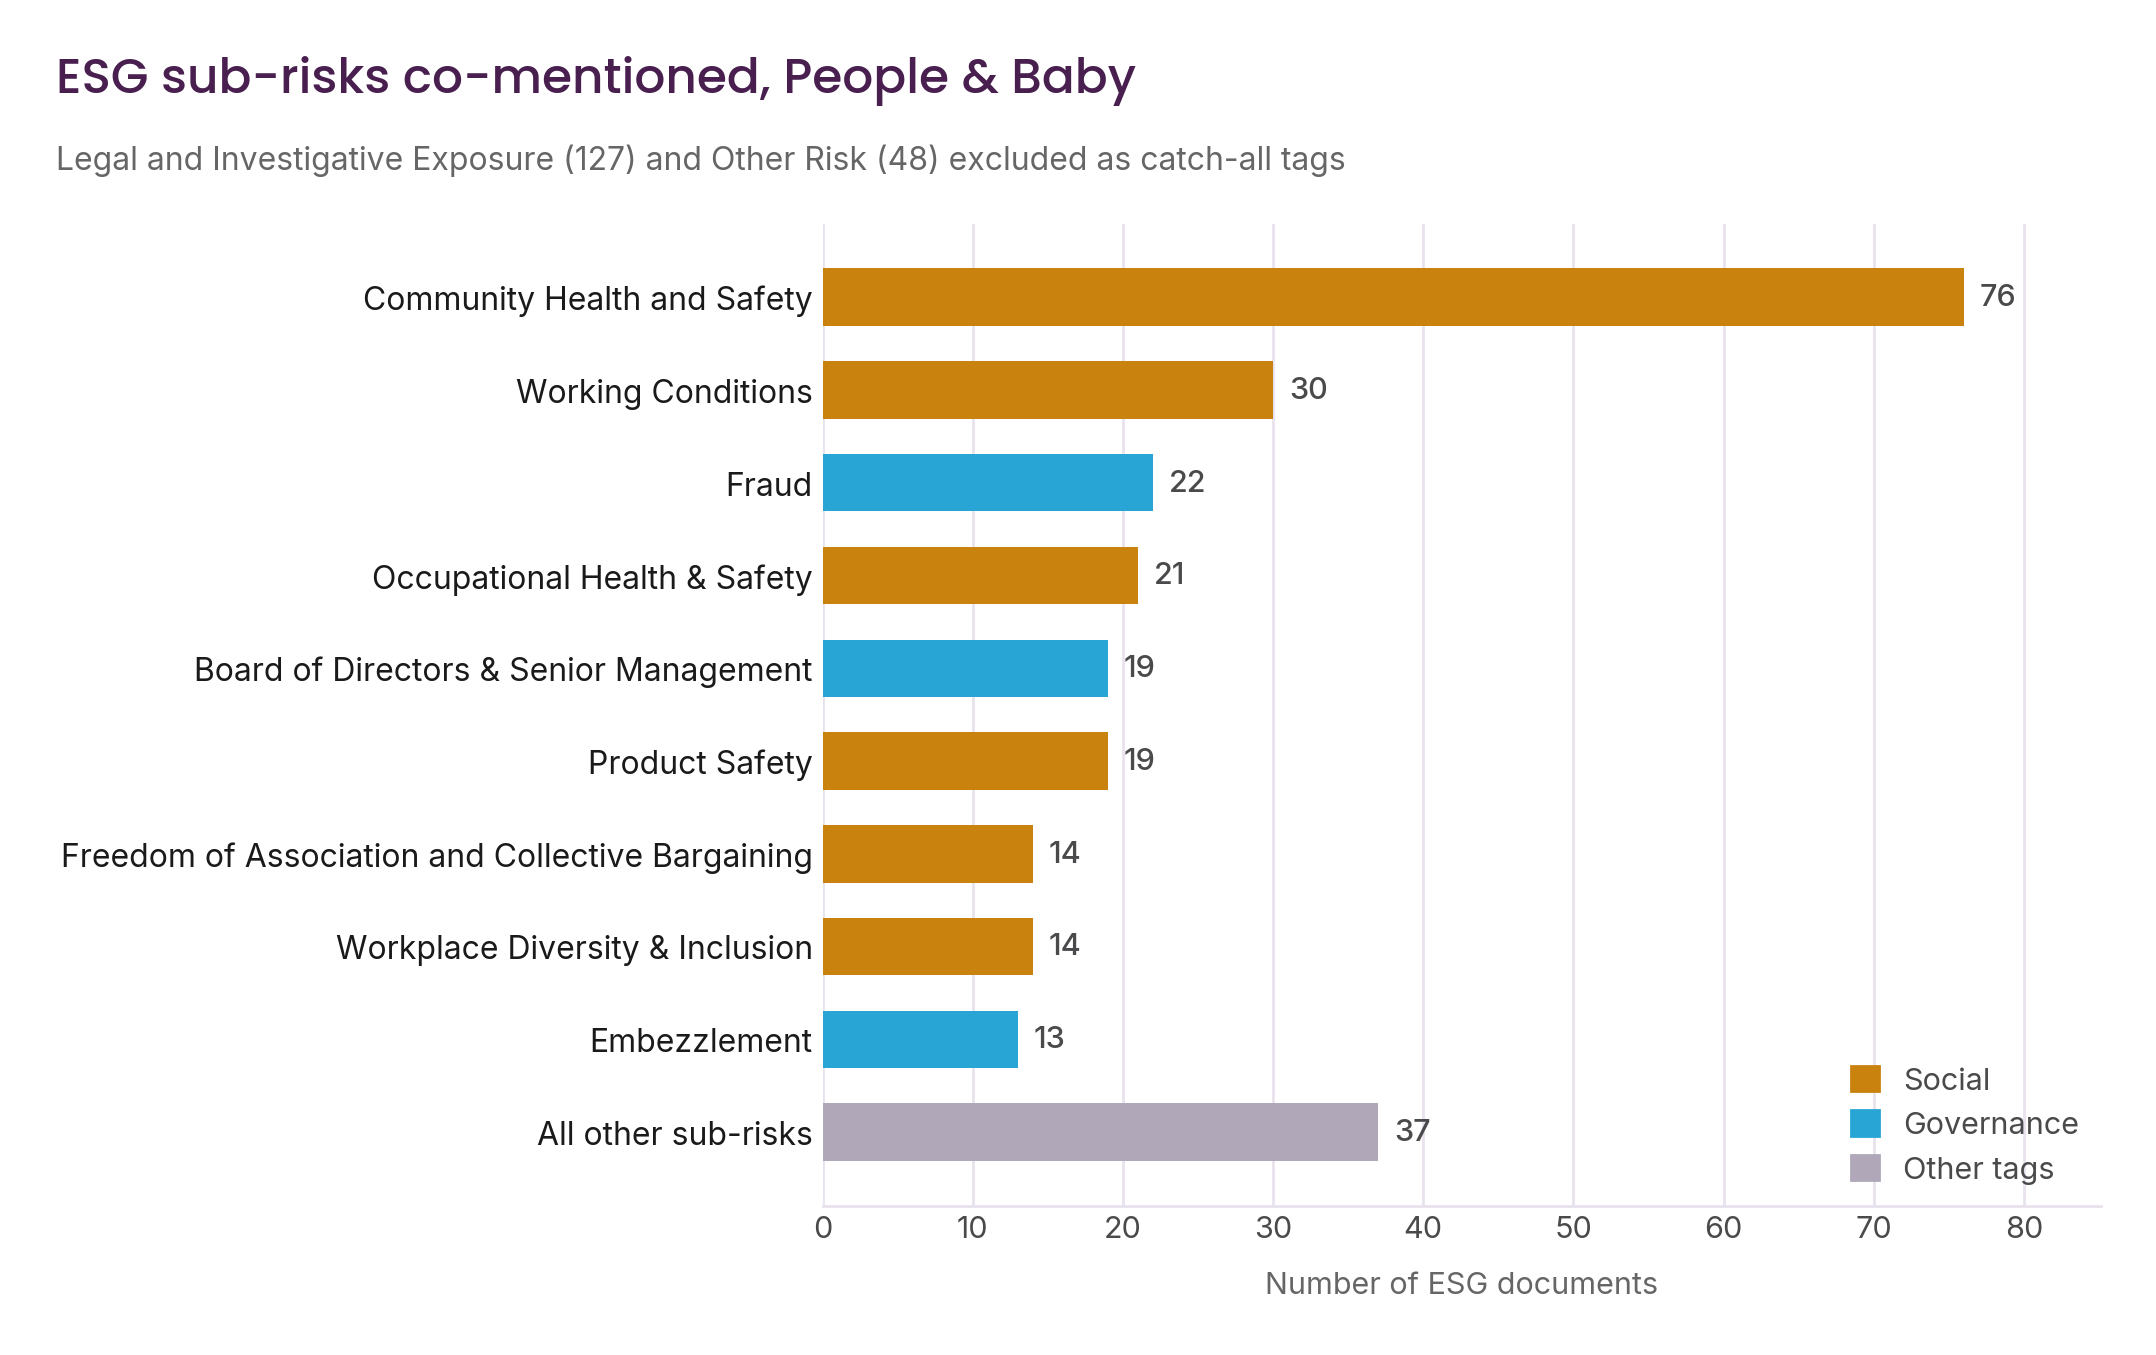
Figure 5 - Sub-risks co-mentioned across People & Baby coverage. Legal And Investigative Exposure (127) and Other Risk (48) are excluded as catch-all tags.

Four cases account for nearly all of People & Baby's exposure: the Castanet, Anticor, and public-funds case, the child-safety case covering the Lyon death and the Bordeaux closure, employee litigation culminating in a Court of Cassation ruling, and the Lille abuse convictions and their sentencing. Spread across 19 sub-risk categories, the same material looks far more diversified than it is. Tags such as Child Labor, Tax Strategy, and Right to Property register because a case touched them once in passing, not because the operator carries exposure there.

The 2026 residue is qualitatively different from a story burning out. What remains is structural rather than incidental: a redundancy plan that removed an entire CGT delegation, a whistleblower retrospective, and two Villejuif nurseries closed. The sector union has shifted its demand accordingly, moving from accountability for individual incidents to an administrative investigation and People & Baby's withdrawal from nursery management altogether. Read alongside the 2025 change of control and the 44 announced closures, the operative residual exposure is loss of public delegations and license to operate, not reputational drag.

Neither crisis is closed. The 2022 safety failures were never structurally resolved, and the 2024 governance case remains before the courts, though counter-signals exist: an ex-director was acquitted on appeal, and one municipality has maintained its contract. The variables to track are the outcome of the fraud investigation, contract renewals with municipalities, and any further union escalation.

The Takeaways:

Across seven years, for-profit childcare has moved from near-invisibility to sustained scrutiny in three markets at once. What surfaced as isolated incidents in individual centers has become a question about the operating model: state inspectors, parliamentary committees, investigative journalists, and prosecutors have converged on the same finding, that margin is held by cutting staffing in a service where staffing is the service. The consequences have stopped being reputational. Operators have lost licenses, entered court-supervised proceedings, changed hands, and closed centers, and in France, the demand has shifted from holding an operator accountable for a given incident to removing it from nursery management altogether. The coverage has thinned since its peak, but nothing in the data suggests the underlying question has been settled.

Access Capital Partners and SESAMm's logos separated by a vertical line

Access Capital Partners, gestionnaire indépendant d'actifs privés européens, et SESAMm, leader mondial des données de controverses ESG et réputationnelles, annoncent la mise en place d'une collaboration destinée à enrichir le suivi des risques environnementaux, sociaux, de gouvernance et de réputation au sein des portefeuilles d'Access Capital Partners.

Dans le cadre de cette collaboration, les équipes d'Access Capital Partners s'appuieront sur les solutions de SESAMm pour identifier en amont d'éventuels signaux de risque et suivre leur évolution dans la durée. L'objectif est de disposer d'une vision continue et documentée, complémentaire aux travaux d'analyse déjà menés en interne, et de nourrir le dialogue avec les partenaires et les sociétés en portefeuille.

« Le suivi des enjeux ESG et réputationnels demande aujourd'hui une information à la fois large, actualisée et traçable », déclare Gaëlle Achdjian, Principal Responsible Investment chez Access Capital Partners. « L'intégration de la solution SESAMm renforce notre capacité à identifier précocement des signaux de risque potentiels et à adopter une approche plus proactive dans leur suivi. Cette source d'information complémentaire et continue contribue à renforcer la robustesse de notre dispositif de gestion des risques, à enrichir nos échanges avec les gérants et sociétés de notre portefeuille et à soutenir notre démarche d'investissement responsable sur le long terme »

La mise en place s'est faite progressivement au cours des derniers mois, en lien étroit entre les équipes des deux sociétés.

À propos d'Access Capital Partners

Fondée en 1998, Access Capital Partners est une société de gestion indépendante européenne de premier plan, gérant 15,8 milliards d'euros et spécialisée dans deux stratégies complémentaires : le Buy-Out Small Cap et l'Infrastructure. Investisseur de conviction, la société développe des partenariats de long terme avec des gérants parmi les plus performants du marché, dont les stratégies sont alignées avec la vision d'Access : accompagner des entreprises et des actifs résilients dans la réalisation d'une croissance durable et créatrice de valeur. L'investissement responsable constitue un pilier central de son approche, avec l'intégration systématique des enjeux ESG dans les processus de sélection, de suivi et de gestion des investissements.
Pour plus d’informations sur Access Capital Partners : www.access-capital-partners.com

‍

À propos de SESAMm propos de SESAMm

SESAMm est un leader mondial de la donnée sur les controverses. Sa plateforme, fondée sur les grands modèles de langage et l'IA générative, identifie en quelques secondes les risques ESG, réputationnels et fournisseurs sur des millions d'entreprises et de projets d'infrastructure, y compris sur les marchés peu couverts. La société a levé 50 millions de dollars et opère sur quatre continents.

Pour plus d’informations sur SESAMm : www.sesamm.com

Environmental, social, and governance (ESG) data now serves very different jobs: portfolio screening for asset managers, supplier due diligence for corporates, ESG reporting for compliance teams. Most ESG data providers describe themselves in similar terms: broad coverage, real-time signals, regulatory alignment. The meaningful differences show up in daily use, when an analyst looks for a supplier controversy but can’t find it in the feed, or when a compliance team reconstructs the evidence behind a screening decision from eighteen months ago.

A demo shows you the ESG data software. It does not show you how the ESG data collection underneath actually works: where the data comes from, how often it refreshes, or which languages the models read. That is what the seven questions below cover. The first five establish what the data is, and the last two establish whether your teams can work with it. Run them in a live session, with the ESG data platform open and your own entities loaded.

First, define what you are buying

The ESG software market bundles several products under one label, and a scoping error here wastes the rest of the evaluation.

Carbon accounting platforms measure your own emissions. Carbon accounting tools calculate a carbon footprint across scopes and draw most of their input from systems you already run, such as purchasing and energy records. No ESG risk dataset replaces carbon accounting, and no carbon accounting platform substitutes for outside-in evidence.

ESG reporting software assembles disclosures, mapping them to GRI, SASB and the other reporting standards a filing requires. That work also starts from your own records rather than from evidence about anyone else.

ESG risk data points outward instead. It draws on sources outside the companies it covers rather than on what those companies choose to file, which is what makes it useful to risk management teams carrying exposure through holdings, suppliers and counterparties they do not control. Whether a vendor delivers it inside a broad ESG solution or as point solutions is a packaging question, not a substantive one.

ESG ratings agencies assess companies rather than supply raw evidence. A rating draws on outside-in sources and on what the company provides directly, including questionnaire responses and details that were never published, which is the depth an external feed cannot reach. The cost is breadth and frequency: rated universes are smaller, and scores are refreshed on a review cycle. Some ESG ratings agencies license third-party risk data to widen coverage and fill the gaps between reviews.

The seven questions in this buyer's guide concern the data underneath either kind of ESG solution, which is what separates an ESG data provider decision from a software decision.

1. How many companies are covered, public and private?

Coverage of listed companies is well served across the market. Roughly 50,000 companies trade on public exchanges worldwide, they publish disclosures, and every established ESG vendor ingests them. The differences start beyond that perimeter.

Private equity portfolio companies, tier-two and tier-three suppliers, and acquisition targets rarely publish sustainability reports, so an ESG rating built on corporate disclosure returns an empty record for them. That empty record then reads as low risk, even though it reflects limited visibility. Disclosure-dependent methods carry a second weakness even where filings exist, since the company is describing its own ESG performance and its own ESG initiatives, which is where greenwashing risk enters and where disclosure-derived ESG scores diverge most from observed behavior.

What matters is the private company count as a number, alongside an explanation of how it is produced. An ESG data provider that derives signals from external sources rather than self-reported filings can cover a private supplier in Vietnam on the same basis as a listed multinational. How that coverage is counted also matters, since operational risk often sits within a subsidiary or a plant trading under a different name.

2. How frequently is the data updated?

Coverage tells you whether an entity appears in the dataset. Update frequency tells you whether what it says is still true.

Controversies develop faster than reporting cycles. A labor investigation or a product recall can escalate within days, while an ESG rating, refreshed annually or even quarterly, describes the company as it stood some time ago. What settles it is the typical lag between a story's publishing and the signal reaching your feed. Measured in minutes and hours, the ESG risk data supports active monitoring. Measured in weeks, it supports periodic ESG reporting, a valid use case, and a narrower one.

Depth of history matters for the same reason in reverse. A decade or more of continuous archive lets you judge whether an incident is isolated or part of a pattern, and lets you backtest before committing budget.

3. Can you see the source behind every signal?

Current data counts for little if the ESG score behind it cannot be traced to a source. Transparent, source-backed evidence determines how far the data travels within your organization.

Follow an ESG score down to its evidence, and keep going until you reach documents: publication name, date, original language, and a working link. If the trail ends at a category label such as "governance concern, moderate," then the underlying governance data cannot be verified, and it will be hard to place the signal in an investment committee paper or a regulatory filing. Investment decisions presented to a client or a regulator need verified sources, not the ESG score alone.

That same trail settles internal disagreement, since a challenged ESG score can be resolved on the document level rather than through proprietary weighting.

Grouping matters just as much. When 40 outlets cover a single strike at a factory, a well-built system presents a single case supported by 40 documents, not 40 separate alerts. Without that consolidation, alert fatigue follows.

4. Which languages does the data cover?

Following a signal to its source assumes the relevant document is in the dataset to begin with, and that depends on the language.

Incidents surface first in local reporting. A pollution complaint against a plant in Guangdong appears in the Chinese regional press long before the environmental impact reaches an English-language wire. A land rights dispute in Brazil appears in Portuguese, often through an NGO bulletin. On the flip side, if coverage is limited to English, it's more likely to arrive late.

There are two important things to look at: the full language list and whether the models analyze source text natively or rely on machine translation, which tends to lose entity names, local aliases, and the sentiment carried by idioms. Language depth carries particular weight for any ESG due diligence provider, since supplier and third-party risk is documented almost entirely in non-English sources.

5. Analyst-based, AI-based, or hybrid methodology?

AI now sits somewhere in almost every provider's pipeline. The question is not whether AI is involved, but where the balance sits between machine and human.

At the analyst-heavy end, people make most of the judgment calls, and AI mainly narrows what they read, which buys depth and a consistent house view at the cost of reduced coverage and a slower refresh. At the AI-heavy end, models carry the work end-to-end, delivering the scalability manual review cannot reach, though at the risk of poor data quality and too much noise. Most ESG vendors describe their approach as hybrid, somewhere in the middle, so the useful follow-up is what each side actually does. Defining the risk taxonomy, validating model output against labeled samples, and adjudicating edge cases are substantive human roles, worth distinguishing from review of finished output. The other number to get on the record is the false positive rate, and how it is measured, since that is where the balance shows up in practice.

6. How does the data fit into your existing workflow?

The first five questions establish what an ESG data provider is worth. The last two decide whether you get that value back.

ESG data management succeeds or fails on the match between the delivery route and the people using it. Many teams work entirely in a dashboard, where single sign-on matters more than any integration, since access runs through credentials the organization already manages. Quantitative and credit risk teams feeding internal models want an API or scheduled files. Others rarely open the platform and work from alerts instead. A growing number of users query the data through an AI assistant connected over MCP, which allows them to create a custom report without ever using an ESG reporting software. None of these routes is necessarily better than the others; it just depends on what you need.

Entity resolution comes next, since the provider has to map its coverage onto the identifiers you already use, whether ISIN, LEI, or internal supplier codes. Manual mapping becomes a recurring cost and a recurring source of error.

Data integration is where costs are concentrated, so be sure to test integration capabilities in concrete terms rather than on a checklist. Total cost of ownership is driven less by license price than by the engineering time each route consumes, and usability belongs on the same axis, since a dashboard your team avoids has the same practical value as a feed nobody wired up. Data security review is worth starting early, because procurement and InfoSec sign-off often run longer than the technical work.

Alerting logic is the piece that teams most often underestimate, whichever route they take. Thresholds should be configurable by severity, risk category, and entity group, so an asset manager covering 300 holdings or a compliance officer covering 400 suppliers sees only the cases that matter this week. Without that control, an ESG data platform gets filtered out rather than used.

7. Is the methodology audit-ready for regulators (SFDR, CSDDD)?

Workflow fit decides whether the data gets used week to week. Documentation decides whether it can be cited.

SFDR principal adverse impact reporting, CSDDD risk prioritization, Corporate Sustainability Reporting Directive (CSRD) disclosure and EU taxonomy alignment all want evidence behind an ESG metric rather than an ESG score copied into a template. TCFD-aligned climate risk reporting works the same way. Omnibus I, adopted in February 2026 with CSDDD transposition due by July 2028, narrowed who falls in scope of both CSDDD and CSRD without softening those regulatory requirements. At procurement, this comes down to one property: the provider's documentation has to be usable by someone other than the provider.

Three points establish whether it is. Is the ESG data provider's methodology written in a form your auditor can read? Is it versioned, so the provider can say which version produced a given signal and when the logic changed? Methodologies shift with regulatory changes, and regulatory changes have arrived steadily since Omnibus I, so a provider that cannot date its own revisions cannot help you date yours. Can the provider reproduce point-in-time data rather than overwriting history with the current view?

Reproducibility is where providers separate most sharply, and it is the easiest to test. Name a company in your book and a date twelve months back, then see whether the provider can produce the record as it stood on that date. A methodology that only ever shows the current view leaves no audit trail behind its own signals, and regulatory compliance rests on the trail as much as on the score.

Running the evaluation

Environmental, social, and governance data is bought once and lived with for years, so the evaluation is worth running properly. Score every ESG data provider against the same seven questions, using your own entity list rather than a curated demo universe, then weight the criteria by use case. Portfolio monitoring and sustainable investment screening prioritize update frequency and alerting. Pre-deal due diligence prioritizes private company coverage and traceability. ESG reporting prioritizes documentation and audit trails.

One pattern runs through all seven. Coverage, freshness, traceability, and language depth are properties of the data itself, shaped by architecture decisions made years earlier. They sit deeper than the ESG data software and the ESG data management tooling layered on top, which is why they deserve more weight in a scorecard than roadmap commitments do. An ESG strategy is only as strong as the evidence under it, and so is every ESG score built on it.

SESAMm was built against these constraints. TextReveal® analyzes over 30 billion articles from 4 million public and premium sources in over 100 languages, covering 5 million public and private companies, with 10 million new documents added daily and an archive reaching back to 2008. Every signal resolves to its original document, which is what lets asset managers, banks, and corporates see the ESG risks and opportunities across a portfolio or supply chain rather than only those a company chooses to disclose.

SpaceX under scrutiny
Analysis

SpaceX under scrutiny: What the Public Record Shows

September 16, 2026
•
5 mins read

SpaceX has spent the past three years in the news for reasons that have little to do with rockets. The company has been in court with a neighboring company in Texas, is at odds with the FAA, and has been quietly dropped by more than one European pension fund. In June 2026, shortly before its record 75 billion dollar public listing, MSCI gave the company its lowest corporate responsibility rating, a CCC.

We took a look at SESAMm’s data on SpaceX’s and pulled its record to see what three years of coverage actually holds. Between September 2023 and September 2026, we detected 139 distinct controversy cases involving the company, assembled from news reporting and other public sources. Four of them sit in the most severe tier, and between them they carry most of the story.

SpaceX and FAA in Regulatory Turmoil

‍

UNGC: Watchlist Severity 5 · Very High
Category Environmental Governance Social

17 events  |  February 2023 to June 2026

The first case in the record is a disagreement with the regulator. Conflict between SpaceX and the Federal Aviation Administration (FAA) intensified over time, with multiple proposed fines and significant penalties for data submission failures and safety oversight. Elon Musk publicly criticized the agency's management and called for reforms. What the case also notes is that none of this severed the relationship: through the same years, SpaceX continued to unveil ambitious plans for Mars and to collaborate with the FAA.

SpaceX's Environmental Challenges and Legal Battles

‍

UNGC: Watchlist Severity 5 · Very High
Category Environmental Governance Social

123 events  |  August 2019 to August 2026

SpaceX faces increasing scrutiny over its expansion and launch activities, with numerous environmental lawsuits and regulatory challenges emerging. The concerns range from habitat destruction and pollution to safety violations, and have prompted protests and legal action from environmental groups and local communities. As the company pushes forward with its plans, the balance between innovation and environmental responsibility remains contentious.

SpaceX Faces Scrutiny Over Workplace Safety Violations

‍

Severity 5 · Very High
Category Environmental Governance Social

13 events  |  November 2023 to June 2026

SpaceX is under scrutiny following a series of workplace safety incidents, including a death and multiple injuries at its facilities. OSHA has imposed significant fines and opened investigations, citing trends in injury rates and unreported incidents, raising questions about the company's safety practices.

SpaceX's Starship Program: A Journey of Triumphs and Setbacks

‍

Severity 5 · Very High
Category Environmental Governance Social

59 events  |  May 2020 to July 2026

The FAA has navigated a complex relationship with the Starship program, closing multiple investigations while mandating corrective actions after a series of explosive test failures. Set against those failures are significant milestones, including successful test flights and the development of new prototypes. Regulatory scrutiny and environmental concerns have continued through both.

What Investors are doing about it

Beyond these four, the record runs heavily to labor and employment litigation, as well as to Starlink's military use and security exposure.

Investors have already acted on it. Danish fund Akademiker Pension blacklisted SpaceX in March 2025. In August 2026 the Swedish state pension fund AP7, which manages savings for roughly six million people, ruled out investing at all, citing corporate governance and human rights risk management. Both decided on evidence that had been public for years. After the listing, the stock fell 27 percent.

Takeaways 

The record does not point to one isolated controversy, or even to one particular part of the business. It points to a pattern. SpaceX’s exposure sits at the intersection of the risks that come with operating at extraordinary speed and scale: safety, environmental impact, labor practices, regulatory compliance and the governance of increasingly consequential technology.

That pattern matters more than any single headline. These cases are different in substance, but they share a common feature: the underlying disputes have persisted.

The exposure is not just something of the pastl. SESAMm’s Controversy Exposure Score* for SpaceXis currently 82 (considered “Very High Risk”) f, in its “Very High Risk” band, compared with an average of 67 (HIgh Risk) over the preceding year.

This ongoing exposure shows that controversy has become a recurring feature of SpaceX’s expansion story. For investors, regulators and other stakeholders, the question is increasingly whether the company’s governance and risk controls can scale as quickly as its rockets, satellites and ambitions.

‍

*The Controversy Exposure Score (CES) is a continuous score from 0 to 100 measuring a company's exposure to ESG controversies over time, based on the severity of incidents and their media volume.

This is an unsolicited rating: it is not commissioned by the rated company. The company is notified before its score is first issued, does not take part in the rating, and SESAMm has no access to its management or non-public documents. Ratings are produced only from public and licensed sources. Methodology: https://www.sesamm.com/methodology 

‍

Product Updates

Introducing SESAMm’s Company Controversy Summary Report

September 1, 2026
•
5 mins read

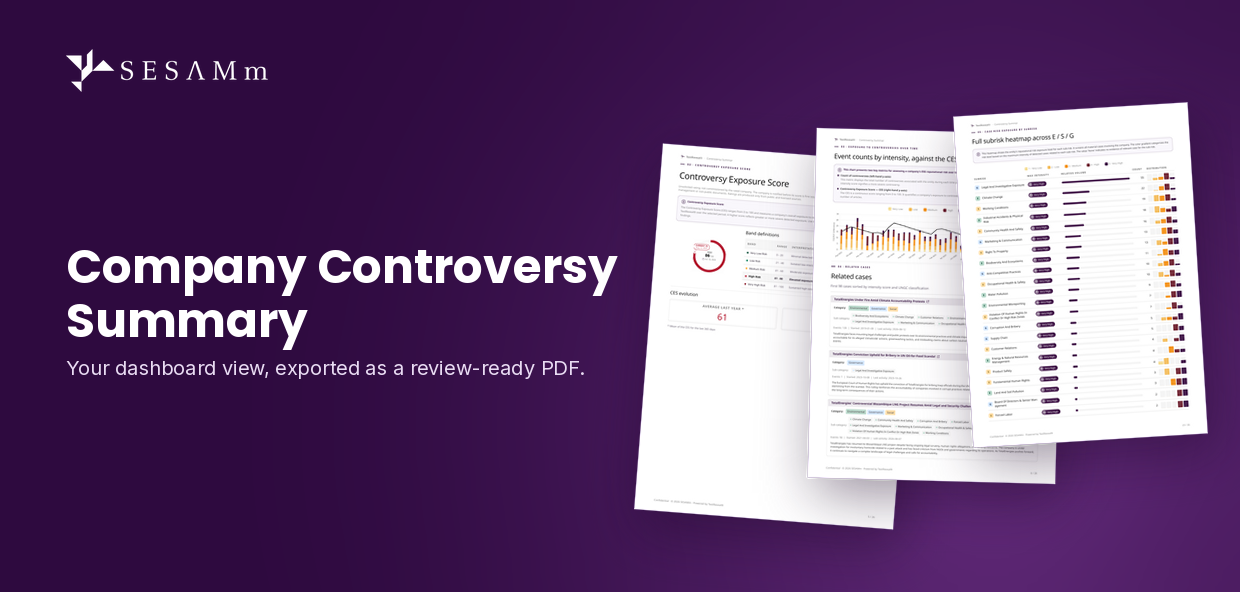
We are happy to announce the Company Controversy Summary, a new entity-level export that turns a TextReveal® dashboard view into a presentation-ready PDF in a single click, without screenshots or manual reformatting.

The report is built for the internal reviews you already run, from quarterly risk committee packs to compliance files and deal team memos. Each section explains what the scores mean and how the analysis was conducted, so the export can be filed or presented as it comes.

From Dashboard to Document in One Click

The report covers six sections: an executive summary, the Controversy Exposure Score (CES), how that score has evolved over time, monthly exposure charts by intensity, a case list with UNGC classification, and a methodology appendix. Because every case traces back to the underlying SESAMm sources, a reviewer can verify any finding without coming back to you.

Monitoring has been real-time for several years, while reporting has not, which leaves analysts screening a company in minutes and then rebuilding the same findings by hand for whoever signs off, a step this export removes.

Scoped to the Review at Hand

Setting the time range and the filters before exporting means the report reflects the review it was produced for, whether that is a deal period, a compliance window, or a monitoring cycle. Those filters are then printed on every page, so anyone reading the document later can see what was screened.

A deal team working on a target, for example, sets the diligence window, applies sector-relevant filters, and exports a report covering only that period.

Key Benefits of the Company Controversy Summary

  • A file, not a screen: The report leaves the dashboard as a document you can attach or present, generated from the view you are already working in.
  • Six sections in one document: Everything a reviewer needs, in the order they read it, with nothing summarized away.
  • Scope a reader can see: The window and the filters behind the report travel with it, so no one has to ask what the analysis included.

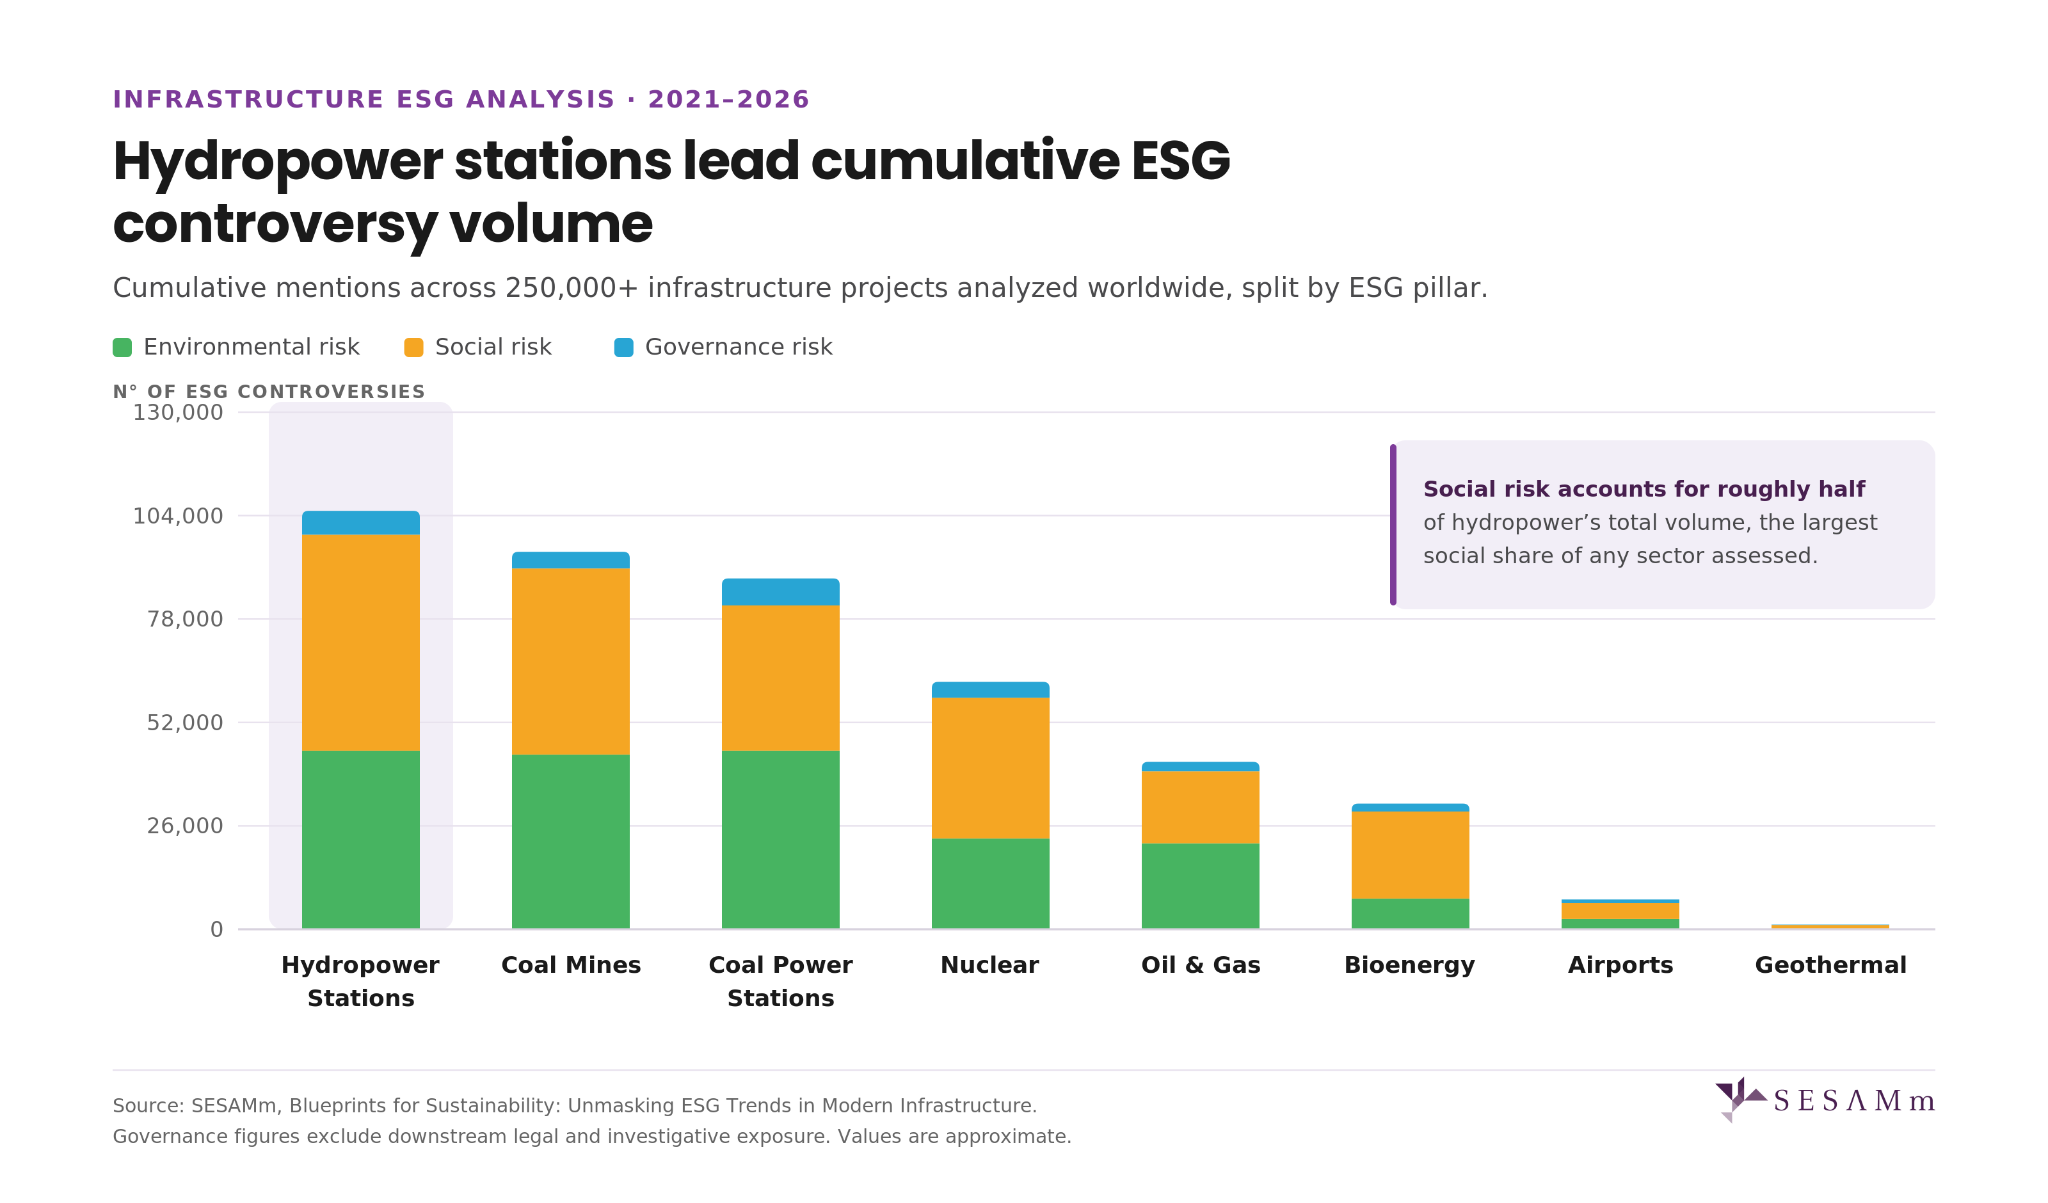
An analysis of over 250,000 infrastructure projects reveals that the sector most often filed under "clean energy" carries the heaviest environmental and social controversy footprint of any asset type assessed.

In the taxonomy of energy infrastructure, hydropower occupies a comfortable position. It is renewable, dispatchable, and long-lived, and it enters transition frameworks, green bond eligibility criteria, and net-zero roadmaps with minimal friction. Where coal is a legacy liability to be managed down and nuclear invites a specialized debate, hydropower is largely treated as settled. What these projects have actually done does not support that treatment.

Belo Monte, an 11,233 MW complex on the Xingu River in Pará, Brazil, is the sharpest test of the point, because it was built to answer this exact objection. Approved after decades of opposition to a far larger design, it was engineered as a run-of-river plant to minimize flooding, and its reservoirs cover 478 km², of which 274 km² was already river channel at high water, a 61% reduction compared with the 1980s proposal, according to the operator's own regulatory filing. The mitigation was designed from the start, and everything that follows happened regardless.

Biodiversity: the cost of a physical footprint

Environmental controversy across infrastructure concentrates on industrial accidents, water pollution, and biodiversity, and hydropower leads the third, outright, because dams require the permanent conversion of river systems and the land around them. Mexico's Federal Electricity Commission won environmental approval in September 2014 for the Las Cruces dam on the San Pedro Mezquital, upstream of Marismas Nacionales, a Ramsar-protected wetland, even though the project's own impact statement conceded that the damage to Indigenous ceremonial sites could not be mitigated. Along the Mekong River, river health and fish populations fell as dam construction spread through the basin. In Brazil, the Doce River carried a mass release of toxic material after an upstream failure. Elsewhere, the record includes violations of the Endangered Species Act and documented disruption to rainfall patterns.

At Belo Monte, the consequences have been measured rather than projected. The plant diverts water into a canal that bypasses a 130-kilometer stretch of the Xingu known as the Volta Grande, which has received less than 30% of its natural annual discharge since 2019, and some 86% of the stretch's seasonally flooded vegetation, 30,748 of 35,600 hectares, can no longer be inundated at all. The gap lies in the regulator's own file: IBAMA's technical staff called for 10,900 cubic meters per second in February, the historic peak month, compared with the 1,600 that the operating regime actually releases. Seven years of underwater video survey data published in Scientific Reports recorded total fish species richness falling from 62 to a post-operation average of 51, with the steepest losses near the dam and in the rocky rapids, which hold roughly 2.6 times as many species as sandy reaches. The zebra pleco, whose entire known range lies inside the dewatered stretch, now sits on Brazil's national list of threatened species as critically endangered.

None of this is an accident or a failure of operation. It is a structural consequence of the asset. A well-run dam still floods a valley, and a dam engineered specifically not to flood one still dewater the river below it.

When engineering fails: hydropower's physical risk profile

Coal mining leads infrastructure on industrial accidents, where the record is dominated by human tragedy and safety negligence: explosions, collapses, fires, and repeated, incremental failures. Hydropower ranks second, but its accidents take a different form, because in this sector, industrial failure means catastrophic engineering failure at scale. The record includes pipe ruptures causing severe land erosion, oil leaks, and dam collapses that killed and displaced people across whole regions, while PG&E's settlement over damages to the Middle Fork American River Hydroelectric Project and the litigation still running in Brazil after dam collapses give a sense of the exposure a single event can generate. For anyone underwriting these assets, the distinction is financial as much as physical: a coal mine's safety record is a rising cost curve, while a dam's structural integrity is a low-probability, near-unbounded loss.

At Belo Monte, that exposure has so far been financial. The project was budgeted at R$28.9 billion when Brazil's development bank approved a then-record R$22.5 billion loan in November 2012, and by late 2017, actual investment had reached R$38.6 billion, roughly 34% over. The operator owed R$28.3 billion to lenders and debenture holders at the end of 2024. Aliança Norte Energia Participações, the Vale and Cemig vehicle holding a stake in the project, discloses a possible loss of R$3.05 billion from a single construction-delay claim and describes the operator's liquidity as its principal point of attention and a source of investor alert. Neoenergia wrote off its own 10% holding by R$482 million in the fourth quarter of 2021.

The physical risk has been closer than the absence of a collapse suggests. In October 2019, the operator wrote to the national water regulator declaring an emergency, because reservoir levels had fallen far enough to expose an unprotected section of the Pimental dam's earthfill base to wind-driven wave erosion and, in the company's own words, structural damage. It cut outflow below the level agreed with the environmental regulator to protect the structure, and the letter surfaced only through investigative reporting.

Beyond the environment: displacement, water, and chronic corruption

Right to property

Hydropower ranks first among infrastructure sectors for property disputes, a direct function of the footprint a dam and reservoir require. The record shows land seizures, forced displacement, compensation that arrives short or not at all, communities never consulted before ground was broken, and blasting that cracked the foundations of nearby homes. Those affected are frequently the least equipped to hold an operator to account.

Fifteen years after Belo Monte broke ground there is still no audited count of who lost their homes. Estimates run from 20,000 to 40,000 depending on the definition used, against the operator's account of rehousing some 6,000 urban families. Landowners say expropriations are priced at unadjusted 2013 values while the project's own construction boom inflated the market, and as of 2025 none of the land required for the riverine resettlement program had been bought. A petition filed with the Inter-American Commission in 2011 still has no ruling.

Community health and safety

Hydropower sits alongside coal and nuclear as a leading source of community health disputes, but it arrives by a different route. Coal delivers PM2.5, nuclear delivers radioactive anxiety, and hydropower delivers water mismanagement: overconsumption that strips farmers of a livelihood, contaminated water reaching local crops. The grievance is agricultural rather than industrial, which widens the affected population considerably.

On the Volta Grande, catch per fisher fell from 11.1 kilograms a day between 2001 and 2008 to 4.53 kilograms between 2020 and 2023. A randomized household survey found 38.5% of residents in Belo Monte's resettlement neighborhoods living with moderate or severe food insecurity, against 28.3% across the surrounding city. In June 2026, federal prosecutors sought as interim relief for 635 families along the reduced-flow stretch the emergency delivery of three and a half to five liters of drinking water per person per day.

Corruption and bribery

Corruption and bribery accounts for close to 30% of governance controversy across infrastructure. What separates hydropower is the pattern. In airports, nuclear, and coal, corruption surfaces as discrete scandals: a probe opens, executives are charged, attention fades. In hydropower it keeps returning, tied repeatedly to falsified records and payments to local officials to secure land and water rights. Isolated scandals point to isolated actors. A pattern that recurs points to how these projects get permitted.

Brazilian prosecutors alleged that Belo Monte's construction contracts carried bribes worth 1% of their value, and three contractors admitted cartel conduct and kickbacks under leniency agreements that carried immunity. Everything after that was procedural closure rather than a finding of liability: the principal defendants were acquitted and the acquittal upheld on appeal in 2024, the competition authority archived its bid-rigging case in 2025, and no individual has been convicted in connection with the project. An investor screening for enforcement outcomes would have found a closed file. The costs landed elsewhere, in permitting delay, financing conditions, and a minority stake that has been for sale since 2022 without a buyer.

Hydropower's risk concentration: what this means

Hydropower's classification as clean energy is accurate on the metric it was designed to measure, because generation is low-carbon. But carbon intensity is one dimension of sustainability, and it is not the dimension that produces operational friction, legal exposure, or the loss of a social license.

What drew sustained opposition to these projects was water rights, displaced communities, cracked foundations, converted wetlands, and permits secured through local payments. None of it appears in a carbon accounting framework.

For investors, insurers, and lenders seeking transition-aligned infrastructure exposure, that is a material blind spot: an asset class that screens well on the primary criterion while carrying the heaviest social burden in the dataset, and carrying it on behalf of people who have no employment relationship with it. Belo Monte was engineered to avoid precisely that outcome and produced it regardless, which suggests the exposure is not a function of how a dam is built but of what a dam is.

The label is not wrong. It is simply measuring something other than risk.

‍

Stay ahead with the latest in ESG and AI intelligence

Join our mailing list to receive new reports, event invites, and updates from SESAMm directly to your inbox.