SEC Withdraws Defense of Climate Disclosure Rules: Impact on ESG Investing
May 9, 2025
•
5 mins read
The Securities and Exchange Commission (SEC) has voted to cease defending its climate disclosure regulations in court, marking a significant shift in U.S. corporate sustainability reporting requirements. This decision, announced on March 27, 2025, under Acting Chairman Mark Uyeda's leadership, has substantial implications for the ESG landscape.
The Decision
The SEC’s withdrawal from defending its climate disclosure rules comes amidst ongoing litigation before the U.S. Court of Appeals for the Eighth Circuit. Originally adopted in 2024, the rules were intended to provide investors with standardized information about companies' climate-related risks, emissions, and the financial impact of those risks. Uyeda justified the withdrawal by stating, “The goal of today’s Commission action is to cease the Commission’s involvement in the defense of the costly and unnecessarily intrusive climate change disclosure rules.” The regulations faced swift opposition from industry trade groups and Republican state attorneys general, who argued the SEC had overstepped its authority. The legal challenge quickly gained momentum, and with the change in SEC leadership, the agency opted not to continue defending the rules. Caroline Crenshaw, the lone Democratic commissioner, sharply criticized the move. She described it as an attempt to “unlawfully undo valid regulations” and accused her colleagues of “watching the rule’s demise while eating popcorn on the sidelines.”
Market Implications
The decision reintroduces regulatory uncertainty for companies. Many had already begun preparing internal systems and compliance structures based on the 2024 rules. Now, in the absence of a federal standard, they may be forced to rely on voluntary reporting frameworks or navigate a fragmented set of expectations from investors, states, and international markets. This lack of uniformity is likely to lead to inconsistent reporting practices and difficulties in cross-company comparisons. Investors, meanwhile, will face greater challenges in accessing reliable and comparable data on climate-related risks. Without SEC-mandated disclosures, much of the burden of transparency shifts to individual companies and third-party ESG data providers. Investors will likely need to increase due diligence efforts, adopt varied methodologies, and potentially absorb higher costs to obtain the data needed to manage climate risk effectively.
The Broader Context
This decision does not exist in isolation—it aligns with a broader trend of regulatory rollback on climate issues in the U.S. and signals a widening divergence between American and international disclosure approaches.
The divergence creates complexity for multinational corporations that must now navigate different expectations in different jurisdictions. This fragmentation may also create competitive disadvantages for U.S.-listed firms, especially those competing for capital in more disclosure-forward markets.
SEC Leaves the ISSB
In a related move that further isolates the U.S. from international sustainability efforts, the SEC recently withdrew from two key ISSB governance groups: the IFRS Sustainability Jurisdictional Working Group and the Sustainability Standards Advisory Forum. These groups are central to building alignment on global ESG disclosure standards.
The SEC’s exit from these forums signals a significant retreat from coordinated climate disclosure initiatives and weakens the U.S. role in shaping global ESG norms.
Market Response
Despite the rollback, some companies may continue voluntary climate-related disclosures. Those that have already invested in reporting infrastructure may opt to maintain transparency to meet investor expectations, mitigate reputational risk, and support long-term sustainability goals.
Simultaneously, ESG data providers and rating agencies are expected to play a more prominent role in filling the information gap. Financial institutions may also develop their own internal frameworks to evaluate climate risks, further privatizing what was once a public regulatory function.
Looking Forward
The path ahead remains uncertain. State-level legislation may introduce a patchwork of new rules. Global investors—particularly those with mandates in the EU or UK—may continue demanding robust disclosures from U.S. firms. And future federal administrations could choose to reintroduce or reshape mandatory disclosure regimes. In the interim, companies and investors will need to adapt by maintaining flexible reporting systems, monitoring evolving voluntary frameworks, and diversifying their sources of ESG data. While federal requirements may have receded, the underlying investor interest in climate-related financial risk is not going away. Climate disclosure, in one form or another, remains firmly on the radar.
SESAMm’s AI Technology Reveals ESG Insights
Discover unparalleled insights into ESG controversies, risks, and opportunities across industries. Learn more about how SESAMm can help you analyze millions of private and public companies using AI-powered text analysis tools.
The direct-to-consumer (DTC) genetic testing industry has transformed personal health and ancestry exploration, offering consumers remarkable insights from their DNA. Yet rising ESG concerns around data privacy, ethical use, and regulatory compliance are reshaping this landscape, pushing companies to prioritize consumer trust. Once a leader, 23andMe now faces steep challenges with data security, public confidence, and corporate stability. Recent breaches, including a leak impacting 6.9 million users, have led to lawsuits, a $30 million settlement, and boardroom upheaval, casting uncertainty on the company's future. Meanwhile, competitors like Ancestry and MyHeritage, though contending with similar issues, have remained comparatively stable. How does 23andMe compare to its competitors when it comes to ESG concerns? Read on to find out.
23andMe: From Market Leader to Data Breach Fallout
23andMe initially led the DTC genetic testing market but has faced a series of challenges, mainly around data privacy. A major data breach in 2023 compromised 6.9 million users’ information, resulting in a $30 million settlement and reputational damage. Board resignations followed, highlighting corporate governance issues. These events underscore the need for strong data security and governance in sustaining consumer trust.
Ancestry: Customer Loyalty Tested by Rising Controversies
Ancestry has also faced privacy-related challenges, especially since its acquisition by Blackstone. Lawsuits claim the company misused consumer data without consent, violating privacy laws. Public backlash, such as from a controversial advertisement, has further affected Ancestry’s image. Yet, its solid user base has helped it remain stable compared to some competitors.
MyHeritage: Navigating Privacy Compliance Across Borders
MyHeritage, while facing fewer controversies than its peers, still encounters significant privacy scrutiny. Investigations in Norway and Denmark have raised questions about its compliance with data laws. Although MyHeritage’s controversies are less severe, maintaining regulatory compliance remains essential for its international operations.
The future of the DTC genetic testing industry depends on how effectively companies manage ESG risks. Companies like 23andMe, Ancestry, and MyHeritage can better protect consumer trust and build a foundation for sustainable growth in this scrutinized sector by prioritizing data security, strong governance, and compliance.
Reach out to SESAMm
TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.
Join SESAMm for breakfast in Midtown during Climate Week NYC on September 23rd from 8:30 am - 10:30 am. We'll give a short, informal walkthrough of what's new on the platform and what's coming next, then open it up for coffee and conversation with the SESAMm team and other users in ESG, risk, and compliance.
This is a small gathering for SESAMm clients and prospects. Space is limited - looking forward to seeing you there!
SESAMm's ESG data shows FIFA's Controversy Exposure Score has stayed High to Very High since 2020. See why continuous monitoring beats the four-year cycle.
With the 2026 World Cup now underway, FIFA is back in the global spotlight, and its risk profile is once again being narrated in four-year cycles, as though controversy arrives with the tournament and recedes with the closing ceremony. The data points to a different pattern. Across the period from January 2020 to June 2026, the large majority of FIFA's most serious controversies were recorded outside any World Cup window. Tournaments concentrate global attention on FIFA's existing liabilities, but the evidence suggests they do not drive the underlying volume. Many of the substantive events, including court verdicts, regulator rulings, fund decisions, and bid matters, occur in the periods between tournaments.
For investors, sponsors, and anyone screening exposure to football's governing body, this distinction matters. If controversy were cyclical, it could be assessed around the calendar. Because the data indicates it is closer to continuous, it is better suited to ongoing monitoring. To examine this, the analysis below draws on SESAMm's controversy data, which captures and classifies FIFA's reputational, regulatory, and operational controversies.
Context: How FIFA's Structure Shapes Its Risk
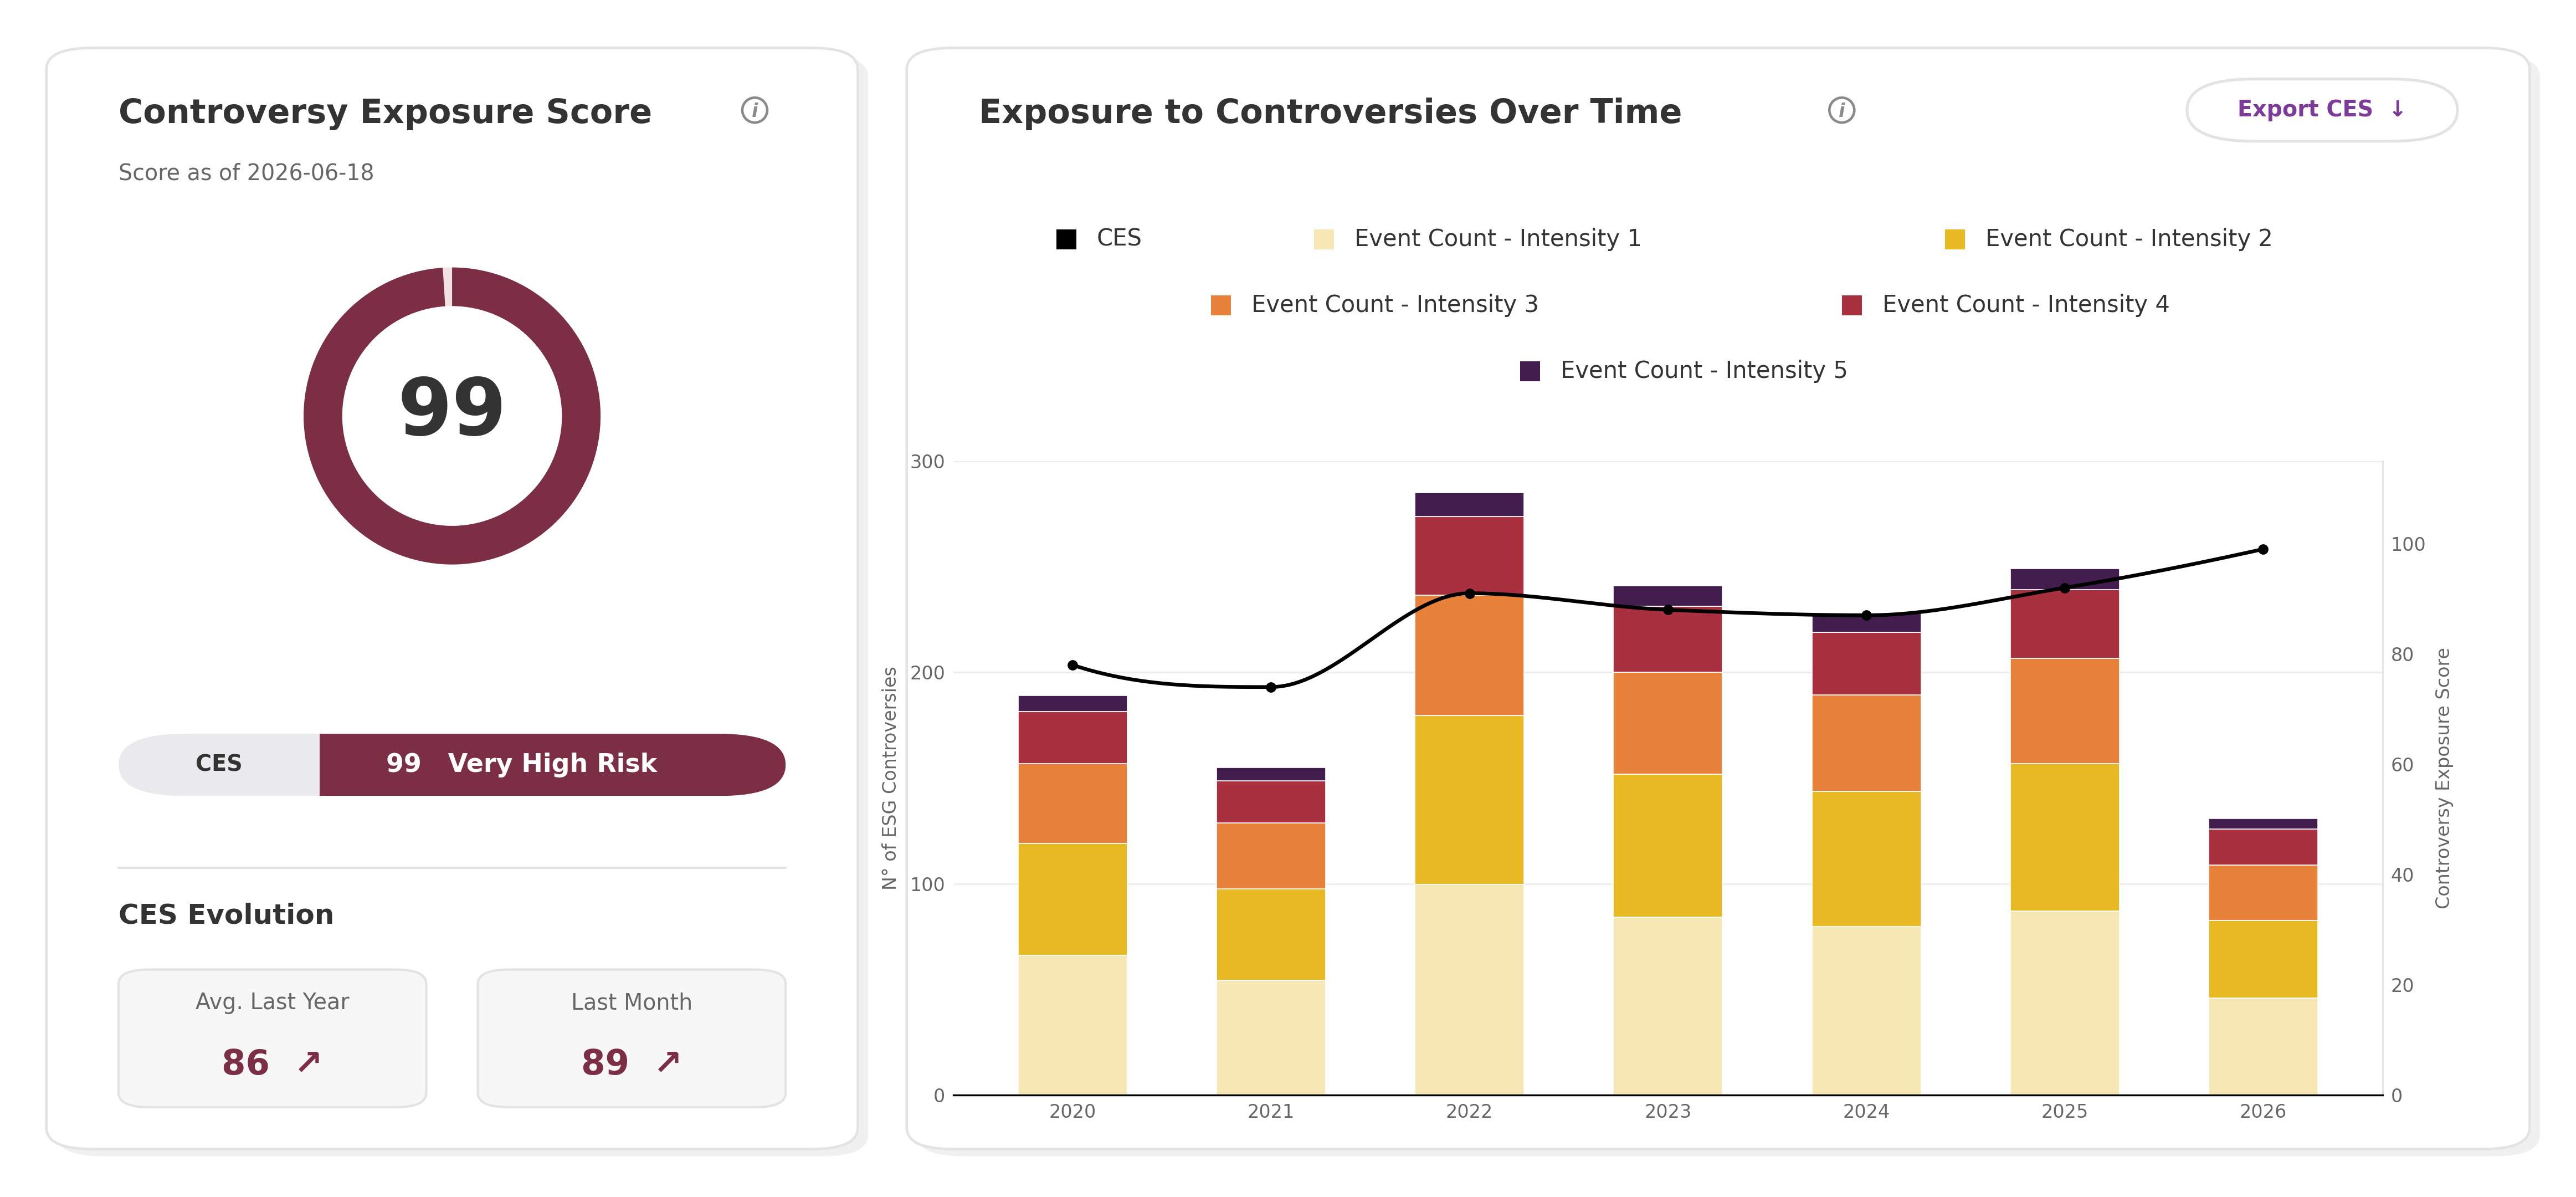
Controversy Exposure Over Time
*Unsolicited ratings - produced from public sources, not commissioned by the rated company. For more information, visit here.
It helps to start with how FIFA is organized, because its governance structure has a direct bearing on the type of risk it carries. As a Swiss-law association, FIFA answers to a membership rather than to shareholders or a securities regulator, and its decision-making body, the FIFA Council, is composed of representatives from the regional confederations whose commercial interests the Council also oversees. This means the regulatory functions of sanctioning, eligibility, and integrity sit close to the commercial function of awarding and selling tournaments. Arrangements of this kind tend to produce a steady stream of governance-related questions as part of normal operations, which is consistent with SESAMm’s controversy data.
One useful illustration is procedural rather than criminal. The Blatter and Platini proceedings span the entire time period without reaching a clear resolution, running from a 2020 complaint through a fraud indictment, an acquittal, a prosecutorial appeal, and a second acquittal, before Platini opened a fresh action against FIFA and Infantino in June 2026. As a corruption narrative, the sequence is inconclusive. As a governance observation, it illustrates a broader dynamic in which matters are litigated and re-litigated over long periods, in part because resolution often depends on external courts operating on their own timelines. The result is a long-running procedural footprint rather than discrete, time-bound events.
The CES is an aggregate, entity-level score (0–100) that measures an entity's overall exposure to ESG controversies over time. It's built from individual ESG events and their intensities, synthesizing both event volume and severity into a single trackable figure. The intensity score, by contrast, operates one level down: it's applied at the event level, measuring how severe or important each individual ESG event is on a scale from 1 (least severe) to 5 (most severe). In short, the CES tells you how exposed an entity is overall, while the intensity score tells you how serious each underlying event is.
ESG Risk Over Time
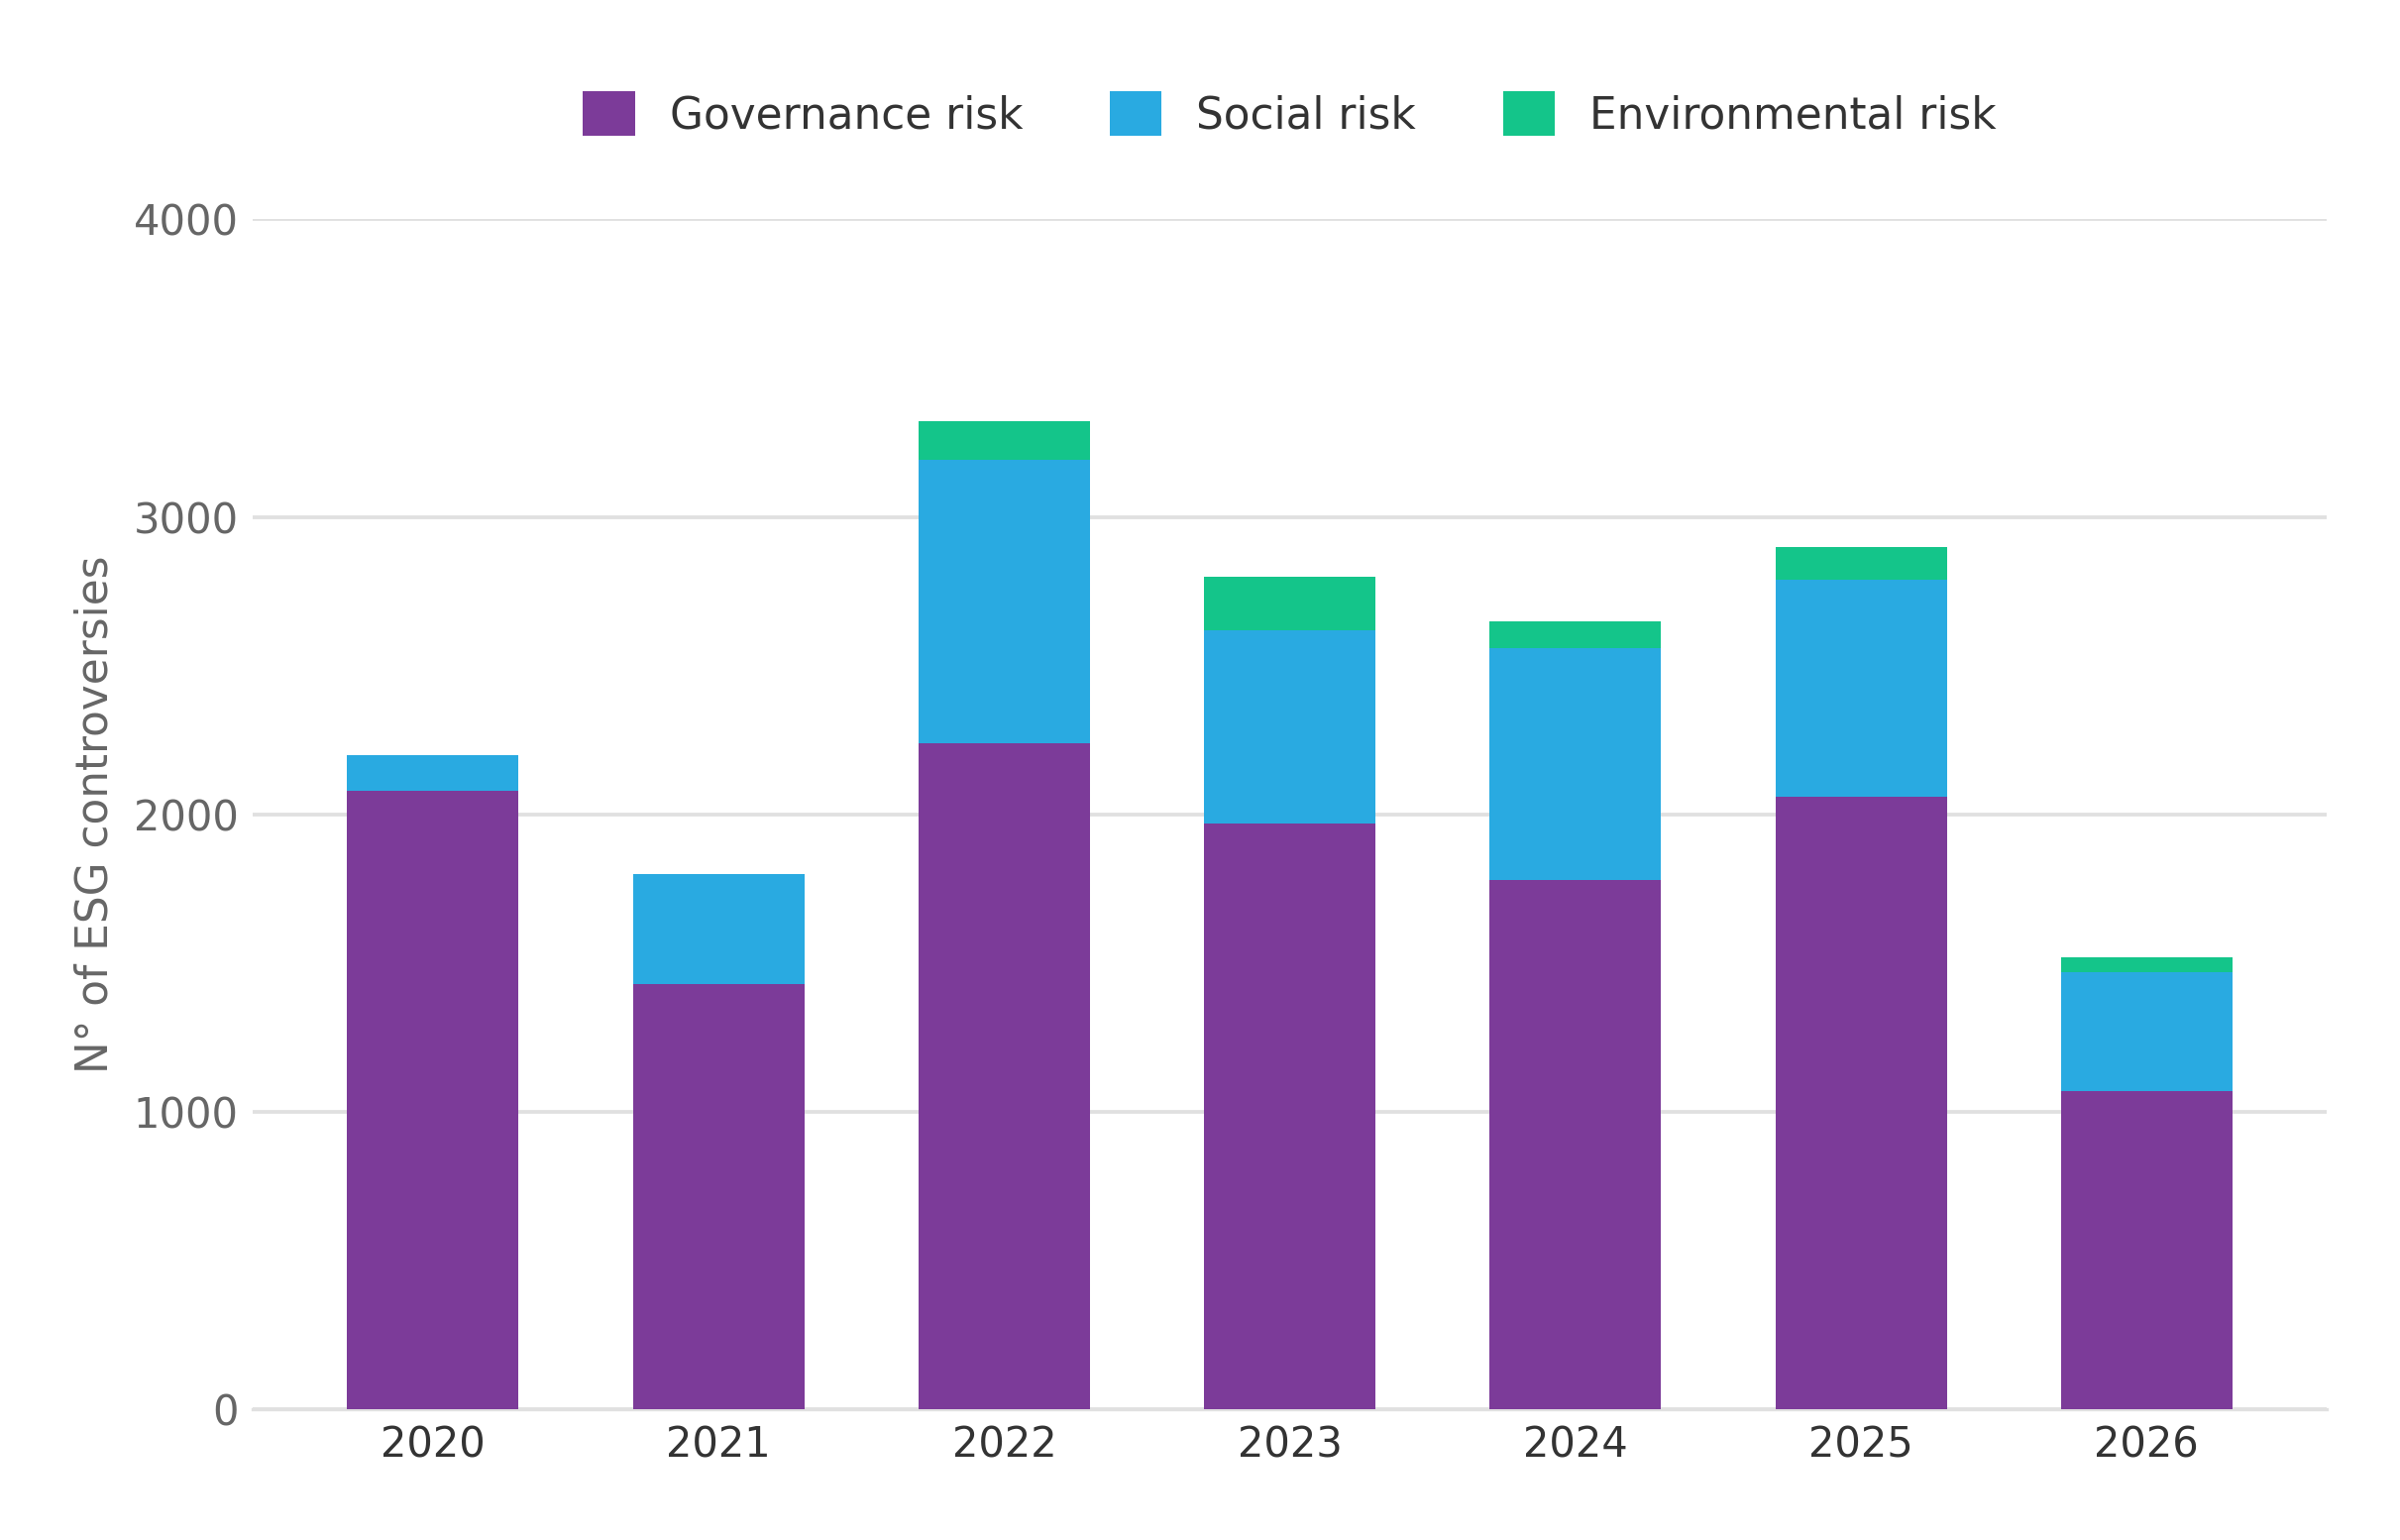
This chart tracks FIFA's ESG controversies per year from 2020 to 2026, stacked by risk pillar. Governance dominates every bar, with social forming a secondary band and environmental barely visible. Volume climbs from a governance-heavy opening year to a clear peak in 2022, then holds at a stable plateau through 2025 before the short 2026 bar. The shape is driven by a handful of major events. The 2020 corruption investigations kept the opening-year baseline elevated and were almost purely governance-related, following a US DOJ indictment unsealed that April, which alleged bribes were paid for the votes that awarded Russia and Qatar the 2018 and 2022 World Cups.
The 2022 Qatar World Cup marked the clear inflection point, drawing sportswashing accusations and pushing total controversies to their peak, while migrant-worker conditions and human-rights coverage around Qatar thickened the social band into a permanent quarter-to-third of each bar from 2022 onward. Rather than reverting, controversies settled into a post-2022 "new normal," plateauing well above the pre-tournament level.
Underneath it all, corruption-and-bribery and legal/investigative exposure account for the bulk of total risk across 2020 to 2026, while environmental risk stays statistically negligible throughout.
ESG Risk by Type
Environmental Risks
Environmental risk accounts for a small share of FIFA's total controversy volume, but that low frequency masks cases of genuine severity. The Swiss Fairness Commission ruled against FIFA's Qatar 2022 carbon-neutrality marketing, turning a greenwashing accusation into a formal regulatory matter still active in June 2026. Related controversies extend the theme, including criticism of the Saudi Aramco and Coca-Cola sponsorships, the cooling and water-use controversies at Qatar, and the animal-welfare outcry over stray-dog culling ahead of Morocco's 2030 hosting.
Beyond these, FIFA has drawn criticism over its marketing and communications, notably branding the 2022 Qatar World Cup as "carbon neutral," and has dealt with fraud and embezzlement, exemplified by the case of former FIFA and CONCACAF official Chuck Blazer. Issues tied to its board and senior management leadership round out the picture, though the overall pattern is one of an organization reacting to the weight of its legal and ethical past rather than getting ahead of it.
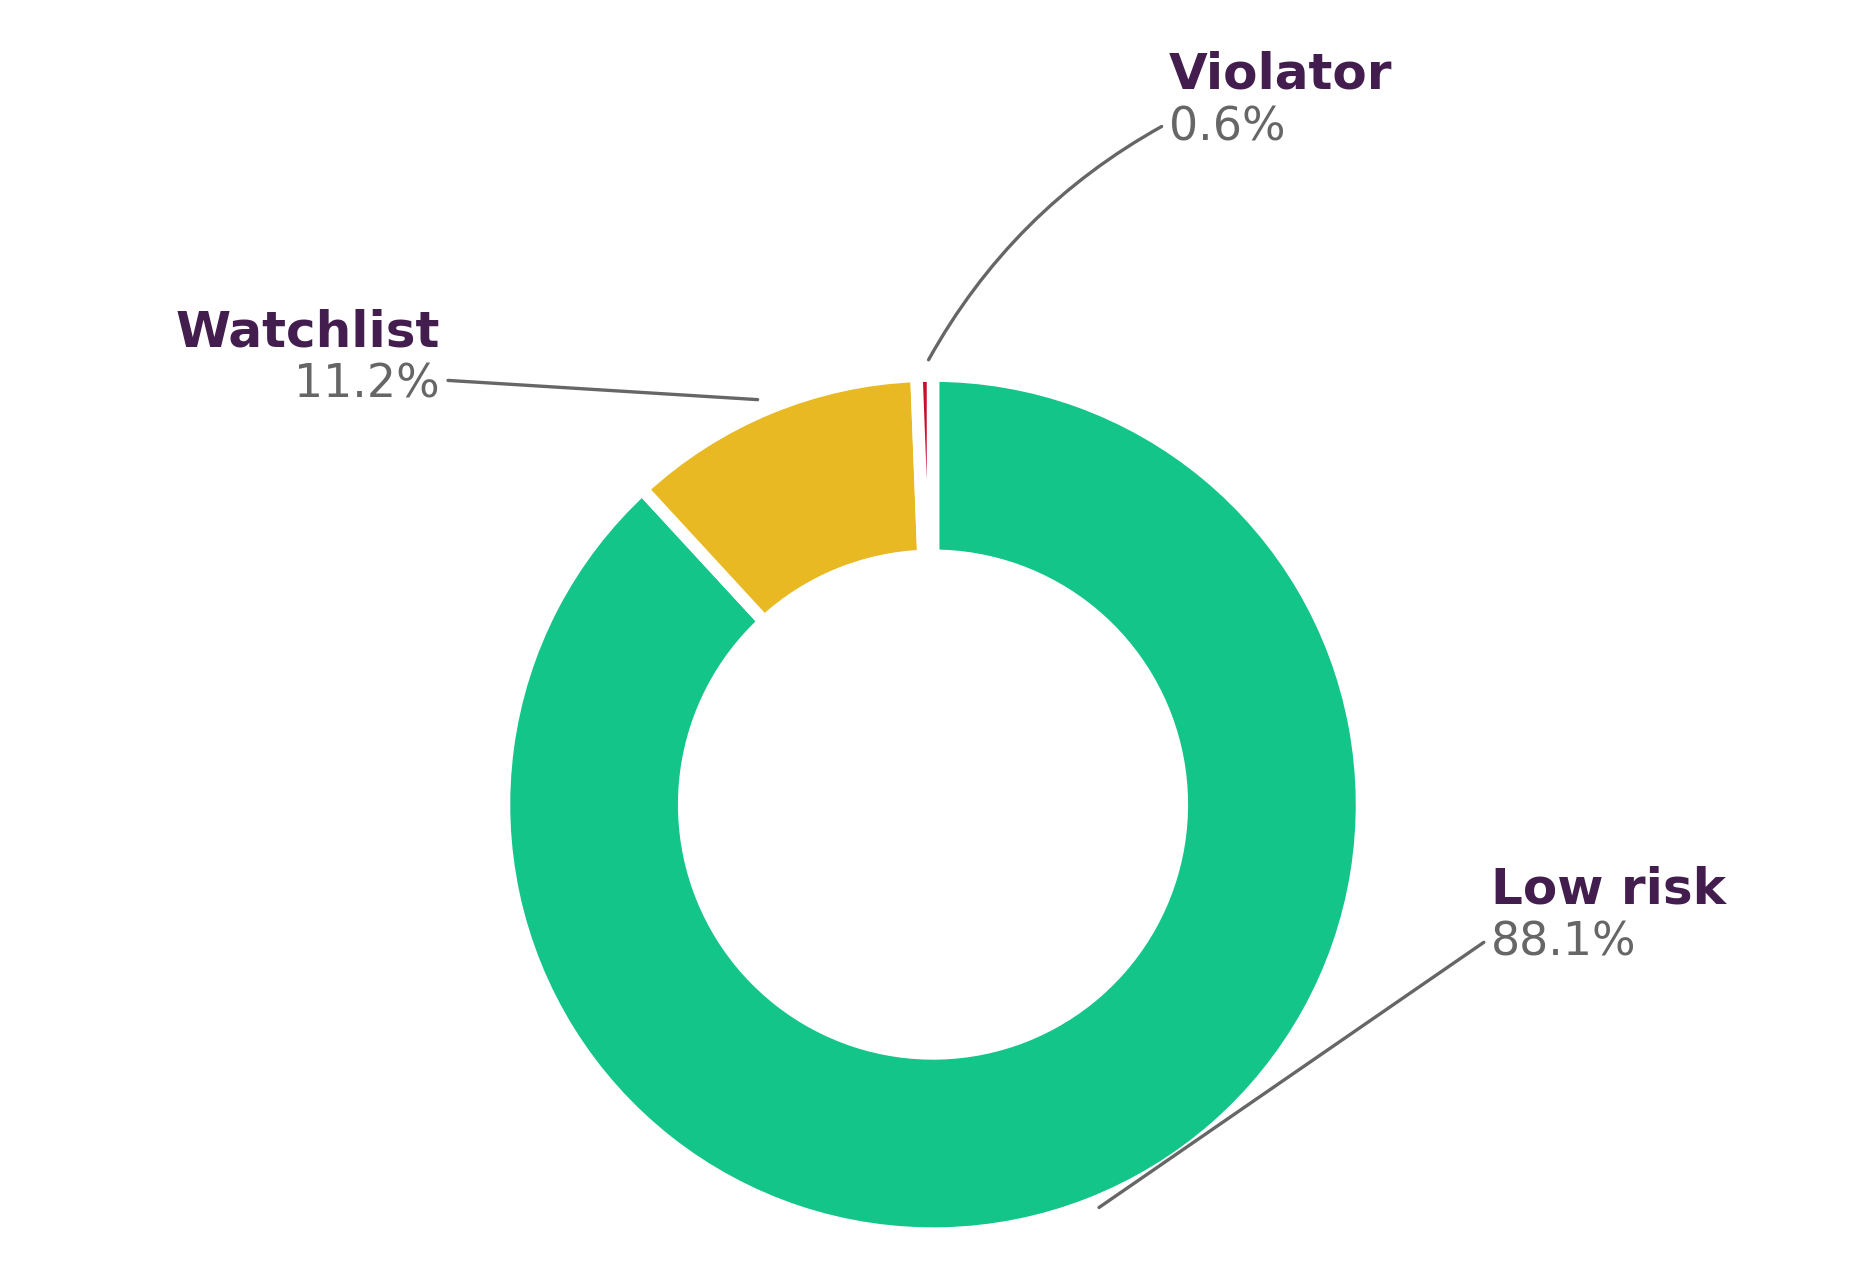
As the breakdown above shows, the overwhelming majority of FIFA's screened ESG events fall into the low-risk tier (1,294, or 88.1%), with 165 (11.2%) on the watchlist and 9 (0.6%) classified as Violator, the highest-risk tier under SESAMm's UN Global Compact screening. That tier is assigned only where there is clear evidence of a breach, such as formal sanctions, court findings, or regulatory condemnations, rather than unresolved allegations. For investors with SFDR Article 8 or 9 obligations, or internal exclusion policies tied to UNGC compliance, a Violator flag on a core holding or counterparty is a material signal rather than a monitoring note, which is why the profile is best read as governance-led: the nine Violator events reflect adjudicated breaches concentrated in FIFA's governance history, not the live controversies surrounding the current tournament.
The composition that emerges is a governance core of long-running legal cases, a Qatar-rooted social overlay that has proven durable, and a small but genuinely high-severity environmental tail now being contested through formal channels.
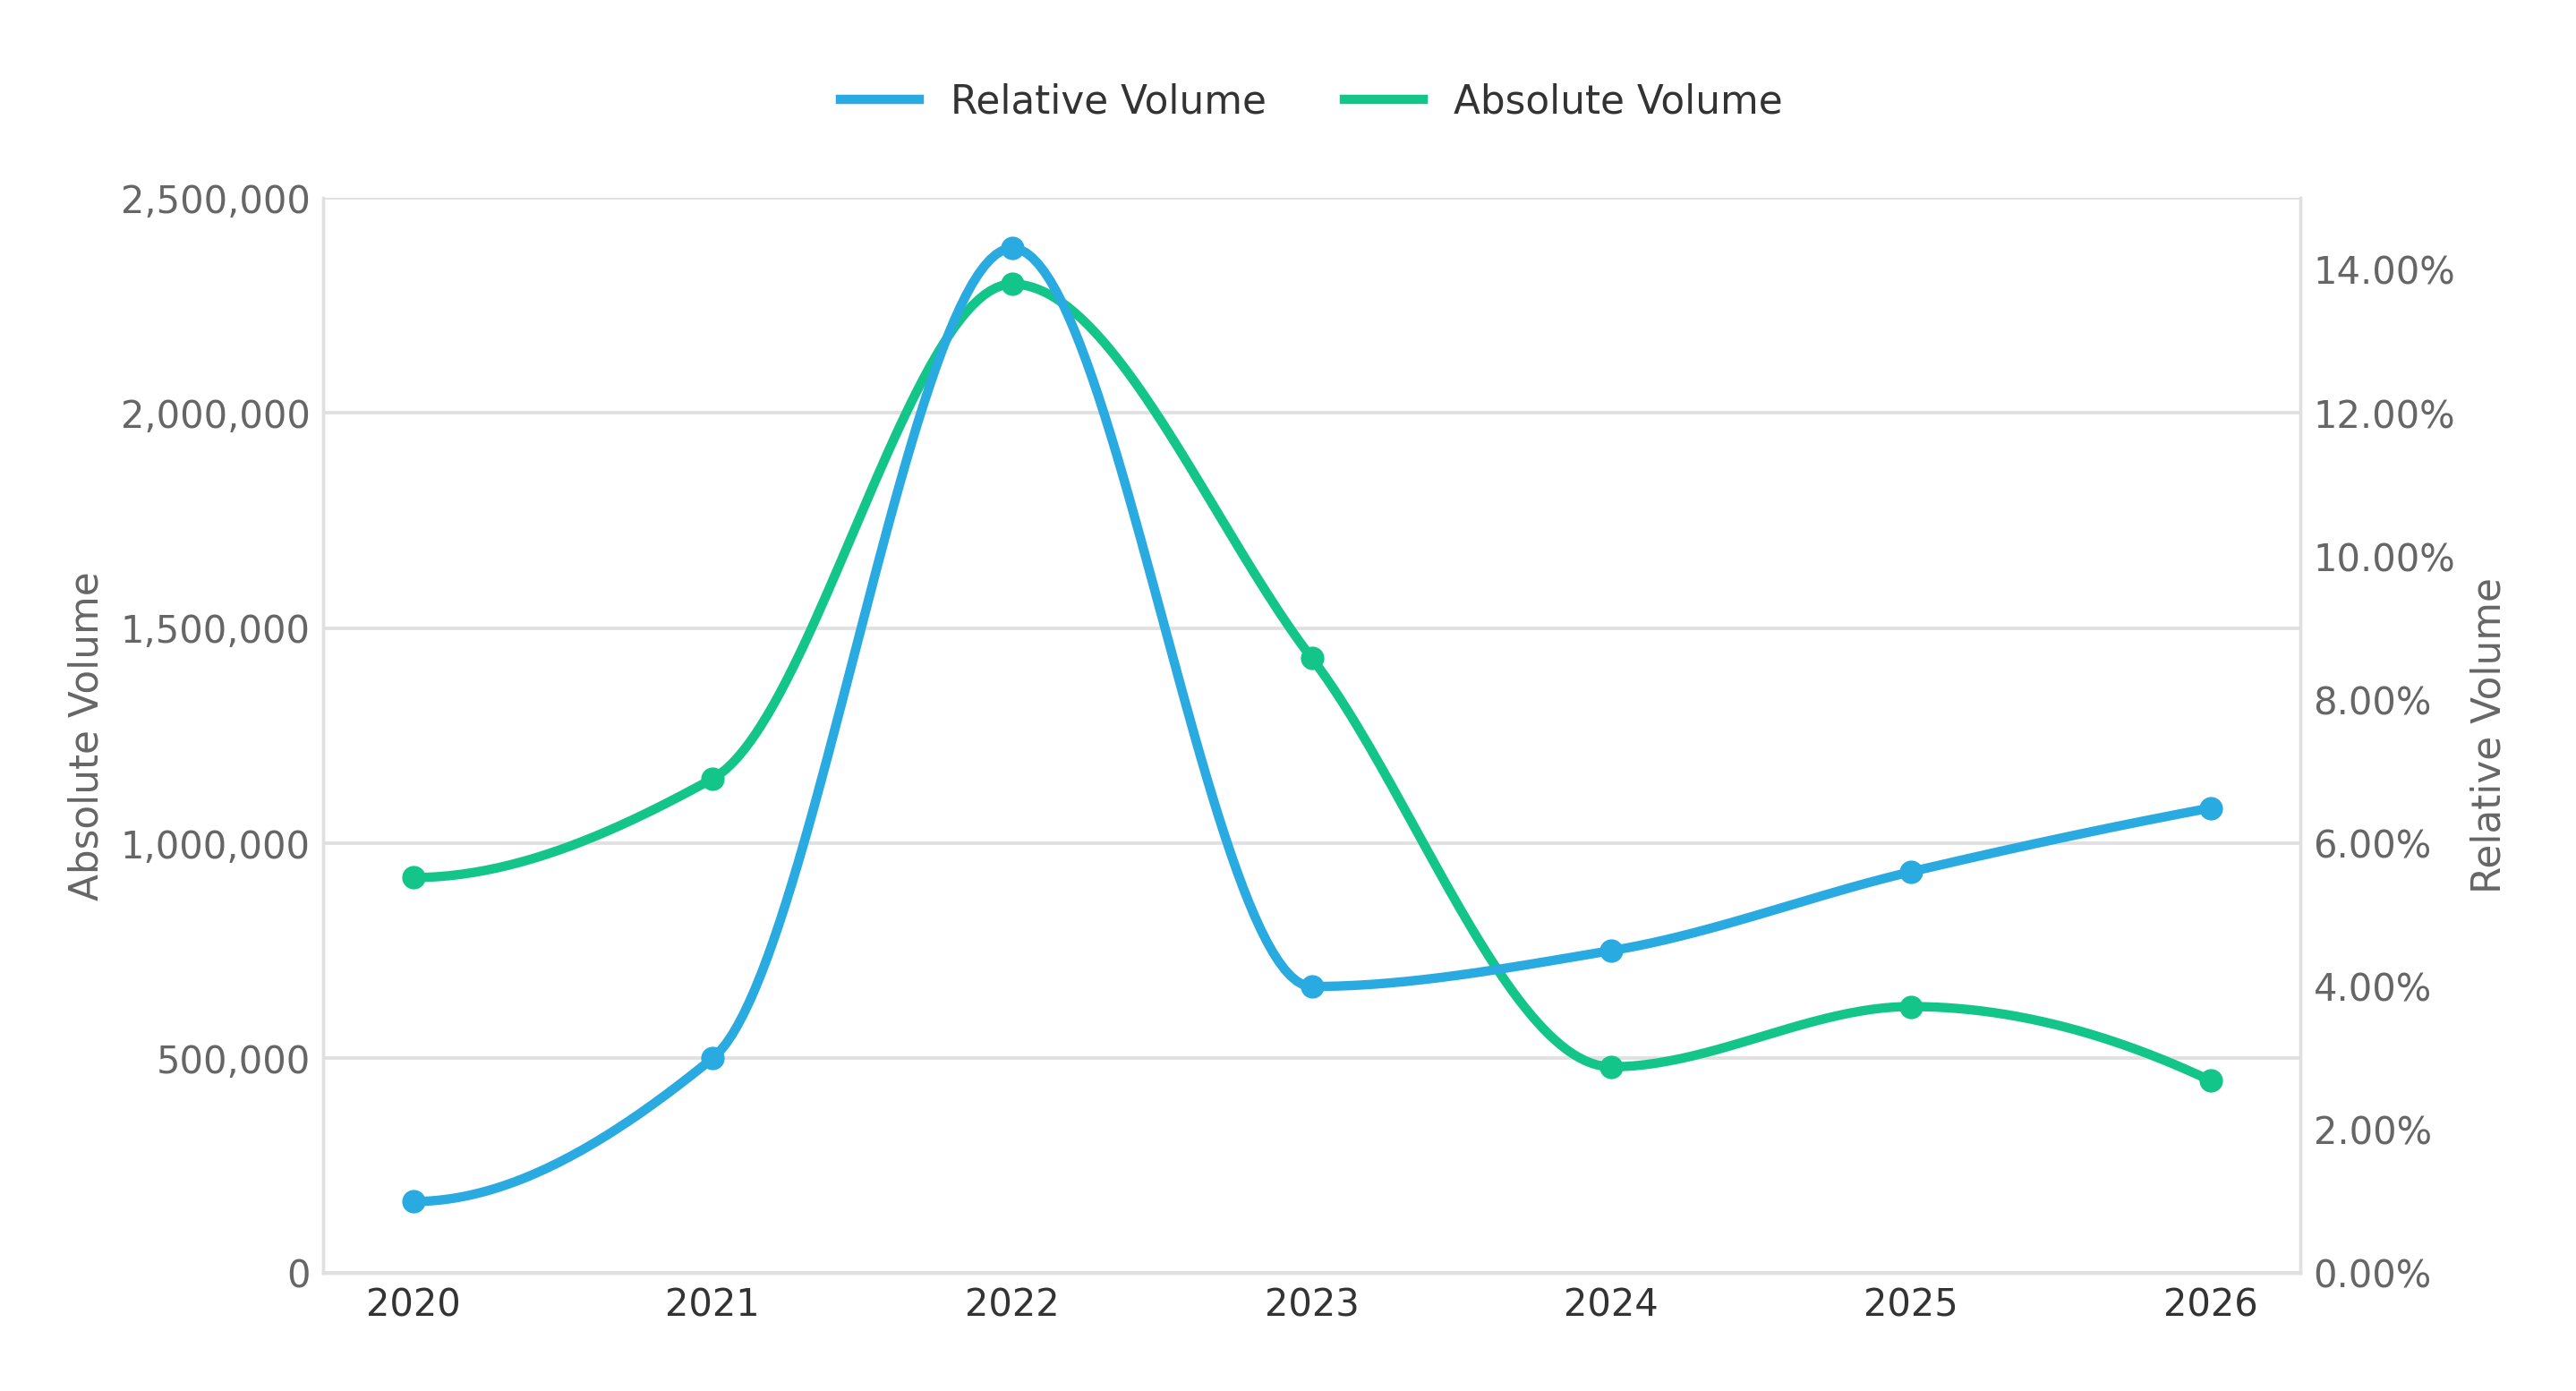
Both lines explode together, but unevenly: absolute volume roughly doubles while the relative share more than quadruples, briefly making Qatar roughly one in seven of all FIFA-related items, because nearly every controversy fires at once. The spike packs in wider labor abuses, and the jailing of whistleblower Abdullah Ibhais; the OneLove armband ban and Qatar's criminalization of same-sex relations and the broader sportswashing and carbon-neutral greenwashing charges; and the unresolved bribery allegations over the 2010 hosting vote. On its own, this acute cluster would suggest a controversy that lives and dies with the tournament.
Phase 3: Off-Season Accumulation (2023–2026)
This is where the two lines part ways, and the accumulation shows itself. After the tournament, the relative share deflates sharply in 2023, the acute spike clearing, but it never returns to baseline; instead, it grinds steadily upward every subsequent year, ending in 2026 at roughly four-and-a-half times its pre-tournament level. Over the same stretch, the absolute volume collapses, from 1.43M in 2023 to around 448K in 2026, under a fifth of the 2022 peak. The two movements together are the key finding: even as total FIFA coverage shrank dramatically, the Qatar migrant-worker case captured a larger and larger share of what remained. Driving that residual are post-tournament findings: The non-payment of the migrant workers during the 2022 World Cup, the campaign for a migrant-worker compensation and remedy fund, and Amnesty's continued push for FIFA to fund remediation.A storyline that merely echoes the event would fade with the falling volume; one that accumulates does the opposite. The controversy is no longer powered by the match calendar but by its own momentum.
The Case Underneath
Underneath that residual sits the report's single heaviest case: the human-rights strand of 135 events running from 2020 to 2026, the longest-running and most densely populated case in the dataset. What stops it fading is that each turn of the hosting cycle reactivates it: the 2026 uptick to 6.49%, the highest reading outside the tournament year itself, coincides with the 2026 World Cup now underway in North America, which revives retrospective scrutiny of Qatar, and the emerging human-rights questions around Saudi Arabia's 2034 tournament, which carries the same migrant-labour lens straight to the next host. The case is not simply failing to fade; it is being actively topped up by each new host, which is why the social exposure reads as structural rather than event-bound.
Key Takeaways
Taken together, the data describes a profile that is primarily governance-related, with the most severe and persistent cases concerning legal exposure, corruption, and bribery, supported by a durable Qatar-rooted social overlay and a small but high-severity environmental tail. All three pillars reach maximum case intensity, so severity is not confined to any single dimension.
The most consistent feature is persistence. FIFA's Controversy Exposure Score has remained in the High-to-Very-High band throughout the period and sits at 99 today. The largest cases run continuously from 2020 to 2026, and a significant share of binding decisions occur outside tournament windows. None of this reduces the significance of the World Cup, which clearly concentrates attention and scrutiny. But the underlying controversy is produced across the quarters between tournaments, and several of FIFA's most consequential outcomes are set during lower-attention periods. For those screening FIFA, the practical implication is that continuous monitoring suits this profile better than event-triggered review, because much of the relevant activity occurs between tournaments rather than during them.
The data suggests that for an entity like FIFA, a four-year review cycle misses most of what matters. Request a demo to see how SESAMm supports the kind of ongoing monitoring this profile requires.
*The Controversy Exposure Score (CES) is a continuous score from 0 to 100 measuring a company's exposure to ESG controversies over time, based on the severity of incidents and their media volume. This is an unsolicited rating: it is not commissioned by the rated company. The company is notified before its score is first issued, does not take part in the rating, and SESAMm has no access to its management or non-public documents. Ratings are produced only from public and licensed sources. The methodology is available here.
Stay ahead with the latest in ESG and AI intelligence
Join our mailing list to receive new reports, event invites, and updates from SESAMm directly to your inbox.