
Insights & Updates

Blog thumbnail

Hydropower's ESG Paradox: Why the "Green" Asset Class Tops the Controversy Charts

August 20, 2026
5 mins read
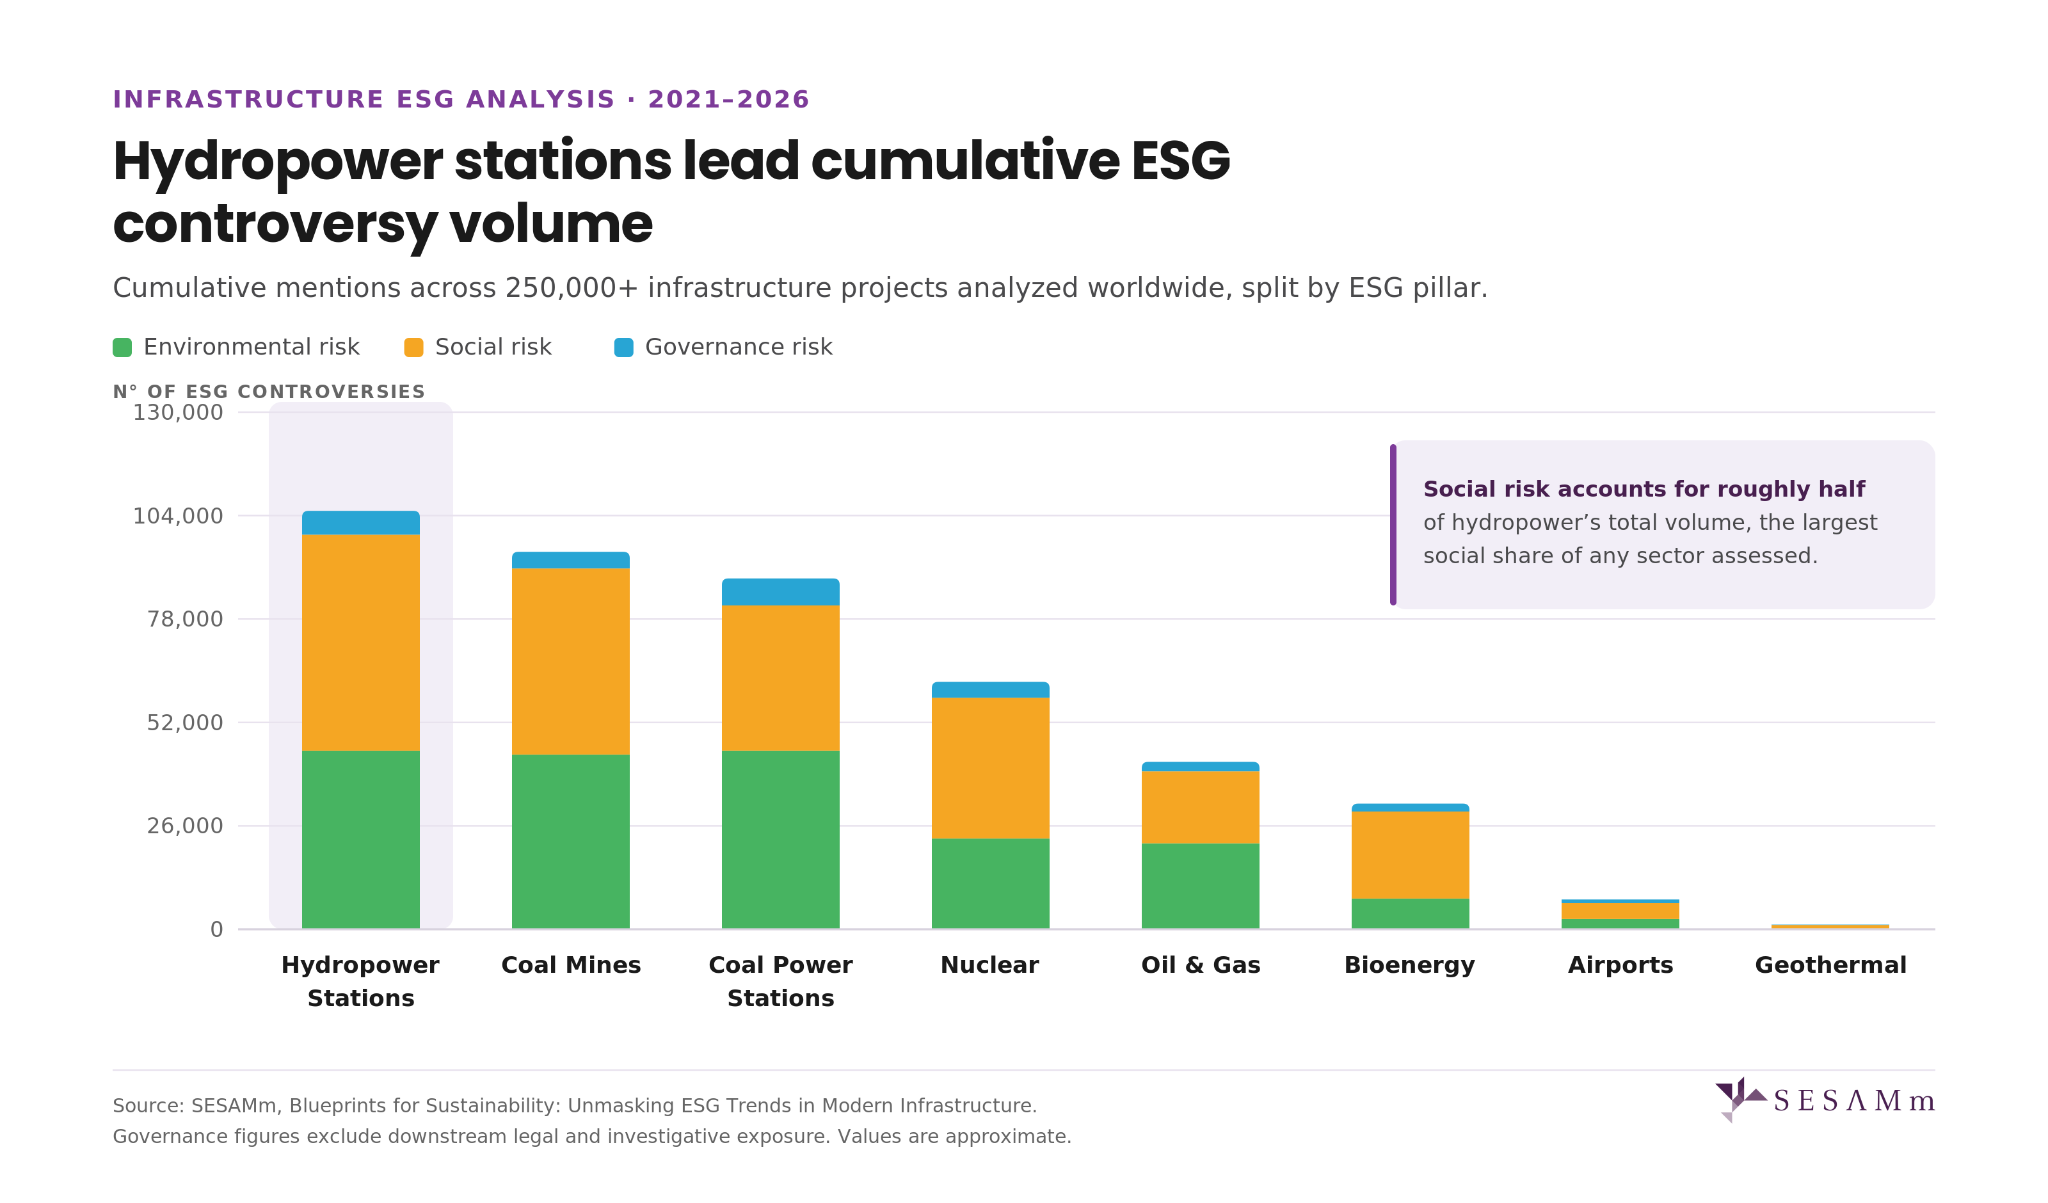
Hydropower tops ESG controversy volume across 250,000+ projects, outranking coal. Why the greenest label in energy hides the heaviest social risk.

An analysis of over 250,000 infrastructure projects reveals that the sector most often filed under "clean energy" carries the heaviest environmental and social controversy footprint of any asset type assessed.

In the taxonomy of energy infrastructure, hydropower occupies a comfortable position. It is renewable, dispatchable, and long-lived, and it enters transition frameworks, green bond eligibility criteria, and net-zero roadmaps with minimal friction. Where coal is a legacy liability to be managed down and nuclear invites a specialized debate, hydropower is largely treated as settled. What these projects have actually done does not support that treatment.
Belo Monte, an 11,233 MW complex on the Xingu River in Pará, Brazil, is the sharpest test of the point, because it was built to answer this exact objection. Approved after decades of opposition to a far larger design, it was engineered as a run-of-river plant to minimize flooding, and its reservoirs cover 478 km², of which 274 km² was already river channel at high water, a 61% reduction compared with the 1980s proposal, according to the operator's own regulatory filing. The mitigation was designed from the start, and everything that follows happened regardless.

Biodiversity: the cost of a physical footprint

Environmental controversy across infrastructure concentrates on industrial accidents, water pollution, and biodiversity, and hydropower leads the third, outright, because dams require the permanent conversion of river systems and the land around them. Mexico's Federal Electricity Commission won environmental approval in September 2014 for the Las Cruces dam on the San Pedro Mezquital, upstream of Marismas Nacionales, a Ramsar-protected wetland, even though the project's own impact statement conceded that the damage to Indigenous ceremonial sites could not be mitigated. Along the Mekong River, river health and fish populations fell as dam construction spread through the basin. In Brazil, the Doce River carried a mass release of toxic material after an upstream failure. Elsewhere, the record includes violations of the Endangered Species Act and documented disruption to rainfall patterns.

At Belo Monte, the consequences have been measured rather than projected. The plant diverts water into a canal that bypasses a 130-kilometer stretch of the Xingu known as the Volta Grande, which has received less than 30% of its natural annual discharge since 2019, and some 86% of the stretch's seasonally flooded vegetation, 30,748 of 35,600 hectares, can no longer be inundated at all. The gap lies in the regulator's own file: IBAMA's technical staff called for 10,900 cubic meters per second in February, the historic peak month, compared with the 1,600 that the operating regime actually releases. Seven years of underwater video survey data published in Scientific Reports recorded total fish species richness falling from 62 to a post-operation average of 51, with the steepest losses near the dam and in the rocky rapids, which hold roughly 2.6 times as many species as sandy reaches. The zebra pleco, whose entire known range lies inside the dewatered stretch, now sits on Brazil's national list of threatened species as critically endangered.

None of this is an accident or a failure of operation. It is a structural consequence of the asset. A well-run dam still floods a valley, and a dam engineered specifically not to flood one still dewater the river below it.

When engineering fails: hydropower's physical risk profile

Coal mining leads infrastructure on industrial accidents, where the record is dominated by human tragedy and safety negligence: explosions, collapses, fires, and repeated, incremental failures. Hydropower ranks second, but its accidents take a different form, because in this sector, industrial failure means catastrophic engineering failure at scale. The record includes pipe ruptures causing severe land erosion, oil leaks, and dam collapses that killed and displaced people across whole regions, while PG&E's settlement over damages to the Middle Fork American River Hydroelectric Project and the litigation still running in Brazil after dam collapses give a sense of the exposure a single event can generate. For anyone underwriting these assets, the distinction is financial as much as physical: a coal mine's safety record is a rising cost curve, while a dam's structural integrity is a low-probability, near-unbounded loss.

At Belo Monte, that exposure has so far been financial. The project was budgeted at R$28.9 billion when Brazil's development bank approved a then-record R$22.5 billion loan in November 2012, and by late 2017, actual investment had reached R$38.6 billion, roughly 34% over. The operator owed R$28.3 billion to lenders and debenture holders at the end of 2024. Aliança Norte Energia Participações, the Vale and Cemig vehicle holding a stake in the project, discloses a possible loss of R$3.05 billion from a single construction-delay claim and describes the operator's liquidity as its principal point of attention and a source of investor alert. Neoenergia wrote off its own 10% holding by R$482 million in the fourth quarter of 2021.

The physical risk has been closer than the absence of a collapse suggests. In October 2019, the operator wrote to the national water regulator declaring an emergency, because reservoir levels had fallen far enough to expose an unprotected section of the Pimental dam's earthfill base to wind-driven wave erosion and, in the company's own words, structural damage. It cut outflow below the level agreed with the environmental regulator to protect the structure, and the letter surfaced only through investigative reporting.

Beyond the environment: displacement, water, and chronic corruption

Right to property

Hydropower ranks first among infrastructure sectors for property disputes, a direct function of the footprint a dam and reservoir require. The record shows land seizures, forced displacement, compensation that arrives short or not at all, communities never consulted before ground was broken, and blasting that cracked the foundations of nearby homes. Those affected are frequently the least equipped to hold an operator to account.

Fifteen years after Belo Monte broke ground there is still no audited count of who lost their homes. Estimates run from 20,000 to 40,000 depending on the definition used, against the operator's account of rehousing some 6,000 urban families. Landowners say expropriations are priced at unadjusted 2013 values while the project's own construction boom inflated the market, and as of 2025 none of the land required for the riverine resettlement program had been bought. A petition filed with the Inter-American Commission in 2011 still has no ruling.

Community health and safety

Hydropower sits alongside coal and nuclear as a leading source of community health disputes, but it arrives by a different route. Coal delivers PM2.5, nuclear delivers radioactive anxiety, and hydropower delivers water mismanagement: overconsumption that strips farmers of a livelihood, contaminated water reaching local crops. The grievance is agricultural rather than industrial, which widens the affected population considerably.

On the Volta Grande, catch per fisher fell from 11.1 kilograms a day between 2001 and 2008 to 4.53 kilograms between 2020 and 2023. A randomized household survey found 38.5% of residents in Belo Monte's resettlement neighborhoods living with moderate or severe food insecurity, against 28.3% across the surrounding city. In June 2026, federal prosecutors sought as interim relief for 635 families along the reduced-flow stretch the emergency delivery of three and a half to five liters of drinking water per person per day.

Corruption and bribery

Corruption and bribery accounts for close to 30% of governance controversy across infrastructure. What separates hydropower is the pattern. In airports, nuclear, and coal, corruption surfaces as discrete scandals: a probe opens, executives are charged, attention fades. In hydropower it keeps returning, tied repeatedly to falsified records and payments to local officials to secure land and water rights. Isolated scandals point to isolated actors. A pattern that recurs points to how these projects get permitted.

Brazilian prosecutors alleged that Belo Monte's construction contracts carried bribes worth 1% of their value, and three contractors admitted cartel conduct and kickbacks under leniency agreements that carried immunity. Everything after that was procedural closure rather than a finding of liability: the principal defendants were acquitted and the acquittal upheld on appeal in 2024, the competition authority archived its bid-rigging case in 2025, and no individual has been convicted in connection with the project. An investor screening for enforcement outcomes would have found a closed file. The costs landed elsewhere, in permitting delay, financing conditions, and a minority stake that has been for sale since 2022 without a buyer.

Hydropower's risk concentration: what this means

Hydropower's classification as clean energy is accurate on the metric it was designed to measure, because generation is low-carbon. But carbon intensity is one dimension of sustainability, and it is not the dimension that produces operational friction, legal exposure, or the loss of a social license.

What drew sustained opposition to these projects was water rights, displaced communities, cracked foundations, converted wetlands, and permits secured through local payments. None of it appears in a carbon accounting framework.

For investors, insurers, and lenders seeking transition-aligned infrastructure exposure, that is a material blind spot: an asset class that screens well on the primary criterion while carrying the heaviest social burden in the dataset, and carrying it on behalf of people who have no employment relationship with it. Belo Monte was engineered to avoid precisely that outcome and produced it regardless, which suggests the exposure is not a function of how a dam is built but of what a dam is.

The label is not wrong. It is simply measuring something other than risk.
Read More

Human rights concerns took center stage in November, with rising scrutiny on how digital platforms and luxury brands safeguard vulnerable users and workers. Across the market, allegations of child exploitation, extremist activity, and labor abuses exposed significant governance and oversight gaps. The month’s top three most controversial companies were Roblox Corporation, Snap Inc. (Snapchat), and Tod’s, each facing escalating legal and regulatory pressure.

#1: Roblox Corporation: Intensifying Allegations of Child Exploitation

Roblox, the video game developer, experienced a surge of human rights–related controversies, driven by lawsuits and criminal cases involving child exploitation and online extremism. Multiple families in the United States filed suits alleging that predators used the game to groom and coerce minors, in some cases leading to severe psychological harm.

Regulators also increased pressure. The Texas Attorney General sued the company, accusing it of violating safety laws and misleading parents about the risks associated with young users. Additional criminal cases surfaced in the US, Ireland, and Argentina, where adults were convicted of grooming minors through Roblox. The company faced further backlash after its CEO referred to the child predator crisis as an “opportunity,” prompting criticism even as Roblox highlighted new age-verification tools aimed at improving safety.

#2: Snap Inc.: Social Messaging Platforms Under Renewed Scrutiny

Snap Inc., known for its messaging app Snapchat, emerged as the second-most controversial company in November following several serious incidents involving minors. In the United States, a missing 13-year-old girl was found in a Pennsylvania basement after meeting a man on Snapchat, who has since been charged with human trafficking and sexual assault. Another investigation led to the arrest of a New York man after Snapchat flagged suspected child sexual abuse material on his account.

At a broader level, new research from the Canadian Centre for Child Protection revealed widespread online sexual violence among youth, with Snapchat cited as one of the primary platforms involved. The company was also named in a major lawsuit filed by US school districts against Meta, Google, Snapchat, and TikTok, alleging that platforms suppressed internal research on youth harm and failed to implement meaningful protections.

#3: Tod’s: Supply Chain Labor Abuses Trigger Legal Action

In the luxury sector, Tod’s faced heightened scrutiny following new developments in an ongoing investigation into labor exploitation at its supplier factories. Italian prosecutors expanded their probe into three company executives, citing evidence of serious labor violations involving 53 workers employed by subcontractors. Issues raised included long working hours, low wages, inadequate safety standards, and poor living conditions.

Authorities also highlighted potential negligence and omissions by management, arguing that Tod’s failed to act on inspection findings that documented the abuses. Prosecutors have requested a six-month advertising ban and previously sought judicial administration over the company’s supply chain controls.

Conclusion

November’s top controversies underscore increasing pressure on companies to ensure robust human rights protections, both online and across global supply chains. As regulators, law enforcement, and civil society intensify oversight, firms in technology and consumer markets face rising expectations to demonstrate stronger safety systems, transparent governance, and proactive risk management.

Reach out to SESAMm

TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.

When Meta's market value declined by $307 billion over four trading days in October 2025, it demonstrated a fundamental shift in how markets process reputation risk. Algorithmic systems detected, interpreted, and priced a narrative misalignment faster than the company's internal coordination process could respond.

This wasn't an isolated event. It reflects how AI has restructured the relationship between reputational events and market consequences.

The Collapse of Sequential Crisis Management

Corporate crisis management has historically relied on sequential stakeholder awareness. A controversy would surface in local media, then spread to analysts, then national coverage, then institutional investors, with retail awareness coming last. This sequence provided time, days, or weeks to investigate, coordinate across functions, and craft targeted responses.
AI has eliminated that sequence.

Today, hedge funds run real-time controversy models that trigger trades within hours. Institutional investors receive automated NLP alerts. ESG vendors update scores continuously by scanning billions of multilingual sources. Proxy advisors flag governance risks in near real-time. Retail investors access sentiment apps that surface issues instantly. NGOs monitor local-language supply chain incidents globally. Regulators deploy automated surveillance that detects patterns before companies file reports.

The result: external stakeholders now see the same signals simultaneously. The response window has compressed from 24–48 hours to sometimes just hours.

How Fast Has “Fast” Become?

The compression is measurable. Compare crisis timelines before and after AI became standard:

Pre-AI Era (2010-2020)

BP Deepwater Horizon (2010): Destroyed $60B in market value in one month, ultimately reaching $100–105B over two months.

Wells Fargo fake accounts (2016): Evolved over three weeks, creating multiple response windows.

Boeing 737 Max (2019): Erased $27B in two days, $40B in two weeks, and $62B over five months as investigations unfolded sequentially.

AI Era (2023-2025)

Meta (Oct 2025): Lost $307B in four days once algorithms flagged narrative misalignment.

Bud Light (2023–2025): A single controversy generated $27B in value destruction within two months and sustained 40% sales declines.

Tesla:  Recalls and investigations repeatedly triggered rapid volatility across compressed time frames.

The pattern is consistent: crisis timelines have collapsed from months to weeks to days.
Regulatory cycles have accelerated as well. The SEC and other agencies now deploy automated surveillance tools, and in several cases, enforcement actions have been disclosed before companies completed internal investigations.

Why Companies Discover Crises Late

Most companies learn about reputational issues after external stakeholders have already detected and acted on them.

Four Categories of Monitoring Tools

  1. Basic keyword tools: Fast, but lack sentiment, context, and depth.
  2. Media monitoring platforms: Broad coverage, high volume, and low material clarity.
  3. AI extraction engines: Add interpretation, but lack access to investor-grade sources.
  4. AI-driven controversy analytics (SESAMm, RepRisk, TruValue Labs, Verisk Maplecroft): Apply large-scale NLP to billions of multilingual data points, including regulatory filings, NGO reports, and local-language media. Platforms operating at this scale - SESAMm alone monitors over 5 million companies across 4 million+ sources, including private firms in low-disclosure markets -  provide visibility most corporates do not have.

This is where the detection gap originates: most corporates rely on categories 1–2; markets rely on category 4.

The Coordination Gap

Reputation responsibilities typically sit across Communications, IR, ESG, Risk, Legal, Public Affairs, regional leads, and business units. Each has separate systems and approval paths.

When crises unfold over hours, this structure becomes a bottleneck.

Sector-Specific Amplification Patterns

AI accelerates information flow differently by industry:

Pharmaceuticals: Clinical data travels through medical networks → hedge funds within 4–6 hours.

Financial Services: Disclosure anomalies → lawyers → regulators in days, not weeks.

Consumer/Energy (complex supply chains): Supplier issue → local media → NGOs → retail boycotts in 48–72 hours.

Generic plans fail because velocity is industry-specific.

What Leading Organizations Are Building

Companies adapting to machine-speed markets are focused on closing the detection gap and compressing coordination cycles.

A Pre-release AI Content Analysis

Before major disclosures, leading organizations now assess:

  • What controversy categories may be triggered
  • Expected sentiment scores
  • Governance themes algorithms will extract
  • Phrases correlated with a negative reaction in their sector

This is not message sanitization, it's anticipating how machines will interpret the content.

Compressed Coordination Frameworks

Organizations have implemented pre-authorized workflows enabling response in 2–4 hours:

  • Pre-cleared language templates
  • Simplified approvals
  • Clear escalation thresholds
  • Regular simulation exercises

Stakeholder ecosystem mapping

Understanding who detects what and how issues escalate allows for proactive engagement with NGOs, analysts, sentiment communities, short sellers, and others.

Unified monitoring infrastructure

Shared dashboards give all functions real-time visibility into:

  • Sentiment shifts
  • Controversy score changes
  • ESG rating movements
  • Supply-chain signals
  • Retail sentiment trends

Some organizations have begun deploying AI agents to automate entire steps: summarizing incidents, assessing severity, and routing them to the correct teams, helping move from detection to coordinated action with far less manual effort.

Financial Quantification

Boards increasingly expect:

  • Expected volatility ranges
  • Funding cost implications
  • Correlation with institutional flows
  • Proxy voting impacts

Reputation must now be expressed in capital markets language.

The Governance Shift

Reputation is migrating into integrated risk committees with representation from Finance, Risk, Legal, Corporate Affairs, and IR. Some boards now use real-time dashboards with automated escalation.

Controversy detection is being incorporated into materiality assessments, proxy preparation, and disclosure committee processes.

Practical Implications Across Functions

  • IR explains volatility driven by algorithmic pricing of signals not yet internally detected
  • Communications must prioritize speed alongside accuracy
  • Risk quantifies reputation financially
  • ESG manages real-time score shifts
  • Legal faces enforcement that may precede internal review
  • Public Affairs addresses issues that now cross borders instantly
  • C-Suite must increase coordination speed

Conclusion

AI has compressed crisis timelines from months to days and eliminated sequential stakeholder awareness. Markets now detect, interpret, and act on reputational signals faster than traditional internal processes.

Organizations that close the detection gap and compress coordination to hours rather than days gain measurable advantages in volatility management and stakeholder confidence.
The assumption that companies can control when stakeholders become aware of reputational issues is no longer valid. Crisis response must now match the speed at which markets process risk.

Reach out to SESAMm

TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.

ESG

ESG Assessment: LVMH

December 10, 2025
5 mins read

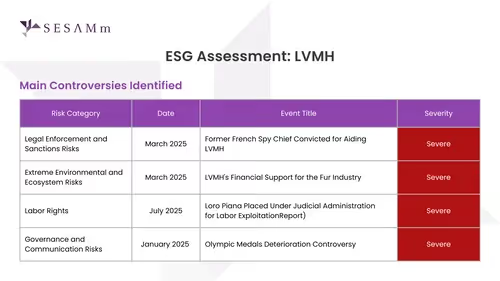
SESAMm’s AI-generated ESG Assessment Reports deliver fast, sharp insights into the ESG performance, risks, and controversies of leading global companies in under 30 minutes. Designed for investors, risk teams, and sustainability leaders, they surface the issues that matter most for due diligence and portfolio oversight. In this edition, we dive into LVMH, one of the world’s largest luxury groups, to see how its sustainability ambitions stack up against the challenges it faces. Explore the summary below or fill out the form to receive your own free AI-generated report.

ESG AI Screening Report Summary: LVMH

LVMH Louis Vuitton Moët Hennessy SE (LVMH) is a leading French multinational conglomerate in the luxury goods sector, with a diverse portfolio of 75 brands across fashion, wines, spirits, cosmetics, and more. Despite its strong market position, LVMH faces significant ESG challenges. A major red flag is the €8 million fine by the French Autorité des Marchés Financiers for failing to disclose its acquisition of a stake in Hermès, highlighting governance and transparency issues. The company has been criticized for environmental impacts, including deforestation linked to its leather supply chain and allegations of greenwashing. Social risks are also prominent, with labor exploitation cases in its supply chain and allegations of workplace harassment.

On the positive side, LVMH claims robust environmental targets, such as a 55.1% reduction in Scope 1 and 2 emissions by 2024, and significant investments in renewable energy. The company is a signatory of the UN Global Compact, indicating a commitment to international sustainability standards.

However, the luxury goods industry inherently faces severe ESG risks due to high scrutiny and frequent controversies, such as cultural appropriation and labor issues. LVMH's ESG reporting is comprehensive, with detailed disclosures on environmental and social initiatives, but the presence of significant controversies suggests a need for improved governance and transparency.

The ESG landscape for U.S. private equity firms is increasingly defined by systemic governance pressure and rising social and environmental scrutiny. Governance issues at firms such as Blackstone, KKR, Thoma Bravo, TPG, and Francisco Partners primarily focus on deal processes, disclosure practices, and investor protection. These concerns encompass settlements related to pension mismanagement, actions taken by the Department of Justice regarding pre-merger filings, as well as lawsuits and shareholder investigations examining the fairness of take-private transactions and stock buybacks. On the social side, exposure is driven largely by portfolio companies and political positioning. Housing and tenant-rights disputes sit alongside allegations of labor abuses, child labor, and unsafe conditions. Environmental concerns are increasingly prominent, with major companies facing criticism for their exposure to fossil fuels, their impact on climate change, and associated lobbying efforts.

What are the most pressing ESG challenges currently facing the U.S. private equity firms? Read on to find out.

Blackstone: Governance Pressure, Social Backlash, and Climate Criticism

Blackstone is facing a wide range of ESG controversies. Governance challenges include a $227.5 million settlement related to Kentucky pension mismanagement, a $590 million lawsuit involving SPAC Recovery Co. that alleges a fraudulent scheme, and SEC fines tied to off-channel communications failures. On the social front, the firm has drawn criticism for political spending that heavily favors right-leaning candidates, child-labor incidents, and recurring safety violations at portfolio companies. Housing-related concerns also persist, with tenant protests over rent and eviction practices and university movements calling for divestment from Blackstone-linked real estate funds. Environmentally, Blackstone continues to be targeted by climate activists for its fossil fuel exposure and its perceived contribution to escalating climate risks.

Key Controversies:

Reach out to SESAMm

TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.

In a recent interview, CEO Sylvain Forté spoke with Fintech Global about how the SESAMm has evolved, the role of AI in transforming ESG risk detection, and what's next for the industry.

Can you tell us about SESAMm's origins and how the company has evolved since 2014?

SESAMm started with a focus on analyzing sentiment and reputational signals on social media to understand how narratives influenced financial performance. We began by working with asset managers and quickly realized that reputational risks were not only impacting public equities but were becoming critical in other asset classes.

As we evolved, we discovered a much broader blind spot in private markets. ESG and reputational data simply didn't exist for private companies, infrastructure projects, or suppliers, yet these made up a significant share of global exposure. This expansion was supported by Carlyle, a leading private equity firm and a SESAMm investor, which helped us deepen our expertise in private markets. Since then, we've expanded to supply chain and procurement use cases as well.

The name SESAMm stands for "open sesame." We were designed to unlock this missing layer of insight, opening access to critical ESG risks across public, private, and supply chain assets.

How is AI transforming the way financial institutions detect and understand ESG risks?

AI is a fundamental enabler of SESAMm's platform. We cover over 5 million companies, public and private, across more than 4 million sources, making it the largest private asset ESG coverage in the industry. This would be impossible to maintain with traditional manual workflows.

But our AI enables not just massive scale; it delivers quality. We aggregate documents, match events over multiple years, classify and score controversies properly, and do all of this in real time. There is no lag between detection and delivery.

We've gone further than data delivery. With AI agents, we've moved from surfacing insights to solving real problems. For example, for an insurance company, our AI agents don't just provide controversy data; they fully complete underwriting risk questionnaires. This is not just enhanced ESG; it's a workflow transformation.

Can you share an example where SESAMm caught an ESG signal that others missed?

One example is Loro Piana, an LVMH company, where we were able to surface early signals from regional news and filings before they became broadly visible.

For private markets, some of our clients, including major US private equity firms, have used our insights to stop due diligence processes early, saving millions of dollars by identifying major ESG risks at the pre-deal stage. These events were buried in local reports or niche sources and would have gone undetected using traditional tools. This is where SESAMm's multilingual, real-time coverage delivers immediate and material value.

How does SESAMm's global, multilingual scope lead to better ESG insights?

SESAMm's reach is a key differentiator. We process content from over 100 languages and 4 million data sources, including local news, NGO reports, legal documents, blogs, and more. For global private investment firms, this makes it possible to monitor hundreds of portfolio companies and thousands of credit lines every single day, without human intervention.

Due diligence becomes instant. Customers can type a company name into the platform and get immediate access to source data, scores, and an auto-generated report. This level of coverage and automation is only achievable with AI. Without multilingual processing, most of these risks would remain hidden in local languages and never surface in English datasets.

What role does Generative AI play in turning complex data into actionable intelligence?

GenAI allows us to go beyond raw data or filtered alerts. SESAMm now delivers fully automated ESG due diligence reports in under 30 minutes, complete with citations, severity levels, and multi-language source integration. These are dynamically built with real insights. The same applies to legal reports, private equity and M&A deal screening, secondary and credit due diligence, and more.

Teams no longer need to sift through events, tag them, write memos, or manually structure reports. We also accelerate regulatory workflows by automatically flagging potential significant harm, governance issues, and controversial activities, enabling clients to meet disclosure requirements more quickly and focus their time on high-impact actions.

SESAMm has announced partnerships with Clarity AI and Sayari. How do these enhance your offering?

These partnerships are both strategic and complementary. SESAMm offers comprehensive data coverage, particularly for private firms and complex events, which many partners utilize to enhance their own offerings. Sayari enhances the mapping of supply chains and tier-N suppliers. Clarity AI provides a full ESG analytics platform. SESAMm plugs into each of them, either as a source of controversy intelligence or to enrich end-user offerings.

In return, they help our clients go further, from data to action, whether through real-world audits, regulatory support, or deeper portfolio insights. The goal is to offer an ecosystem of ESG solutions that go beyond alerts and into implementation.

Why are financial institutions now treating ESG and reputational risk as strategic intelligence rather than just compliance?

The stakes are higher than regulation. Of course, frameworks like SFDR and PAI 10 are important, but firms come to us because they need actionable insight. Corporates monitor their suppliers and group entities. Investors track portfolio companies, screen for risk during deal flow, and respond to reputational events.

ESG controversies now have direct financial implications, influencing deal approvals, investment decisions, and valuations. This is especially true in private markets. We work with both LPs and GPs to integrate controversy detection into due diligence and ongoing monitoring. In many cases, ESG insights are the trigger for early engagement or the reason to walk away from a deal.

What do you see as the next frontier for AI in ESG and reputational risk?

The next frontier is clearly AI agents. SESAMm is already building and deploying agents that automate entire workflows, from detection and classification to full reporting. This includes ESG due diligence in 30 minutes, secondary screening, good governance screening, controversial activity screening, legal risk reports, and more.

For secondary funds, this means being able to screen hundreds of underlying assets in hours, not days. For compliance teams, it means automated risk reports with source evidence and scoring. For ESG professionals, this means saving time to focus on engagement, strategy, and impact, rather than data wrangling.

We believe AI agents will power the next generation of ESG intelligence, providing seamless, embedded, and action-ready solutions.

Click here to access the full ESGFintech100 2025 report.

Reach out to SESAMm

TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.

By Magnus Billing, SESAMm advisor, with insights from Sylvain Forté, CEO of SESAMm

Investors have faced so-called “black swan” events throughout history: unexpected crises with severe consequences, often rationalized only in hindsight. Yet in an era defined by generative AI and vast, real-time data lakes, the question arises: could such events be understood and acted upon before they unfold?

The 2023 U.S. regional banking crisis offers a striking case study. The rapid collapses of Silicon Valley Bank and Signature Bank revealed how quickly stress can spread and how difficult it remains to connect early warning signs across sources.

While traditional financial analysis focuses on fundamentals such as capital ratios, liquidity positions, governance, and earnings, a new class of tools is expanding the lens. AI-driven controversy data aggregates and analyzes millions of public sources, from regulatory statements to media and industry discussions, to detect emerging issues as they surface. It does not replace quantitative and fundamental analysis; it complements it by tracking the visibility of risk as it enters public conversation.

This combination of approaches may offer investors a fuller picture: the structural risks visible in balance sheets, and the narrative risks revealed through public dialogue. To test this idea, we revisited the 2023 crisis through both perspectives, starting with what traditional analysis could have shown and what it missed.

Traditional Analysis and Its Blind Spots

In hindsight, the vulnerabilities of regional banks such as Silicon Valley Bank and Signature Bank were visible before the start of 2023. Unrealized losses on long-term securities, heavy reliance on uninsured deposits, and exposure to interest-rate risk pointed to potential liquidity stress. Yet these indicators were neither fully recognized nor connected in the market.

Traditional analysis has a tendency to evaluate banks based on their specific niches: Silicon Valley Bank focused on technology and venture financing, while Signature Bank served commercial real estate and digital asset clients. However, this approach risks overlooking the common and shared structural factors: concentrated depositor bases, high sensitivity to interest rate changes, rapid growth, and weaknesses in governance. Few, if any, observers recognized how rapidly these vulnerabilities could interact and escalate in a modern, digitalized banking environment.

While financial reports contained the data, there was little discussion connecting these risks in the public domain. But what about controversy data? Would it have caught the impending crisis? To find out, I asked Sylvain Forté, CEO of SESAMm, to provide an AI perspective.

What the Data Showed: Signature Bank

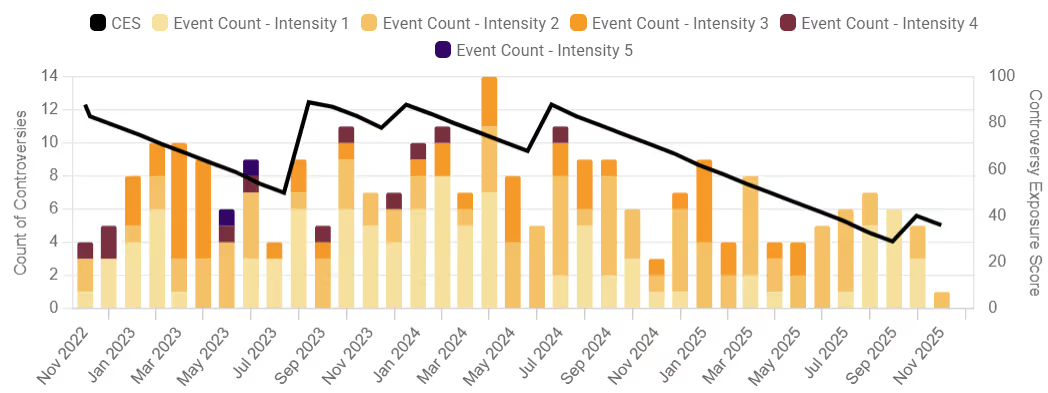
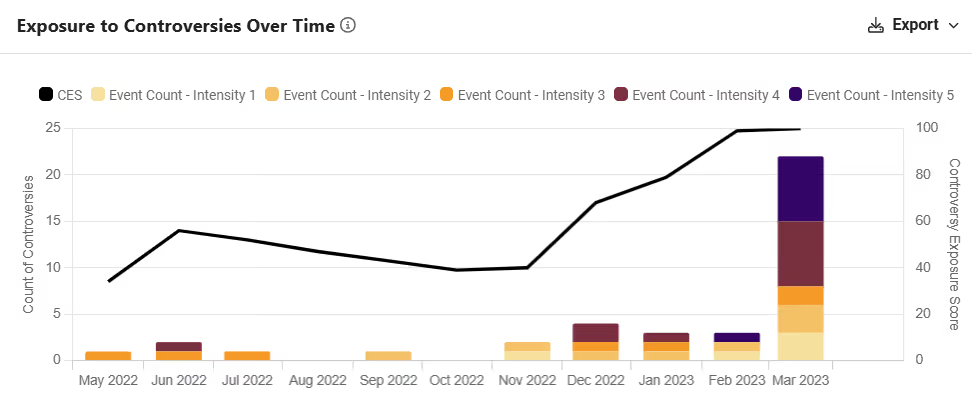
Signature Bank displayed a gradual pattern of emerging risk visible through public discussion. From mid-2022 onward, controversy data showed a rise in coverage related to governance practices, management oversight, and deposit concentration risks, often in the context of its ties to the digital-asset industry.

Importantly, it was not the crypto exposure itself that led to the bank’s collapse. The bank even announced in December 2022 that it would reduce its crypto-related business. Instead, the FDIC’s Supervision of Signature Bank report concluded that, “the root cause of SBNY’s failure was poor management. SBNY’s board of directors and management pursued rapid, unrestrained growth without developing and maintaining adequate risk management practices and controls.”

From a controversy perspective, those signals were publicly visible but fragmented. As shown in the chart above, AI-powered monitoring could have aggregated them into a clear view of a sustained drift in governance-related discussions, offering an early indication that oversight and internal controls were under pressure and risk was increasing.

What the Data Missed: Silicon Valley Bank

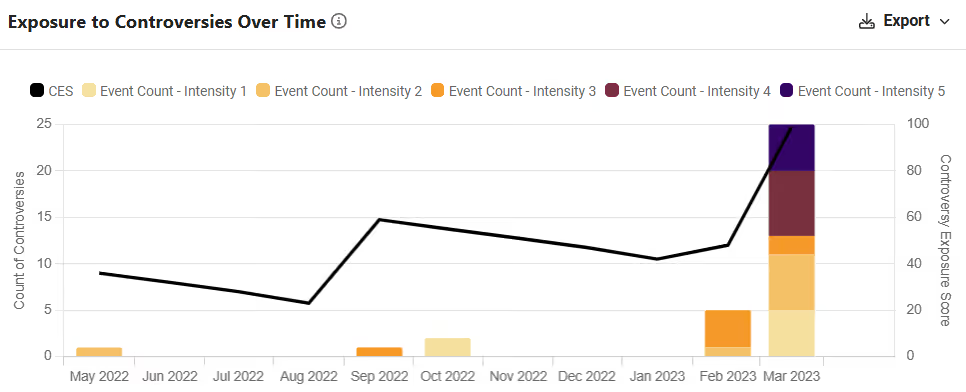
In contrast, Silicon Valley Bank presented a markedly different pattern. While controversy data registered some activity in late 2022,  including investor reactions to financial forecasts and coverage of routine business operations, these signals were fundamentally different in character from Signature Bank's governance-related warnings.

The September 2022 increase reflected market disappointment with financial guidance rather than operational or governance concerns. The subsequent activity captured normal business news, such as arranging syndicated loans. Critically, there was minimal public discussion of the bank's balance-sheet structure, unrealized losses, or depositor concentration risk until the crisis was already unfolding in March 2023.

This example underscores a key distinction: AI controversy monitoring excels at capturing reputational, governance, and operational risks as they enter public dialogue, but may not surface structural financial risks that remain confined to regulatory filings and analyst reports.

Lessons from Both Cases

The contrast between these two banks illustrates the complementary roles of quantitative and fundamental financial analysis vs AI-driven controversy monitoring.

In Signature Bank’s case, controversy data captured a steady accumulation of governance-related warnings, a slow build-up of risk visible through public discussion.

In Silicon Valley Bank’s case, the risks were structural but not yet discussed, leaving little for AI-powered controversy data to detect.

As Sylvain explains, “AI controversy monitoring helps investors understand how and when risks start to emerge in public dialogue. It does not replace fundamental analysis. It complements it by showing when the conversation begins to shift.”

Conclusion

Black swan events are often rationalized only in hindsight, but the 2023 regional banking crisis suggests a more nuanced reality. Some signals existed. What remained difficult was connecting them across sources before stress became contagion.

AI-driven controversy monitoring proved effective at surfacing governance and operational risks as they entered public dialogue, as Signature Bank demonstrated. Yet structural financial vulnerabilities like those at Silicon Valley Bank may not generate discussion until crisis forces the conversation, underscoring that no single lens captures all risk.

The advantage lies not in prediction, but in preparation: combining the structural risks visible in balance sheets with the narrative risks revealed through public discourse. In an era of real-time data and generative AI, the question is no longer whether information exists, but whether investors can connect it before it becomes consensus.

Reach out to SESAMm

TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.

COP30 has just begun in Belém, Brazil. Every year, the Conference of the Parties (COP) serves as the world’s central stage for climate diplomacy, where governments, scientists, and civil society gather to decide how to respond to the global climate emergency. Over the decades, these meetings have shaped major milestones, from the Kyoto Protocol to the Paris Agreement. Yet behind the speeches and pledges, questions persist: how much progress is being made on the ground, and how inclusive are these negotiations in practice?

As countries meet again to assess their collective efforts, looking back at the most recent COPs offers a perspective on how politics, accountability, and competing interests continue to influence the global climate agenda.

What Is the COP?

The Conference of the Parties (COP) is the annual United Nations summit that brings together the 198 signatories to the 1992 UN Framework Convention on Climate Change (UNFCCC). Its purpose is to coordinate international action on climate change through negotiation, progress assessment, and new commitments to reduce greenhouse gas emissions.

COPs are usually held in November or December and last about two weeks. The first took place in 1995 in Berlin, and the tradition has continued ever since. COP27 was hosted by Egypt in 2022, COP28 by the United Arab Emirates in 2023, and COP29 by Azerbaijan in 2024. This year, COP30 marks Brazil’s turn to host the event in the Amazonian city of Belém.

Over the years, COPs have produced landmark outcomes, from the Kyoto Protocol (1997) to the Paris Agreement (2015). More recent debates have focused on climate finance, adaptation, and the global transition away from fossil fuels. Yet, as recent conferences show, progress often comes with friction, delays, and controversy.

The COP Controversies Over the Years

COP27 (2022) - Egypt

Held in Sharm el-Sheikh, COP27 centered on the question of climate justice. Developing nations demanded compensation for loss and damage caused by climate impacts that they did little to create. Therefore, the creation of a Loss and Damage Fund was a landmark step, though details on financing and governance were deferred.

Egypt’s hosting of the summit drew criticism over restrictions on civil society. Amnesty International reported hundreds of arrests before the event, including activists detained for online content. Tight surveillance and limited protest spaces highlighted how political control intersected with the climate agenda.

Meanwhile, energy security concerns following the war in Ukraine exposed inconsistencies in global climate policy. Some European nations resumed coal use or sought new gas projects in Africa, while methane leaks from natural gas infrastructure were found to be worse than estimated. These developments raised questions about whether short-term energy strategies were undermining long-term climate goals.

COP28 (2023) - United Arab Emirates

The 2023 summit in Dubai was among the most debated in COP history. The appointment of Sultan Al Jaber, CEO of the Abu Dhabi National Oil Company, as COP president drew immediate criticism over conflicts of interest. Al Jaber’s comments, suggesting there was “no science” supporting a fossil fuel phase-out, only deepened the controversy.

Leaked letters from OPEC revealed coordinated lobbying to block references to phasing out fossil fuels in the final text. Despite this, over 100 countries advocated for clear language on ending fossil fuel use. The resulting “UAE Consensus” included the phrase “transitioning away from fossil fuels,” the first such mention in COP history. However, critics noted that the wording allowed broad interpretation and loopholes for continued production through “abatement” and carbon capture.

The summit also drew scrutiny for restrictions on activism. Human Rights Watch documented limits on protests, surveillance of delegates, and constraints on speech. Still, COP28 produced incremental steps on renewable energy commitments and adaptation finance, even as it highlighted the influence of the fossil fuel industry on global negotiations.

COP29 (2024)  - Azerbaijan

In Baku, COP29 took place under similar scrutiny. Azerbaijan’s record on press freedom and civil rights was a major concern, with several journalists and activists arrested in the months before the event. Human rights advocate Anar Mammadli and economist Gubad Ibadoghlu were among those detained on politically motivated charges.

The conference also saw diplomatic tensions flare when President Ilham Aliyev criticized Western countries in his opening speech, prompting France to boycott the event. Regional issues, including the aftermath of the Nagorno-Karabakh conflict, added to the complex political backdrop.

The negotiations were dominated by debates over climate finance. Wealthy countries announced a target of $300 billion annually by 2035, largely relying on private capital and multilateral banks. Developing nations argued that the proposal lacked direct grant funding and risked increasing debt burdens. Observers reported confusion and frustration over the agreement’s final approval, with some delegations absent when it was gaveled through.

COP29 concluded with calls for greater transparency, inclusivity, and consistency in how future summits are hosted and managed.

Patterns and Lessons

Across COP27, COP28, and COP29, several common threads emerge. Each conference underscored both the urgency of global climate action and the difficulties of collective decision-making. The creation of new financial mechanisms and the first explicit reference to moving away from fossil fuels were significant steps. Still, they came alongside persistent divisions over fairness, responsibility, and implementation.

A recurring criticism has been greenwashing: the gap between rhetoric and reality. Host countries often present themselves as champions of sustainability while remaining heavily dependent on fossil fuels. At the same time, the presence of record numbers of industry lobbyists, particularly from oil and gas companies, has raised concerns about the balance of influence in climate negotiations.

These issues point to a broader tension: how to ensure that the COP process remains a platform for genuine progress rather than symbolic gestures. Many observers argue that transparency, stronger accountability mechanisms, and better inclusion of civil society are essential to rebuilding trust in the process.

Conclusion

As COP30 unfolds in Brazil, the focus is again on implementation and credibility. The last three conferences demonstrated how progress can coexist with controversy, and how global ambition must be matched by local action and political will.

While the COP framework remains the cornerstone of international climate cooperation, its effectiveness depends on whether commitments are translated into tangible outcomes. The coming days in Belém will show whether lessons from past conferences can help turn dialogue into decisive progress.

Reach out to SESAMm

TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.

As regulatory scrutiny intensifies across industries, several major corporations faced significant legal challenges related to anti-competitive behavior in October 2025. Using SESAMm's AI-powered controversy data, we analyzed corporate activity to identify the companies most involved in anti-competitive practices during the month. The results reveal a pattern of regulatory action spanning tech giants, financial services, and food production sectors.

#1: Alphabet: Mounting Regulatory Pressure

Alphabet

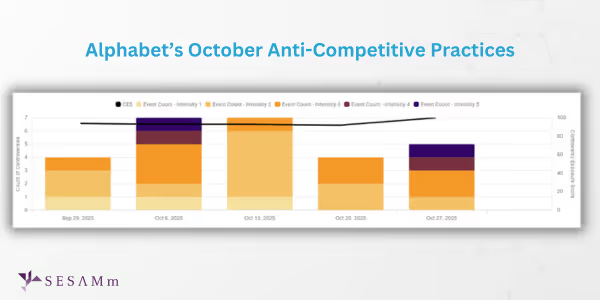
Alphabet continues to face unprecedented legal challenges across multiple jurisdictions. The company is facing a substantial $8.3 billion lawsuit from Klarna, alleging anti-competitive practices in the Android market. The situation intensified when the U.S. Supreme Court denied Google's request to delay mandated changes that would open Google Play to rival app stores.

Adding to these concerns, a federal judge is now examining whether Google can legally bundle its Gemini AI app with other services, a move that could significantly extend its market power into emerging AI markets. Perhaps most significantly, the Court of Justice of the European Union upheld a €2.4 billion fine against Google for self-preferencing in Google Shopping, reinforcing the legal framework against such anti-competitive behaviors and establishing stronger regulatory precedent for digital platforms.

#2: Visa: Financial Services Under Fire

Visa

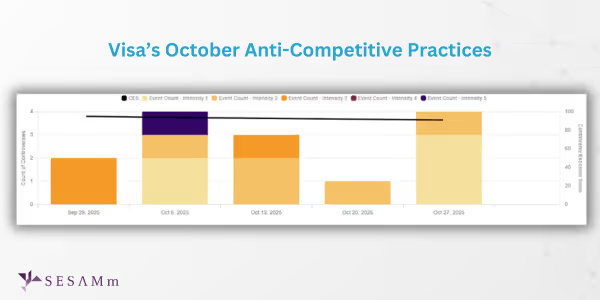
Visa continues to face legal and regulatory pressures across multiple jurisdictions. In the United States, the long-running merchant fee antitrust litigation (MDL 1720) remains active, with ongoing appeals and challenges to proposed settlements. Several merchant groups that opted out of earlier agreements have been permitted by the courts to continue pursuing their claims, extending Visa’s legal exposure.

The company's $5.3 billion acquisition of Plaid has drawn intense scrutiny from the U.S. Department of Justice, reflecting growing concern about consolidation in the fintech sector. Meanwhile, across the Atlantic, the UK Competition Appeal Tribunal delivered a landmark ruling against both Visa and Mastercard, determining that their Multilateral Interchange Fees violate competition laws; a significant victory for European merchants and a potential precedent for future cases.

#3: Tyson Foods: Settling Price-Fixing Allegations

Tyson Foods

The meat processing industry's legal troubles continued in October, with Tyson Foods at the center of multiple settlements. The company, along with Cargill, agreed to settle a beef price-fixing lawsuit for $55 million and $32.5 million, respectively. These settlements contribute to a broader $208 million resolution in related consumer cases, although litigation against JBS and National Beef continues.

Beyond beef, Tyson reached an even larger $85 million settlement in a separate antitrust case concerning pork price inflation, the largest settlement to date in ongoing litigation against major U.S. meat producers.

Conclusion

The findings from October 2025 underscore a critical moment in corporate regulation, as authorities worldwide demonstrate an increased willingness to challenge anti-competitive practices in sectors ranging from technology and finance to food production. The substantial fines, denied appeals, and ongoing investigations signal a regulatory environment that is actively reshaping market dynamics.

For investors and market observers, these cases highlight the material financial and operational risks associated with anti-competitive behavior. As enforcement mechanisms strengthen and legal precedents solidify, companies across all sectors should anticipate heightened scrutiny of market practices, particularly those involving platform dominance, merger activities, and pricing coordination.

Reach out to SESAMm

TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.

Industry News

UK to Regulate ESG Ratings Providers: Why It Matters

November 4, 2025
5 mins read

In a landmark move for sustainable finance, the UK government has announced plans to regulate ESG (Environmental, Social, and Governance) ratings providers. The Financial Conduct Authority (FCA) will soon be tasked with overseeing these firms, marking a major shift from the current hands-off approach. This development comes amid growing concerns about the inconsistency, opacity, and influence of ESG ratings on investment decisions.

Why Regulate ESG Ratings Providers?

The regulatory gap in ESG ratings is clear when compared to traditional credit ratings. Credit rating agencies (like S&P, Moody’s, and Fitch) operate under strict regulatory oversight and well-defined methodologies, which is one reason their assessments tend to be closely aligned. In fact, one study found the top credit agencies’ ratings are 99% correlated, whereas ESG ratings from different providers showed only about 60% correlation. In practice, that means two ESG raters might disagree as wildly as “AAA” vs “BBB” for the same firm in the same period. By contrast, it’s rare to see such divergence in credit ratings because that industry has long been supervised and standardized.

Absent regulation, ESG ratings have been opaque and inconsistent. Regulators and market watchdogs have likened the ESG ratings arena to a “Wild West” in need of a sheriff. An environment “unregulated and opaque” where even companies with poor environmental track records can sometimes score surprisingly well. The lack of transparency in how ratings are determined makes it hard for investors to trust what an ESG score truly reflects. This opacity not only fuels skepticism but also raises the risk of greenwashing, where unsustainable companies might hide behind inflated ESG scores.

New oversight aims to bring transparency, consistency, and trust to ESG ratings. Authorities around the world are now stepping in. For instance, the UK government has introduced legislation to bring ESG rating providers under the Financial Conduct Authority’s remit. Similarly, European regulators (ESMA in the EU) and others in Japan and India are moving toward tighter standards. The consensus is that ESG ratings need basic guardrails, much like credit ratings, to ensure they are rigorous, reliable, and free of conflicts of interest. As one analysis noted, if a credit rating agency were to suddenly downgrade scores at the scale we’ve seen with ESG re-ratings, regulators would have intervened immediately. Treating ESG ratings “similarly” to credit ratings in terms of oversight is increasingly seen as necessary to prevent nasty surprises (read: unexpected discrepancies) and to maintain market stability.

Regulation can address several issues: it can mandate clearer methodological transparency, require disclosure of rating drivers, and enforce governance standards (for example, to manage conflicts of interest if a rater also offers paid consulting). All of these steps would help investors and companies finally peek behind an ESG rating. In other words, examine the underlying factors, rather than taking scores at face value. Ultimately, effective regulation should turn ESG ratings from a black box into a more consistent, credible tool for decision-making.

What the UK Plans to Do

Under the new legislation, any ESG ratings provider serving UK clients will be required to obtain authorization from the FCA. These firms will need to disclose their methodologies, manage conflicts of interest, and maintain proper governance controls. The regulation is designed to align with international recommendations, such as those from IOSCO, and mirrors similar efforts already underway in the EU.

The goal is to bring greater transparency, comparability, and accountability to a market expected to grow significantly in the years ahead. The FCA plans to consult on specific rules later this year, with implementation expected to phase in over time.

Why This Matters

Bringing ESG ratings under regulatory oversight could be a turning point for sustainable investing. With consistent standards and greater clarity on how scores are determined, investors can better understand the rationale behind ratings and compare them more effectively. It could also reduce the risk of greenwashing by forcing providers to show their work.

Of course, some concerns remain. Smaller ESG ratings firms may struggle with the cost of compliance. Others worry that regulation could stifle innovation or lead to market consolidation. But broadly, the move has been welcomed by investors and industry groups as a necessary step toward improving trust in ESG data.

As global regulators push for greater alignment, the UK's framework could help shape a more transparent and robust ESG ratings ecosystem - one that better serves both capital markets and long-term sustainability goals.

SESAMm’s AI Technology Reveals ESG Insights

Discover unparalleled insights into ESG controversies, risks, and opportunities across industries. Learn more about how SESAMm can help you analyze millions of private and public companies using AI-powered text analysis tools.

Stay ahead with the latest in ESG and AI intelligence

Join our mailing list to receive new reports, event invites, and updates from SESAMm directly to your inbox.