Summer Roundup: Our 10 Most-Read Blog Posts This Year (So Far)
September 7, 2022
•
5 mins read
Summer is almost over for us in the northern hemisphere. (We know. It's sad for us, too.) And with this seasonal shift comes back-to-school and back-to-work activities, including taking a last-minute vacation. And vacations mean time for reading, right?
While they may not be beach reads, we think we have some great choices. These are the posts that have been most popular on SESAMm's blog in the past five months. Let's get started with SESAMm's most-read blog posts since this spring, starting with number 10.
Read this quick guide about what natural language processing is, how it’s used, why it's important to uncover financial alternative data. Bonus: Get an overview of how NLP works at SESAMm.
Review SESAMm's analysis based on its ready-to-use data streams, revealing red flags that support the decision to oust Tesla, Inc. from the S&P 500 ESG Index.
Watch CEO Sylvain Forté at Japan Investor Forum, discussing ESG data, its challenges, and how to use AI and NLP to generate insights on millions of companies.
See how we apply our NLP capabilities to identify companies likely to engage in greenwashing practices by analyzing text in billions of web-based articles.
Based on alternative data, discover how Elon Musk’s personal and related brands measure up to public sentiment following his failed acquisition of Twitter.
Discover why SESAMm’s data lake is ideal for investment research and other basics like what a data lake is, why it’s important, what it does, and how it works.
Learn how SESAMm’s AI and NLP platform is used to gain financial and ESG insights from alternative data for systematic trading, fundamental research, and more.
Learn what SESAMm’s Knowledge Graph is, what it does, and how it’s used in text analysis for financial research, such as in private equity and hedge funds.
Tokio Marine & Nichido Fire Insurance Company and SESAMm work together to predict stock price movements using NLP-generated data from news and social media.
Thank you for reading through our Summer Roundup: the 10 most-read blog posts this year.
Which is your favorite? How would you rate these posts? Let us know what you think on Twitter or LinkedIn.
In our recent webinar, "The Boeing Scandal: Can AI Predict ESG Controversies?" Sylvain Forté, SESAMm’s CEO and Co-founder, along with Emna Abid, Research and Analytics Team Lead, focused on the important role AI plays in detecting and predicting ESG controversies. They explored how AI provides early warning signals for potential crises, using Boeing’s well-known 737 Max scandal as a central example.
The webinar addressed the challenges businesses face when relying on traditional tools to monitor ESG risks. Traditional methods often struggle to capture early signals, particularly when dealing with unstructured data from local news, NGO reports, or social media. SESAMm’s AI solution overcomes this issue by continuously analyzing vast amounts of data in real time to identify red flags that may not be visible through conventional ESG tools.
Using Boeing’s 737 Max crisis as a case study, the webinar demonstrated how SESAMm's AI Solutions detected early warnings before the controversy escalated. The AI system flagged crucial information from whistleblower reports and localized sources well before the issues became major public scandals.
"ESG factors are no longer just secondary concerns. They are at the forefront of how this industry is perceived by the public, investors, and regulators." Emna Abid - Research & Analytics Team Lead, SESAMm
The webinar also touched on the broader aerospace industry, which has faced heightened scrutiny for its environmental and governance issues. The analysis revealed how AI can help companies in high-risk sectors stay ahead of controversies by providing real-time insights and helping them navigate the complex landscape of ESG compliance and public perception.
To sum up, AI is revolutionizing ESG risk detection, providing companies with the ability to identify early warning signs of potential controversies before they escalate into major crises. By analyzing vast amounts of unstructured data in real time, SESAMm’s AI platform helps organizations navigate complex ESG landscapes, particularly in high-risk industries like aerospace. This proactive approach enables businesses to protect their reputation, make more informed decisions, and ensure compliance with evolving ESG standards.
To explore these insights further, be sure to watch the full webinar replay.
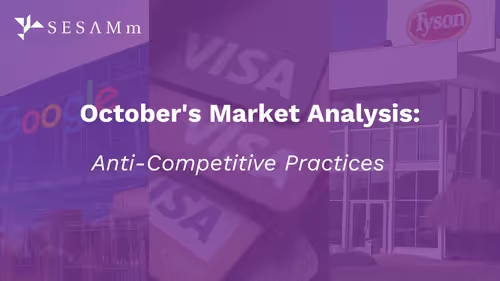
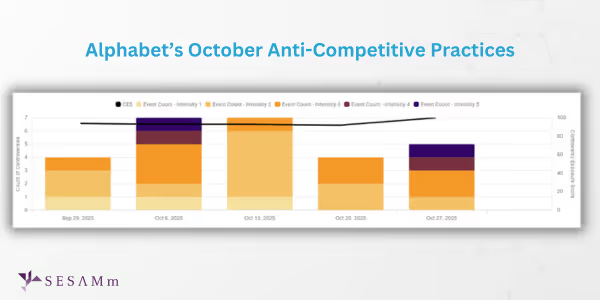
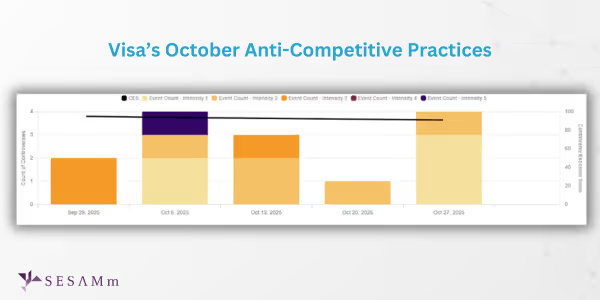
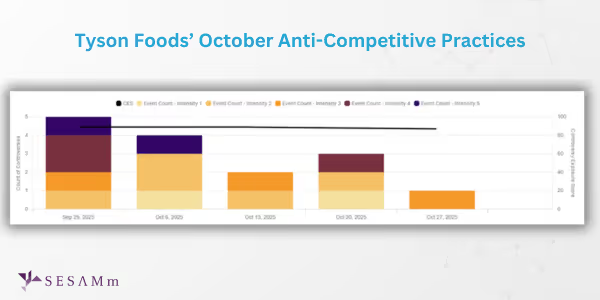
As regulatory scrutiny intensifies across industries, several major corporations faced significant legal challenges related to anti-competitive behavior in October 2025. Using SESAMm's AI-powered controversy data, we analyzed corporate activity to identify the companies most involved in anti-competitive practices during the month. The results reveal a pattern of regulatory action spanning tech giants, financial services, and food production sectors.
#1: Alphabet: Mounting Regulatory Pressure
Alphabet continues to face unprecedented legal challenges across multiple jurisdictions. The company is facing a substantial $8.3 billion lawsuit from Klarna, alleging anti-competitive practices in the Android market. The situation intensified when the U.S. Supreme Court denied Google's request to delay mandated changes that would open Google Play to rival app stores.
Visa continues to face legal and regulatory pressures across multiple jurisdictions. In the United States, the long-running merchant fee antitrust litigation (MDL 1720) remains active, with ongoing appeals and challenges to proposed settlements. Several merchant groups that opted out of earlier agreements have been permitted by the courts to continue pursuing their claims, extending Visa’s legal exposure.
The company's $5.3 billion acquisition of Plaid has drawn intense scrutiny from the U.S. Department of Justice, reflecting growing concern about consolidation in the fintech sector. Meanwhile, across the Atlantic, the UK Competition Appeal Tribunal delivered a landmark ruling against both Visa and Mastercard, determining that their Multilateral Interchange Fees violate competition laws; a significant victory for European merchants and a potential precedent for future cases.
Beyond beef, Tyson reached an even larger $85 million settlement in a separate antitrust case concerning pork price inflation, the largest settlement to date in ongoing litigation against major U.S. meat producers.
Conclusion
The findings from October 2025 underscore a critical moment in corporate regulation, as authorities worldwide demonstrate an increased willingness to challenge anti-competitive practices in sectors ranging from technology and finance to food production. The substantial fines, denied appeals, and ongoing investigations signal a regulatory environment that is actively reshaping market dynamics.
For investors and market observers, these cases highlight the material financial and operational risks associated with anti-competitive behavior. As enforcement mechanisms strengthen and legal precedents solidify, companies across all sectors should anticipate heightened scrutiny of market practices, particularly those involving platform dominance, merger activities, and pricing coordination.
Reach out to SESAMm
TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.
The European Union stands at the forefront of global efforts to promote environmental, social, and governance (ESG) accountability. As the world becomes increasingly ESG-aware, the EU has developed a comprehensive regulatory framework designed to ensure transparency and accountability across all sectors.
These regulations represent the EU's commitment to sustainable development and responsible business practices. However, the regulatory landscape is evolving, with the February 2025 EU Omnibus Proposal introducing potential modifications aimed at reducing the regulatory burden on businesses. However, these proposals come at the risk of substantially undercutting the impact of the regulations.
This article recaps the current ESG regulatory framework in the EU, explores the changes proposed by the Omnibus, analyzes the potential impacts of these modifications, and discusses how financial institutions can navigate this evolving landscape while maintaining compliance.
The ESG Regulatory Landscape in the EU
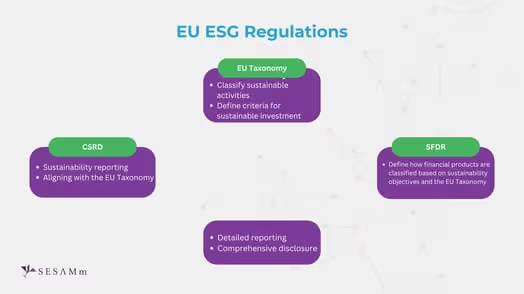
The EU is advancing sustainability through a framework of regulations that enhance corporate accountability and reporting on ESG impacts. These measures aim to promote genuine sustainable practices and address international trade and emissions challenges. Though comprehensive, these regulations are also, at times, confusing in the way they overlap and impact each other. To get started, let’s examine the EU Taxonomy, SFDR, and CSRD—a triad of interconnected regulations designed to streamline and strengthen sustainable investing practices.
EU Taxonomy
The EU Taxonomy provides a classification system for environmentally sustainable economic activities, offering clear criteria to determine whether an economic activity can be considered "green."
Key Aspects of the EU Taxonomy
Defines criteria for environmentally sustainable economic activities
Requires companies subject to CSRD to report on Taxonomy alignment
The Taxonomy helps channel investment toward genuinely sustainable projects and businesses by creating a common language for sustainable activities.
Status
The EU Taxonomy has been operational since January 2022 with phased implementation. As of March 2025, companies subject to CSRD must disclose their taxonomy alignment percentages.
Sustainable Finance Disclosure Regulation (SFDR)
The SFDR focuses specifically on the financial sector, requiring financial market participants to disclose how they integrate ESG risks into their investment decisions and the sustainability impact of their financial products.
Key Aspects of SFDR
Requires disclosure of ESG risks in investment processes
Classifies financial products based on their sustainability characteristics
Aligns with EU Taxonomy criteria for sustainable investments
Aims to prevent greenwashing in financial products
The SFDR plays a crucial role in bringing transparency to the rapidly growing sustainable investment market.
Status
Fully implemented since March 2021, with enhanced Level 2 requirements since January 2023. All EU financial market participants must classify products under Articles 6, 8, or 9. Current market data shows that 28% of EU funds are compliant with Article 8 and 5% with Article 9, with a significant trend of reclassification from Article 9 to 8 due to stricter interpretations.
The CSRD stands as a cornerstone of the EU's ESG regulatory framework, requiring companies to report comprehensively on their environmental, social, and governance impacts. This directive mandates alignment with the EU Taxonomy, ensuring standardized reporting of sustainability metrics.
Key Aspects of CSRD
Requires detailed reporting on ESG impacts
Aligns with EU Taxonomy criteria for sustainability
Currently applies to companies with 250+ employees
Enhances corporate transparency on sustainability issues
The CSRD represents a significant step forward in standardizing sustainability reporting across the EU, providing investors, consumers, and regulators with comparable information on corporate sustainability performance.
Status
The CSRD, adopted in November 2022, replaces the Non-Financial Reporting Directive (NFRD). The transition to CSRD reporting was originally slated to begin in 2025 and would expand the number of companies subject to reporting requirements to 49,000 (vs 11,700 under NFRD). However, as we’ll see later, the Omnibus may push back the timing of CSRD.
Outside of the EU Taxonomy, SFDR, and CSRD, the Omnibus Proposal highlights two other key ESG regulations: CSDDD and CBAM. These regulations relate to corporate accountability for supply chains and to limiting carbon leakage.
Corporate Sustainability Due Diligence Directive (CSDDD)
The CSDDD focuses on corporate accountability throughout global supply chains, requiring companies to identify, prevent, and mitigate human rights and environmental risks associated with their operations.
Key Aspects of CSDDD
Requires companies to identify and mitigate human rights and environmental risks
Applies to full supply chains, ensuring comprehensive oversight
Applies to EU companies with 1,000+ employees and €450 million+ global turnover and non-EU companies with over €450 million EU turnover
Mandates regular monitoring and reporting on due diligence efforts
Strengthens corporate accountability for sustainability across operations
This directive acknowledges that a company's sustainability impact extends beyond its direct operations, encompassing its entire value chain.
Status
CSDDD was adopted in April 2024. Its phased implementation is slated to start in June 2026 and be completed by June 2028. The timing and scope of CSDDD is subject to change following the Omnibus Proposal.
Carbon Border Adjustment Mechanism (CBAM)
The CBAM is an innovative approach to preventing carbon leakage. It levies a carbon tax on imports to ensure that the EU's ambitious climate policies do not simply shift carbon-intensive production outside its borders.
Key Aspects of CBAM
Imposes a carbon tax on imported goods
Requires importers to report emissions data
Ensures payment for embedded carbon costs in imported products
Aims to prevent carbon leakage to regions with weaker climate policies
This mechanism aims to create a level playing field for EU producers subject to carbon pricing while encouraging global partners to implement similar carbon pricing mechanisms.
Status
The transitional phase for CBAM began in October 2023, with full implementation scheduled for January 2026. It currently covers cement, iron and steel, aluminum, fertilizers, electricity, and hydrogen. The certificate requirements will phase in gradually from 30% in 2026 to 100% by 2034. It’s expected to apply to 1.8 million EU importers and generate €5-14 billion in annual revenue when fully implemented.
The February 2025 EU Omnibus Proposal
Purpose and Goals
The EU Omnibus Proposal represents a significant recalibration of the EU's regulatory approach, seeking to balance sustainability ambitions with business competitiveness concerns.
The primary objectives of the Omnibus focus on alleviating regulatory burdens faced by businesses, simplifying compliance requirements, and streamlining reporting obligations. These efforts aim to enhance business competitiveness while addressing regulatory complexity concerns. By minimizing these challenges, the goal is to create a more favorable environment for businesses to thrive. However, this push for simplification could come at the expense of transparency and accountability, especially in sectors where regulation plays a protective role.
Impact Analysis: How the Omnibus Changes ESG Compliance
Below, we’ll take a closer look at each regulation and the changes proposed by the Omnibus Proposal.
EU Taxonomy Modifications and Implications
The Omnibus Proposal suggests a Level 2 modification to the application of the EU Taxonomy, reducing the number of companies required to report taxonomy alignment.
Key Changes:
Taxonomy alignment reporting is limited to companies subject to CSDDD
Voluntary reporting option for companies not required to comply
Possible Implications:
Reduced availability of standardized sustainability data
Increased difficulty in verifying "green" business claims
Higher risk of greenwashing in financial markets
Less reliable information for sustainable investors
These modifications would potentially undermine the Taxonomy's role in creating a common language for sustainable activities.
CSRD Modifications and Implications
The Omnibus Proposal significantly narrows the scope of the CSRD, reducing the number of companies required to report on ESG impacts.
Key Changes:
Threshold increase from 250+ to 1,000+ employees
Optional reporting for SMEs
A two-year delay in reporting obligations for some companies
Possible Implications:
80% reduction in companies required to report
Decreased transparency in corporate sustainability performance
Fewer sustainability data available to investors and regulators
Potential challenges in tracking sustainability progress
These modifications would substantially reduce the regulatory burden on smaller companies but raise concerns about the availability of comprehensive sustainability data.
CSDDD Modifications and Implications
The Omnibus includes significant modifications to CSDDD, with a narrowed scope and reduced monitoring requirements.
Key Changes:
Due diligence is limited to direct suppliers with over 500 employees, not full supply chains
Monitoring frequency reduced from annual to every 5 years
Delayed enforcement for one year for the first batch (Companies with 1.5 billion in turnover and 5000 employees)
Possible Implications:
Weakened corporate accountability for supply chain sustainability
Increased risk of undetected human rights and environmental violations
Reduced monitoring of global supply chain impacts
Extended timeline before full implementation
These changes would significantly reduce companies' compliance burdens but come at the risk of removing the essence of the directive, which is eliminating child labor, forced labor, etc.
SFDR Modifications and Implications
While not directly modified, changes to other regulations, particularly the EU Taxonomy, indirectly affect the SFDR.
Indirect Impacts:
Reduced availability of reliable ESG data
Challenges in differentiating truly sustainable investments
Potential increase in greenwashing risk
These indirect effects could undermine the SFDR's effectiveness in bringing transparency to sustainable investment products.
CBAM Modifications and Implications
The Omnibus Proposal simplifies CBAM compliance, particularly for smaller importers.
Key Changes:
Small importers (under 50 metric tons/year) are exempted
Reduced reporting burden for over 182,000 businesses
Possible Implications:
Simplified compliance for small businesses
Potential loophole risk if companies split shipments to stay under the threshold
Maintained coverage of 99% of emissions despite exemptions
These modifications would maintain the CBAM's effectiveness while reducing the administrative burden on smaller importers.
The Debate: Perspectives on the Omnibus Proposal
Arguments in Favor
Proponents of the Omnibus Proposal emphasize its benefits for business competitiveness and regulatory efficiency. They highlight the reduced administrative burden, especially for small and medium-sized enterprises (SMEs), which often struggle with complex regulations. Additionally, the changes aim to simplify compliance requirements, making it easier for businesses to adhere to regulations. By aligning with global standards, the proposal helps maintain the EU's economic competitiveness while promoting a more efficient allocation of resources across industries. Together, these factors create a more streamlined and supportive environment for businesses to thrive.
As BusinessEurope Director General Markus J. Beyrer stated: "Doing better with fewer and clearer norms is what European companies of all sizes are asking for. By reducing unnecessary reporting and regulatory burdens, the first Omnibus will allow companies to contribute more effectively to the EU's sustainability objectives while also preserving the EU economy's competitiveness."
European Commission President Ursula von der Leyen also expressed support for the proposal, stating: "EU companies will benefit from streamlined rules. This will make life easier for our businesses while ensuring we stay firmly on course toward our decarbonization goals."
Criticisms and Concerns
Critics raise significant concerns about the potential undermining of the EU's sustainability ambitions. They argue that the Omnibus Proposal may lead to unintended consequences, including reduced transparency in corporate sustainability performance, weakened supply chain accountability, and regulatory uncertainty during transition periods. Additionally, it could undermine sustainability objectives and increase the risk of greenwashing. As Mariana Ferreira from WWF European Policy Office commented:
"The Commission's sudden urge to destroy laws that are crucial for the achievement of the EU Green Deal is a perilous approach that is forcing Europe into a time of regulatory uncertainty. Under the guise of 'simplification,' the Commission put forward a proposal that will hinder economic and business success."
"The Omnibus proposal erodes EU's corporate accountability commitments and slashes human rights and environmental protections."
While the European Parliament debates the Omnibus Proposal, the fact remains that even if the regulations are delayed or loosened, the need for risk management remains unchanged. Investors require transparency, and companies must manage supplier risk effectively.
Navigating ESG Risks with SESAMm
SESAMm’s cutting-edge AI solutions empower investors, financial institutions, and corporations to navigate the complexities of ESG compliance with confidence. Leveraging an industry-leading data lake and state-of-the-art AI, SESAMm uncovers hidden risks in supply chains and target companies, providing real-time insights that drive proactive decision-making. By transforming regulatory challenges into opportunities for responsible and sustainable growth, SESAMm helps businesses stay ahead of evolving ESG requirements while mitigating risk and enhancing transparency.
SESAMm’s AI Technology Reveals ESG Insights
Discover unparalleled insights into ESG controversies, risks, and opportunities across industries. Learn more about how SESAMm can help you analyze millions of private and public companies using AI-powered text analysis tools.
Stay ahead with the latest in ESG and AI intelligence
Join our mailing list to receive new reports, event invites, and updates from SESAMm directly to your inbox.