
Insights & Updates

Blog thumbnail

Hydropower's ESG Paradox: Why the "Green" Asset Class Tops the Controversy Charts

August 20, 2026
5 mins read
Hydropower tops ESG controversy volume across 250,000+ projects, outranking coal. Why the greenest label in energy hides the heaviest social risk.

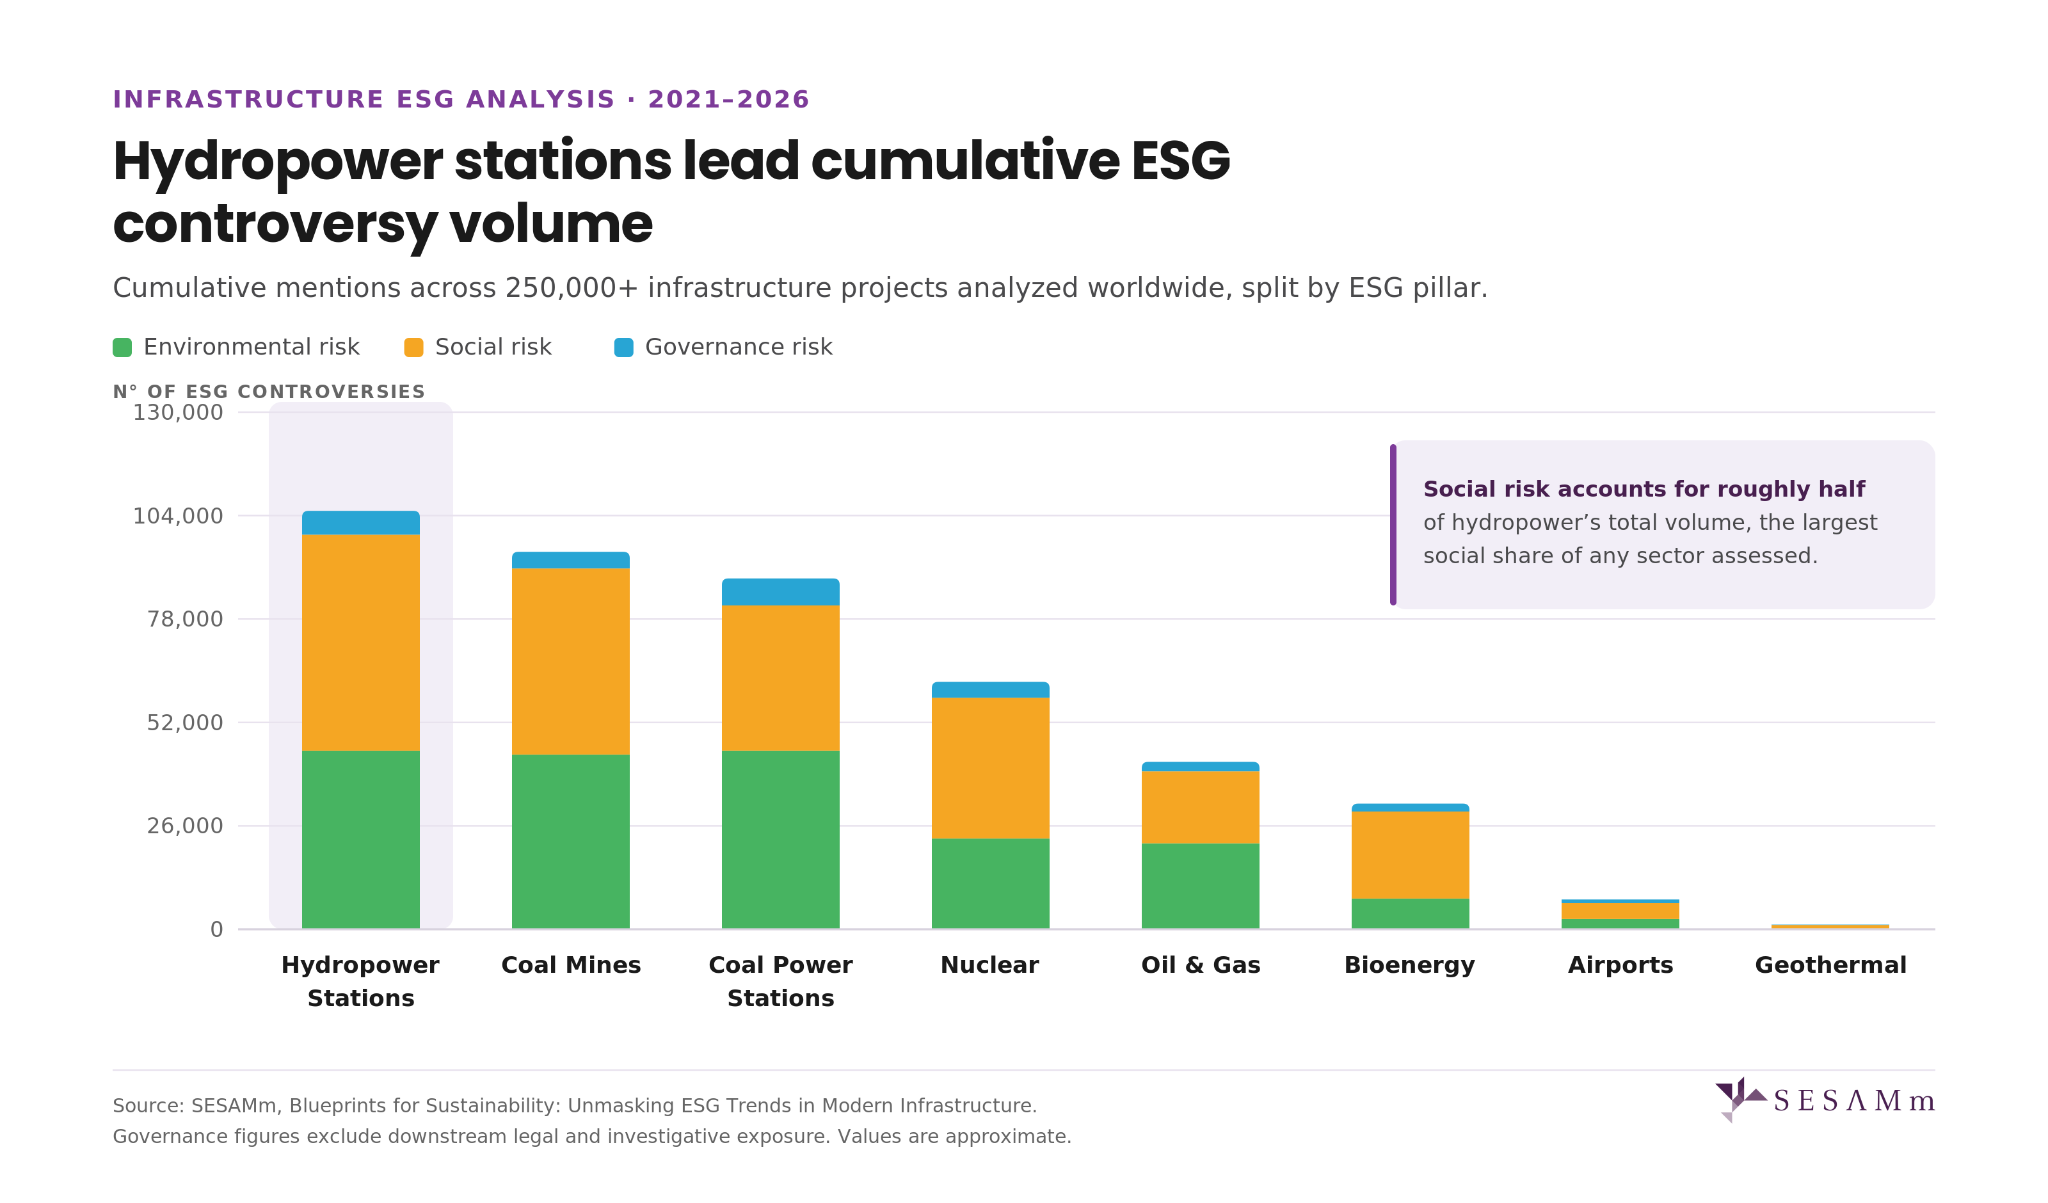
An analysis of over 250,000 infrastructure projects reveals that the sector most often filed under "clean energy" carries the heaviest environmental and social controversy footprint of any asset type assessed.

In the taxonomy of energy infrastructure, hydropower occupies a comfortable position. It is renewable, dispatchable, and long-lived, and it enters transition frameworks, green bond eligibility criteria, and net-zero roadmaps with minimal friction. Where coal is a legacy liability to be managed down and nuclear invites a specialized debate, hydropower is largely treated as settled. What these projects have actually done does not support that treatment.
Belo Monte, an 11,233 MW complex on the Xingu River in Pará, Brazil, is the sharpest test of the point, because it was built to answer this exact objection. Approved after decades of opposition to a far larger design, it was engineered as a run-of-river plant to minimize flooding, and its reservoirs cover 478 km², of which 274 km² was already river channel at high water, a 61% reduction compared with the 1980s proposal, according to the operator's own regulatory filing. The mitigation was designed from the start, and everything that follows happened regardless.

Biodiversity: the cost of a physical footprint

Environmental controversy across infrastructure concentrates on industrial accidents, water pollution, and biodiversity, and hydropower leads the third, outright, because dams require the permanent conversion of river systems and the land around them. Mexico's Federal Electricity Commission won environmental approval in September 2014 for the Las Cruces dam on the San Pedro Mezquital, upstream of Marismas Nacionales, a Ramsar-protected wetland, even though the project's own impact statement conceded that the damage to Indigenous ceremonial sites could not be mitigated. Along the Mekong River, river health and fish populations fell as dam construction spread through the basin. In Brazil, the Doce River carried a mass release of toxic material after an upstream failure. Elsewhere, the record includes violations of the Endangered Species Act and documented disruption to rainfall patterns.

At Belo Monte, the consequences have been measured rather than projected. The plant diverts water into a canal that bypasses a 130-kilometer stretch of the Xingu known as the Volta Grande, which has received less than 30% of its natural annual discharge since 2019, and some 86% of the stretch's seasonally flooded vegetation, 30,748 of 35,600 hectares, can no longer be inundated at all. The gap lies in the regulator's own file: IBAMA's technical staff called for 10,900 cubic meters per second in February, the historic peak month, compared with the 1,600 that the operating regime actually releases. Seven years of underwater video survey data published in Scientific Reports recorded total fish species richness falling from 62 to a post-operation average of 51, with the steepest losses near the dam and in the rocky rapids, which hold roughly 2.6 times as many species as sandy reaches. The zebra pleco, whose entire known range lies inside the dewatered stretch, now sits on Brazil's national list of threatened species as critically endangered.

None of this is an accident or a failure of operation. It is a structural consequence of the asset. A well-run dam still floods a valley, and a dam engineered specifically not to flood one still dewater the river below it.

When engineering fails: hydropower's physical risk profile

Coal mining leads infrastructure on industrial accidents, where the record is dominated by human tragedy and safety negligence: explosions, collapses, fires, and repeated, incremental failures. Hydropower ranks second, but its accidents take a different form, because in this sector, industrial failure means catastrophic engineering failure at scale. The record includes pipe ruptures causing severe land erosion, oil leaks, and dam collapses that killed and displaced people across whole regions, while PG&E's settlement over damages to the Middle Fork American River Hydroelectric Project and the litigation still running in Brazil after dam collapses give a sense of the exposure a single event can generate. For anyone underwriting these assets, the distinction is financial as much as physical: a coal mine's safety record is a rising cost curve, while a dam's structural integrity is a low-probability, near-unbounded loss.

At Belo Monte, that exposure has so far been financial. The project was budgeted at R$28.9 billion when Brazil's development bank approved a then-record R$22.5 billion loan in November 2012, and by late 2017, actual investment had reached R$38.6 billion, roughly 34% over. The operator owed R$28.3 billion to lenders and debenture holders at the end of 2024. Aliança Norte Energia Participações, the Vale and Cemig vehicle holding a stake in the project, discloses a possible loss of R$3.05 billion from a single construction-delay claim and describes the operator's liquidity as its principal point of attention and a source of investor alert. Neoenergia wrote off its own 10% holding by R$482 million in the fourth quarter of 2021.

The physical risk has been closer than the absence of a collapse suggests. In October 2019, the operator wrote to the national water regulator declaring an emergency, because reservoir levels had fallen far enough to expose an unprotected section of the Pimental dam's earthfill base to wind-driven wave erosion and, in the company's own words, structural damage. It cut outflow below the level agreed with the environmental regulator to protect the structure, and the letter surfaced only through investigative reporting.

Beyond the environment: displacement, water, and chronic corruption

Right to property

Hydropower ranks first among infrastructure sectors for property disputes, a direct function of the footprint a dam and reservoir require. The record shows land seizures, forced displacement, compensation that arrives short or not at all, communities never consulted before ground was broken, and blasting that cracked the foundations of nearby homes. Those affected are frequently the least equipped to hold an operator to account.

Fifteen years after Belo Monte broke ground there is still no audited count of who lost their homes. Estimates run from 20,000 to 40,000 depending on the definition used, against the operator's account of rehousing some 6,000 urban families. Landowners say expropriations are priced at unadjusted 2013 values while the project's own construction boom inflated the market, and as of 2025 none of the land required for the riverine resettlement program had been bought. A petition filed with the Inter-American Commission in 2011 still has no ruling.

Community health and safety

Hydropower sits alongside coal and nuclear as a leading source of community health disputes, but it arrives by a different route. Coal delivers PM2.5, nuclear delivers radioactive anxiety, and hydropower delivers water mismanagement: overconsumption that strips farmers of a livelihood, contaminated water reaching local crops. The grievance is agricultural rather than industrial, which widens the affected population considerably.

On the Volta Grande, catch per fisher fell from 11.1 kilograms a day between 2001 and 2008 to 4.53 kilograms between 2020 and 2023. A randomized household survey found 38.5% of residents in Belo Monte's resettlement neighborhoods living with moderate or severe food insecurity, against 28.3% across the surrounding city. In June 2026, federal prosecutors sought as interim relief for 635 families along the reduced-flow stretch the emergency delivery of three and a half to five liters of drinking water per person per day.

Corruption and bribery

Corruption and bribery accounts for close to 30% of governance controversy across infrastructure. What separates hydropower is the pattern. In airports, nuclear, and coal, corruption surfaces as discrete scandals: a probe opens, executives are charged, attention fades. In hydropower it keeps returning, tied repeatedly to falsified records and payments to local officials to secure land and water rights. Isolated scandals point to isolated actors. A pattern that recurs points to how these projects get permitted.

Brazilian prosecutors alleged that Belo Monte's construction contracts carried bribes worth 1% of their value, and three contractors admitted cartel conduct and kickbacks under leniency agreements that carried immunity. Everything after that was procedural closure rather than a finding of liability: the principal defendants were acquitted and the acquittal upheld on appeal in 2024, the competition authority archived its bid-rigging case in 2025, and no individual has been convicted in connection with the project. An investor screening for enforcement outcomes would have found a closed file. The costs landed elsewhere, in permitting delay, financing conditions, and a minority stake that has been for sale since 2022 without a buyer.

Hydropower's risk concentration: what this means

Hydropower's classification as clean energy is accurate on the metric it was designed to measure, because generation is low-carbon. But carbon intensity is one dimension of sustainability, and it is not the dimension that produces operational friction, legal exposure, or the loss of a social license.

What drew sustained opposition to these projects was water rights, displaced communities, cracked foundations, converted wetlands, and permits secured through local payments. None of it appears in a carbon accounting framework.

For investors, insurers, and lenders seeking transition-aligned infrastructure exposure, that is a material blind spot: an asset class that screens well on the primary criterion while carrying the heaviest social burden in the dataset, and carrying it on behalf of people who have no employment relationship with it. Belo Monte was engineered to avoid precisely that outcome and produced it regardless, which suggests the exposure is not a function of how a dam is built but of what a dam is.

The label is not wrong. It is simply measuring something other than risk.

Read More

With sustainability being imperative, it's essential to examine how public and private companies align with the Sustainable Development Goals (SDGs). This article, leveraging insights from SESAMm's TextReveal, dives into the behaviors of both sectors across industries, exploring their impact on achieving a sustainable future. Join us as we unravel the complexities of corporate contributions to the SDGs, highlighting key differences and challenges public and private entities face in their journey toward sustainability.

What are the 17 Sustainable Development Goals?

The 17 UN SDG objectives, introduced in 2015 with the target of achievement by 2030, are geared towards building a sustainable society. Initially designed for governments, certain companies can contribute significantly to these goals through their products or conduct. However, our focus here will center on identifying behaviors that counter these 17 objectives.

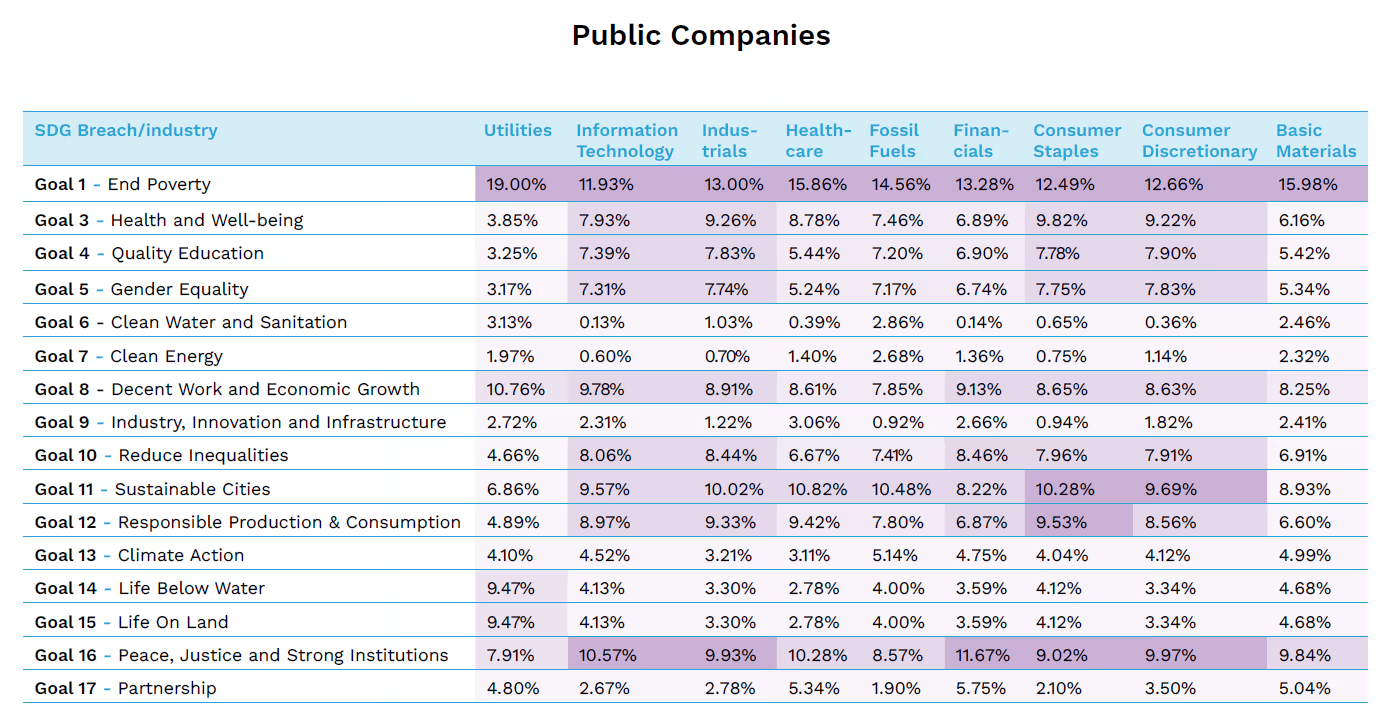
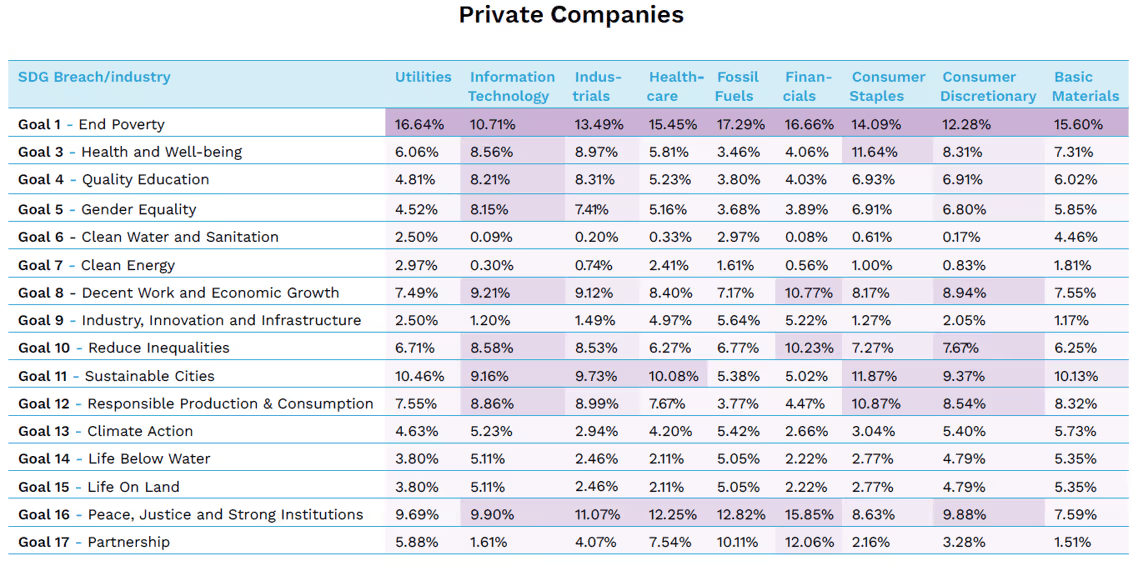
The analysis of Sustainable Development Goal (SDG) adverse behaviors, as identified by SESAMm's TextReveal, offers a comprehensive comparison between public and private companies within various industries. The focus is to discern disparities in SDG behaviors within the same sector and pinpoint the predominant SDG goal breaches in these industries.

Excluding Goal 2 ("End hunger") due to its alignment with state-related initiatives, the analysis concentrates on corporate-impactful goals.

Public and private sectors face challenges in meeting SDGs, particularly Goals 1 ("End poverty") and 16 ("Peace & justice and strong institutions"), with issues in labor rights and governance. However, public companies are more aligned with Goal 8 ("Decent work and economic growth") across industries, facing a range of controversies from biodiversity to management issues. In contrast, private companies focus on Goal 11 ("Sustainable cities"), dealing with climate change and customer relations risks.

Both sectors show high breaches in Goal 1 ("End poverty"), indicating widespread controversies related to labor rights, human capital, and governance-related pay issues, spanning senior board compensation, tax strategies, and potential anti-competitive practices.

Goal 16 ("Peace & justice and strong institutions") is significant in both sectors but particularly in the Financials and Information Technology for public companies and in Financials, Fossil Fuels, and Health Care for private companies. This goal involves human rights, labor rights, human capital, and governance-related controversies.

Sector-Specific Trends

Public Companies

Goal 8 ("Decent work and economic growth") is prominent across all industries, especially in Utilities. The range of controversies includes biodiversity, human rights, labor rights, human capital, supply chain social management, and governance issues like senior management structures and anti-competitive practices.

Private Companies

Goal 11 ("Sustainable cities") is notably significant in Consumer Staples and Utilities. Risks are primarily associated with climate change, atmospheric pollution, waste management, fundamental human rights, human capital, customer relations, anti-competitive practices, and influence strategy and communication.

These findings highlight the profound impact of SDG-related risks on economic growth and stability across various sectors. Industries like Information Technology, Industrials, and Consumer Discretionary exhibit heightened susceptibility to SDG adverse behaviors, underscoring the necessity for vigilant risk management to ensure economic prosperity and security.

Industrial UNGC Use Case

What is the UN Global Compact?

The United Nations Global Compact (UNGC), established in 2000, outlines ten principles across four main pillars: human rights, labor standards, and anti-corruption. These principles are critical in guiding companies toward ethical and responsible behaviors.

UNGC public companies-1
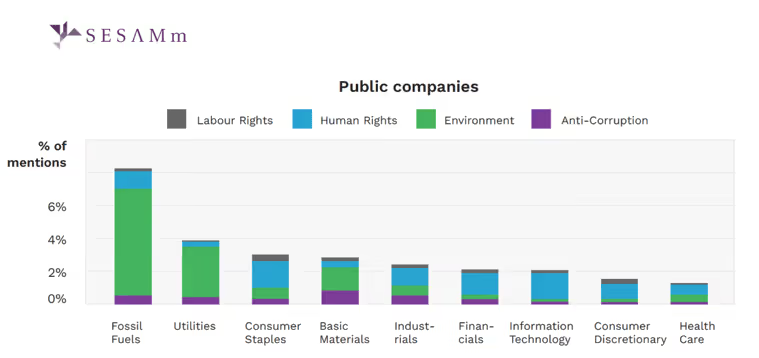
Figure 1: UNGC for public companies.
UNGC private companies
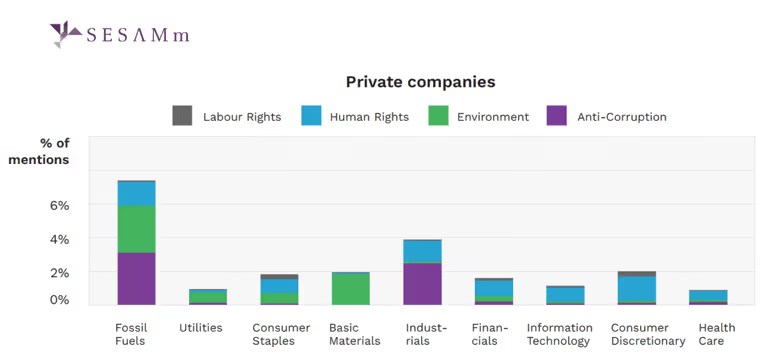
Figure 2: UNGC for private companies.

The analysis reveals distinct patterns in breaches of UNGC principles. Private companies in the industrials and fossil fuel sectors show a notable correlation with anti-corruption breaches, emphasizing the importance of due diligence in these areas. In the fossil fuel industry, public companies primarily breach environmental principles, while private companies show more breaches related to anti-corruption along with environmental concerns.

Public utilities companies exhibit more environmental breaches, including issues like gas leaks and unauthorized discharges. In contrast, private companies in the basic materials sector experience more environmental breaches, marked by incidents such as plant explosions and non-compliance with environmental regulations. Public companies in this sector, however, tend to have more anti-corruption breaches.

Private industrial companies also display a significant number of anti-corruption breaches involving various legal challenges. In the consumer staples sector, public companies primarily face human rights breaches, including forced labor and privacy violations. The private consumer discretionary sector also shows a high number of human rights breaches, particularly related to privacy and diversity and inclusion.

Overall, public companies across various sectors tend to have more frequent or severe UNGC breaches compared to private companies. This highlights the different challenges faced by public and private entities in adhering to the UNGC principles.

Conclusion

Significant variations in sustainability strategies emerge when looking at public and private companies through their SDG performances. Public companies prioritize economic growth and grapple with environmental and governance concerns, while private companies focus on creating sustainable cities, addressing climate change, and fulfilling social responsibilities. Both sectors encounter obstacles in eradicating poverty and ensuring justice, highlighting their crucial roles in promoting global sustainability objectives. This analysis underscores the essential proactive approach needed from both public and private entities to tackle sustainability challenges effectively.

Download the full report to discover how different sectors navigate regulatory pressures and sustainability challenges with real-world examples to guide your strategy.

Reach out to SESAMm

TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.

Public companies, due to their large market presence and mandatory financial disclosures, often receive a lot of attention on the Internet. Their operations and regulatory obligations put them under a media spotlight, which amplifies any ESG controversies they face in public and online discussions. In contrast, private companies operate with a higher degree of discretion and are generally less exposed to intense external scrutiny.

Although private companies are less visible to the public, there is still an underlying interest and, more importantly, a need to understand the nature of ESG controversies they face. Are these controversies different in any way, such as being less significant or having unique characteristics? This raises questions about whether certain types of risks are more susceptible to controversies in the private sector. When comparing prominent public companies with their private counterparts, do controversies differ within the same industry?

ESG Overview

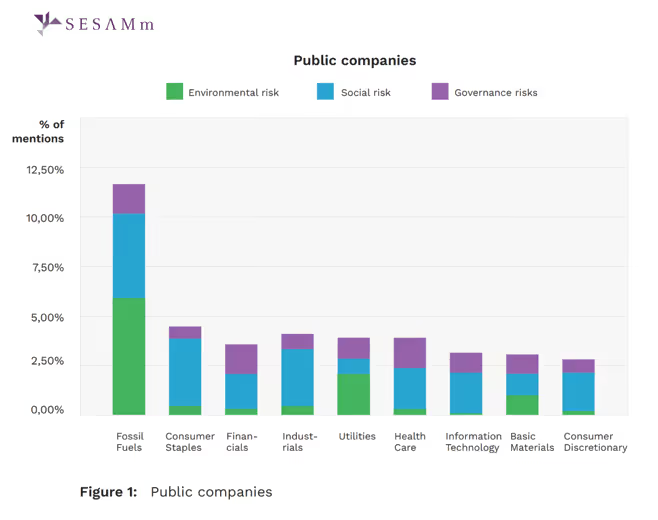
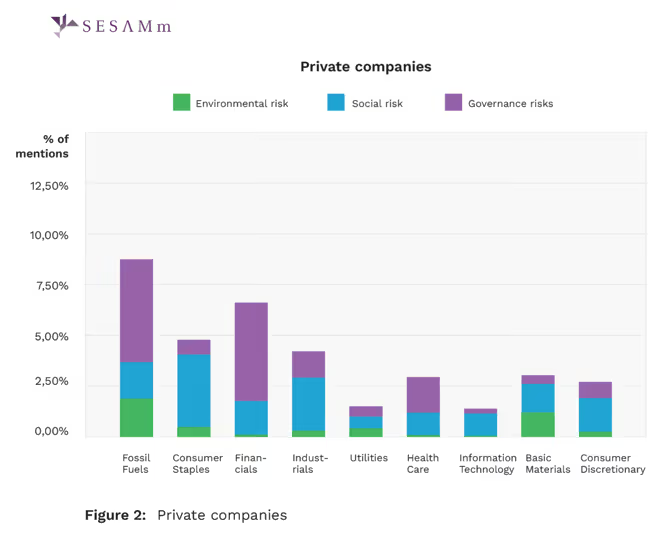
In exploring the ESG landscape, a compelling comparison emerges between private and public companies. Public companies predominantly grapple with environmental and social risks. On the other hand, private companies, especially in the financial sector, are more frequently embroiled in governance-related controversies. This section highlights the ESG challenges each sector faces and the varying degrees of visibility and scrutiny these issues receive in the public and private domains.

ESG public companies-2

ESG private companies-2

Within the fossil fuel industry, a distinct difference emerges: public companies are predominantly associated with environmental and social risks, while private companies face more governance-related issues.

This disparity is partly due to the more visible and significant environmental impacts often linked to public companies, such as BP's gasoline spill cleanup in Washington state and the devastating impacts of Shell's oil spills in Nigeria. Public companies also tend to experience more social issues, like employee strikes, protests, and human rights infringements.

In contrast, private companies, particularly in the financial sector, show a higher frequency of governance risks. Examples include controversies surrounding FTX and Binance, highlighting issues like corruption, substantial fines, and money laundering allegations. This trend mirrors the earlier observation in the fossil fuel sector, where private companies, despite fewer controversies, experience more pronounced impacts when significant ESG issues arise.

It's noteworthy that private sector controversies, due to their relatively lower level of scrutiny, can gain significant traction and visibility when they do surface. This differs from the public sector, where the constant exposure to ESG risks leads to more frequent detection but not necessarily the same level of virality for each event. Public companies regularly encounter ESG risks, but the prevalence of such issues in their operations means that individual events may not always attain widespread attention.

ESG Deep-dive

Environmental risks deep-dive

Looking at environmental risks, public companies often face significant issues like emissions, climate change, and water pollution, while private firms encounter these challenges on a smaller scale and with different focuses, such as animal cruelty and environmental strategy.

E subrisks public companies-1

E subrisks private companies-1

In the Consumer Discretionary sector, both types of companies encounter environmental risks, but the nature of these risks differs. Public companies, particularly in the automotive industry, are often involved in incidents like fires and lawsuits related to harmful emissions. Private companies, while also dealing with fires and automotive issues, face additional problems like animal cruelty allegations in retail.

The Fossil Fuel sector shows a clear distinction in ESG issues. Public companies frequently face controversies related to climate change and atmospheric pollution, often involved in significant incidents like legal actions and fines. Private companies, on the other hand, are more focused on general environmental strategy, though their controversies tend to be of a smaller scale.

In Utilities, public companies are more involved in water pollution controversies, with significant incidents like fines for unlawful water extraction making headlines. Private companies, while also dealing with water pollution, do so less frequently and on a smaller scale.

The Financial sector reveals that public companies, especially banks and financial services, are closely linked to the fossil fuel industry. This association has led to various controversies, including greenwashing accusations and involvement in ESG probes.

The Healthcare sector, particularly in public companies, shows a focus on biodiversity-related controversies. Issues like animal cruelty in biotechnology are prominent.

Overall, public companies tend to be at the center of more significant and high-profile environmental controversies, particularly in sectors like fossil fuels, utilities, and financials. Private companies, while also facing environmental and ethical challenges, often do so on a different scale, indicating different approaches and impacts in their management.

Social risks deep-dive

Public companies across sectors like Consumer Discretionary, IT, Financials, and Fossil Fuels frequently confront a broad spectrum of social risks, including human rights breaches and human capital concerns. Private companies, while also facing these issues, tend to have a more focused approach, with specific concerns in areas like telecommunications, social media, and health & safety. This indicates differing strategies and impacts on their social management.

S subrisks public companies-1

S subrisks private companies-1

Public companies in the Consumer Discretionary sector struggle with a substantial volume of data related to human rights breaches and human capital issues. These challenges are widespread across various industries, with incidents in telecommunications, social media, and the automobile industry being particularly noteworthy. In contrast, private companies in this sector primarily confront human rights breaches, with a significant focus on issues within telecommunications and social media. This contrast indicates a more specialized concern for private companies in this sector.

Both public and private companies in the Information Technology sector experience significant risks related to fundamental human rights breaches and human capital concerns. However, public companies, particularly those in software and hardware, are more frequently linked to these issues. Private companies, while also implicated, tend to have a different focus within the same concerns.

In the Financial world, public companies exhibit a pronounced focus on human capital issues, surpassing their private counterparts. This focus spans the banking and insurance industries with notable instances of discriminatory dismissals and wage disputes. Additionally, public companies in this sector also navigate complexities related to human rights and customer relations, including racial discrimination lawsuits and data breaches. Conversely, private financial companies face significant customer relations issues, especially highlighted in financial services, and human rights concerns, such as charges against Binance for child pornography and terrorism financing.

Private companies in the Consumer Staples sector lead in mentions related to health and safety, particularly in the Food/Beverage and tobacco manufacturing industry. These references often involve serious incidents like industrial accidents and lapses in COVID protocols. Additionally, customer relations issues are slightly more pronounced in private companies compared to their public counterparts. Public companies, meanwhile, have a slightly higher proportion of mentions related to human rights risks, including labor law violations and privacy concerns.

Public companies in the Fossil Fuel sector are notable for their focus on human capital issues, with references to industry-wide strikes and layoffs. In contrast, private companies in this sector demonstrate a significant focus on human rights issues, as exemplified by the case of the ex-Citgo CEO.

A divergence is seen in the Basic Materials sector, where private companies face more prevalent human capital issues, particularly in mining & metals and the chemical industry. Public companies, on the other hand, encounter a higher proportion of human rights breaches, including harassment lawsuits and violations of indigenous rights.

In summary, public companies across these sectors tend to face a wider range of social controversies, encompassing both human rights and human capital issues, often on a larger and more varied scale. Private companies, while also dealing with similar challenges, tend to do so with a more specific focus, suggesting different approaches and impacts in their social management strategies.

Governance risks deep-dive

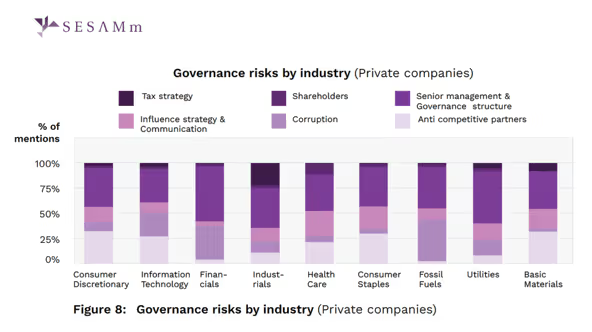
In scrutinizing governance, we found that public firms face risks in management and governance, while private entities encounter issues like anti-competitive practices and corruption. Financial and Industrial sectors see public companies dealing with strategy and compliance challenges, whereas private firms face tax strategy risks. Overall, public companies are more involved in high-profile governance controversies, while private companies focus on specific areas like tax and anti-competitive behavior.

G subrisks public companies-1

G subrisks private companies-1

In the Consumer Discretionary sector, governance issues vary notably between public and private entities. Public companies, particularly in telecommunications and Social Media, encounter significant risks in senior management and governance structures, evidenced by legal actions and allegations against companies like Verizon and Ericsson. Conversely, private companies in Media & Entertainment are more embroiled in anti-competitive practices, as highlighted by Epic Games' antitrust trial against Google.

Information Technology presents a clear distinction. Private companies are frequently linked to substantial corruption issues, with the FTX scandal serving as a prime example. Public companies, on the other hand, are more inclined towards engaging in anti-competitive practices, as seen in the cases of technology giants like Google and Microsoft facing antitrust lawsuits and scrutiny for monopolistic behavior.

In the Financials sector, governance risks are predominantly tied to senior management and corporate structure. Public companies face challenges primarily in their influence on strategy and communication, with notable instances including BlackRock's lawsuit over an alleged misleading ESG strategy. Meanwhile, prominent financial services companies like PayPal have faced regulatory scrutiny, further illustrating the sector's vulnerabilities.

The Industrials sector shows similar trends among public and private companies but with a specific emphasis on tax strategy risks in private firms. This is exemplified by the PwC tax leaks scandal, indicating the deep impact of governance issues in private entities.

In the Fossil Fuels sector, corruption issues are more pronounced, especially among privately-held companies. Incidents such as the lawsuit against Citgo and the Amec bribery case settlement underscore the sector's susceptibility to governance-related controversies.

Lastly, the Utilities sector shows a higher prevalence of corruption among public companies, as demonstrated by the investigation into FirstEnergy's public corruption scandal and subsequent legal actions.

Overall, governance risks manifest differently in public and private companies across various sectors. Public companies are often at the forefront of high-profile governance controversies, dealing with issues related to management, strategy, and regulatory compliance. Private companies, while also grappling with governance challenges, tend to face issues like anti-competitive practices and tax strategy risks, reflecting a variance in operational focus and impact on governance risk management.

Conclusion

By diving into the complexities of ESG, both public and private sectors have a unique opportunity not only to enhance their financial performance but also to drive positive societal and environmental impacts. As we further examine corporate controversies and gain a deeper understanding of the nuances within the ESG landscape, it becomes increasingly clear that a commitment to these principles is essential for long-term success and global well-being. Our journey highlights the tremendous potential for positive change when corporations embrace the pressing demands of today's ESG landscape, paving the way for a more sustainable, equitable, and governance-focused world.

Download the full report to discover how different sectors navigate regulatory pressures and sustainability challenges with real-world examples to guide your strategy.

Reach out to SESAMm

TextReveal’s web data analysis of over five million public and private companies is essential for keeping tabs on ESG investment risks. To learn more about how you can analyze web data or to request a demo, reach out to one of our representatives.

As SESAMm commemorates its 10th anniversary, we take a moment to reflect on a decade marked by significant achievements and invaluable lessons. This journey from a nascent startup to a leader in AI-powered ESG analytics has been both challenging and exhilarating. Through this walkthrough, I aim to share the pivotal milestones that have defined our path, the wisdom we have accrued, and the exciting prospects that lie ahead. These reflections not only encapsulate our past and present but also pave the way for the innovative strides we are poised to make in the future.

A Decade of Innovation and Growth: SESAMm’s 10 Key Milestones

As we celebrate SESAMm's 10th anniversary, I find it humbling and inspiring to reflect on our incredible journey. From our earliest days to our success, each milestone has shaped who we are today. Here’s a personal reflection on the ten key milestones defining our journey.

  1. The Beginning - Winning the SEMIA Prize (2013): Everything started when we received the SEMIA entrepreneurship prize, supported by Société Générale with €10,000. This funding was crucial—it transformed our project from an academic idea into a viable business venture, marking our first serious step towards entrepreneurship.
  2. Forming the Company (April 2014): The decision to officially form SESAMm as a company and my transition to CEO brought both excitement and a profound sense of responsibility. It was a commitment not just to our ideas but to leading a team towards realizing them. There’s a funny anecdote that happened during this period. I was still at school but had to do an internship to finish my studies, so I did it at SESAMm while being the CEO. So I was the CEO and an intern at the same time!
  3. Securing Our First Client (Late 2015): Convincing a London trading firm to start using our products for actual trading activities was our first major market validation. This not only helped us fund our initial operations but also boosted our confidence in the potential of our technology. It helped us onboard other clients in the months thereafter.
  4. Moving and Expanding (November 2015): This period was marked by significant changes, including a successful fundraising effort and relocating our headquarters to Metz. These moves were essential for scaling our operations and preparing for future growth.
  5. Expanding Our Team (Early 2016): Hiring our first dedicated researchers in AI and finance was a key development that enhanced our capabilities dramatically. This expansion allowed us to accelerate our technology development and better serve our clients. It also helped us open our first office in Paris, which allowed us to bring the right talent to continue our development.
  6. Seed Funding Round (2017): Raising €2.6 million in seed funding was a milestone that endorsed our market presence and bolstered our financial stability. We got the opportunity to work with major European asset managers and banks, allowing us to pursue broader objectives and refine our technological offerings.
  7. International Expansion (2019): The expansion into New York and Tunisia was not just a geographical growth but also a strategic pivot focusing on the US, an ambitious plan to tackle the biggest market in the world. We also saw an opportunity to help more firms by incorporating ESG indicators into our services, reflecting our commitment to sustainability.
  8. Establishing in Tokyo (2021): Opening an office in Tokyo was a strategic move to capture opportunities in the Asian markets and broaden our international footprint, which has been instrumental in our global strategy.
  9. Series A Round (2021): The €7.5 million raised from entities like Carlyle and New Alpha was key in scaling our operations and enhancing our credibility in the fintech space globally. Although the fundraising part was critical, it also came with our first major private equity client in the US, Carlyle. That was a big validation in the market which increased our credibility with other firms in the space, leading us to work with the top 7 private equity companies.
  10. A New Phase of Growth (2023): Closing a €35 million funding round was a testament to our growth and the trust investors have in our vision. This milestone coincided with another big one, hiring our 100th employee. The company cemented its position as a leader in ESG AI-powered insights.

“These last ten years have given us the opportunity to grow from a small team to a community ready to tackle any challenge. We learned together the importance of building a product that addresses market needs and prioritizes companies' responsibility for a better future.”

Florian Aubry, CTO & cofounder.

Top Ten Lessons Learned in Ten Years

Here's a reflection on the key insights that have guided our growth and innovation.

  1. Be Ambitious: The journey of SESAMm taught us the power of ambition, and not the voracious kind, but a realistic yet big and aspirational one. Inspired by Sam Altman's advice, "Ask for what you want," we learned early on that setting high goals helps achieve them. Whether it was funding rounds or product development, a clear vision and bold aspirations were crucial.
  2. Be Nice: Contrary to traditional aggressive management styles, we embraced kindness as a core value. This approach has not only improved our internal culture but also helped us build lasting relationships with partners and clients.
  3. Stay Focused: Our focus has matured from developing a technology platform to progressively gaining the necessary laser focus on product market fit. This singular focus has been instrumental in navigating the complexities of the tech and financial markets, with a focus on enhancing our ESG insights that assist our clients in making the right decisions.
  4. Trust People: At SESAMm, we believe in trusting our team by default. This trust has empowered our employees, fostered innovation, and driven our company forward. It’s about giving people ownership and believing in their capacity to succeed.
  5. Client-Centric Approach: We prioritize exceptional customer service and cherish every client relationship. Our goal is to solve real problems and ensure that clients speak highly of us, even if our paths diverge.
  6. Preserve Co-Founder Relationships: We've seen how disputes among founders can derail startups. At SESAMm, we make decisions collectively, emphasizing harmony and shared goals over individual agendas. 10 years later, our founding team is as strong and tight as ever.
  7. Respect Your Investors: Our investors are not just funders; they are partners in our journey. Acknowledging their role and integrating their insights into our decision-making process has been vital for our growth.
  8. Play the Long Game: Success in the startup world is not overnight. It takes perseverance and a long-term perspective to build a lasting enterprise. We emphasize sustainable growth and well-being over quick gains.
  9. Enjoy the Journey: Amidst the hustle, it’s important to enjoy the process. At SESAMm, we aim to cherish every moment - whether it’s a breakthrough in a project or a casual team outing. These experiences enrich our work and lives.
  10. Understand the Technology: As a tech-driven company, maintaining a deep understanding of our technology as founders - particularly AI - is fundamental. This ensures we can innovate effectively and make informed decisions.

Reflecting on these lessons as we look forward to the next decade, we are reminded of how far we've come and how these principles will continue to guide us.

“With a blend of humility and passion, we have boldly pursued our vision, guided by our hearts and intuition. By refining our initial business model, we have achieved remarkable success while remaining true to our core values.”

Pierre Rinaldi, COO & co-founder.

Charting the Future: SESAMm’s Strategic Vision for Advancing AI and ESG Innovation

As we move forward at SESAMm, I am personally very excited about the innovative strides we are making across multiple fronts. We are poised to roll out new generative AI features, including a dynamic AI assistant designed to streamline and enhance our offerings. We're also updating our ESG taxonomy to include the latest regulatory changes, ensuring that our products stay relevant and compliant.

Improving the accuracy and scope of our data remains a priority, and we are expanding our ESG indicators to provide a more comprehensive view of potential impacts. This enhancement will allow us to offer nuanced insights that go beyond traditional metrics.

Our index business is set for expansion with promising new applications leveraging ESG data and the potential for fruitful partnerships, leveraging our cutting-edge technology to explore new markets.

From a client engagement perspective, we are focused on making it easier for potential clients to understand why SESAMm is the superior choice. This involves clarifying our value proposition, which is built on unmatched service quality, extensive coverage, and a competitive edge that sets us apart from our rivals.

Geographically, we are significantly ramping up our efforts in North America, where demand for ESG-oriented solutions is growing rapidly. To support this expansion, we are investing in our team, ensuring we have the right people in place to drive our success in these new markets.

Through these focused efforts, we at SESAMm are not just aiming to maintain our leadership position in AI and financial analytics but are also setting new benchmarks for excellence and innovation in the sector.

Reflecting on the past decade, SESAMm is a testament to the power of innovation, teamwork, and perseverance. The milestones we have celebrated and the lessons we have learned form the bedrock of our enterprise, guiding us as we navigate the future. As we look ahead, our focus remains steadfast on enhancing our technological capabilities, expanding our global footprint, and delivering exceptional value to our clients. Moreover, we are deeply committed to advancing our ESG and sustainability efforts, which are integral to our business philosophy and strategic planning. With a dedicated team, a clear vision, and a robust approach to integrating ESG principles across all our operations, SESAMm is well-positioned to continue its journey of growth and innovation. Here's to the next decade of transforming challenges into opportunities and setting new standards in the financial technology landscape while promoting sustainable and responsible business practices.

SESAMm’s AI Technology Reveals ESG Insights

Discover unparalleled insights into ESG controversies, risks, and opportunities across industries. Learn more about how SESAMm can help you analyze millions of private and public companies using AI-powered text analysis tools.

As we commemorate Earth Day this year, it's important to confront our planet's harsh realities. Despite the numerous efforts of scientists, activists, and the tech-savvy younger generation, the ecological crisis deepens, underscored by persistent natural resource deterioration and escalating climate challenges. Today, we are driven more than ever to harness innovative technologies, including artificial intelligence (AI), to advance environmental, social, and corporate governance (ESG) initiatives and attain sustainability for a better future.

Learn “How Organizations Are Using NLP To Detect Greenwashing.”

Deteriorating Natural Resources

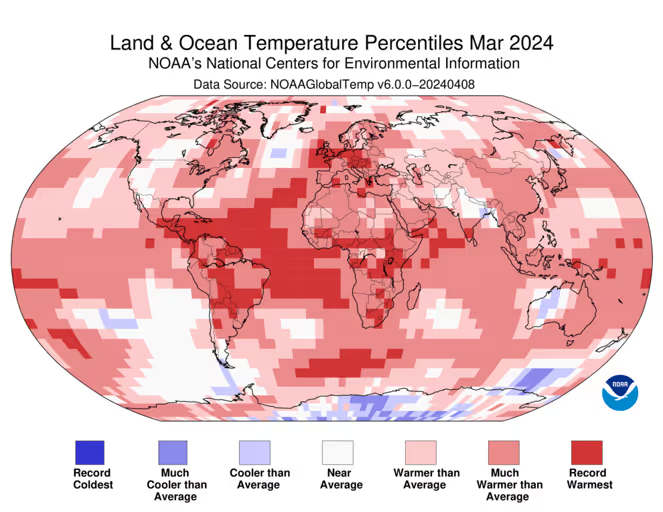
Over the past decades, our natural reserves have alarmingly diminished. By March 2024, the Earth’s average surface temperature has increased to approximately 54.9°F (12.7°C), a seemingly minor increase that masks significant polar ice melt and accelerated climate change.

Land and Ocean Temperature Percentiles March 2024.
Land and Ocean Temperature Percentiles March 2024. Source: noaa.gov.

Greenhouse gas emissions have increased to 37.4 billion metric tons in 2023. According to the United Nations, this is caused by burning fossil fuels, industrialization, food production, over-consumption, and manufacturing.

The loss of biodiversity is growing so fast that we now have around 44,000 species extinct due to climate change, drought, and floods. For example, plastic waste is considered the main contributor to ocean acidification, along with oil and toxins dispensed in the ocean by transportation and shipping companies. Moreover, mass production and mass consumption of food, fast fashion, furniture, and more are, along with urbanism, major factors leading to deforestation and natural resource depletion.

Human Concerns and Environmental Anxiety

These issues not only affect nature but also human well-being. A recent study shows that younger generations face a new form of anxiety called environmental anxiety. It results from their fear of where this crisis leads them and the unclear and ambiguous future. For example, we'll likely suffer from clean water scarcity by 2050, which might produce diseases and epidemics. At this rate, the weather will become hotter, damaging nature and causing massive wildfires. As a result, some areas might become inhabitable, causing mass migration and immigration, resulting in overpopulated cities.

Leveraging AI and ESG for a Sustainable Future

Innovative technologies such as AI are revolutionizing our approach to sustainability. AI tools analyze large amounts of data to monitor ESG metrics effectively, helping organizations to make informed decisions that align with sustainability goals. These technologies facilitate smarter resource management, reduce waste through predictive analytics, and improve energy efficiency. By integrating AI with ESG initiatives, businesses can enhance their operational efficiency and contribute significantly to environmental conservation.

Learn “How Successful Investors Are Using AI to Get ESG Data: A Quick Guide.”

Hope for Change

Despite these daunting challenges, there is room for optimism. From awareness campaigns to employing technology for recycling and reusing resources to building robotic animals to prevent animal captivity, researchers and organizations are doing their best to limit environmental damage. Governments are altering laws and regulations and signing treaties in partnership with active associations and organizations, which are joining efforts to improve life on Earth. Emerging businesses strive to leave an environmental and social footprint by integrating the United Nations' Sustainable Development Goals (SDG) within their corporate culture.

Conclusion

In sum, if we, as a whole, take proper action, the current climate threat could diminish within the next few decades. Helping us get there are more affordable means for renewable energy generation and organic produce and public awareness. We're all capable of making a difference through funding organizations, monitoring our waste and consumption, or participating in local community actions and initiatives. Also, we can learn more about how to help protect wildlife. But NOW is the time to take action to guarantee a better future for us and future generations.

Happy Earth Day!

Introduction

Today, environmental, social, and governance (ESG) criteria have become critical in shaping companies' operational and strategic directions. As organizations strive to align with the United Nation’s sustainable development goals (SDG), understanding the variances in ESG performances across different geographical regions becomes crucial. This article explores ESG discrepancies in North America, Latin America, Europe, Australia, Asia Pacific, and Emerging Countries. By dissecting the prevalent ESG risks and illustrating the distribution of SDG adverse behaviors within these regions, we aim to provide a granular analysis that not only highlights regional challenges but also paves the way for tailored strategic frameworks. This nuanced approach facilitates an informed assessment of disparities, empowering stakeholders to craft effective and regionally nuanced strategies.

ESG Overview: A Regional Perspective

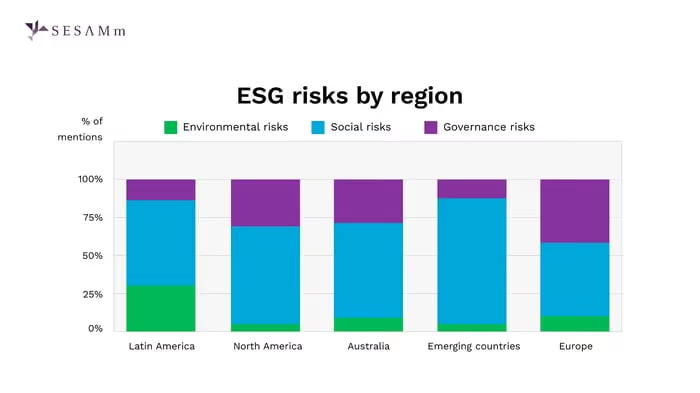
Upon standardizing data across the examined regions, our analysis unveiled a predominance of social risks across the board. Yet, the regional specificities unveil the complexity of global ESG landscapes.

ESG risks by region
Fig 1: ESG Risks by region

Upon standardizing data across the examined regions, our analysis unveiled a predominance of social risks across the board. Yet, the regional specificities unveil the complexity of global ESG landscapes.

Latin America is markedly affected by environmental risks, underscored by legal actions against companies for endangering biodiversity. Legal battles over toxic spills, water contamination, and ecosystem-threatening activities vividly portray this region's environmental challenges.

Europe emerges as a hotbed for governance-related risks, particularly emphasizing influence strategy and communication. European companies find themselves at the correlation of controversies ranging from greenwashing and emissions cheating to governance failures, spotlighting the complex governance terrain they navigate.

While grappling with governance risks, North America and Australia exhibit unique profiles. North American firms face various governance challenges, from securities fraud to greenwashing, painting a complex picture of corporate governance in the region. Australian companies are likewise embroiled in governance concerns, predominantly linked to senior management and regulatory compliance, reflecting the governance trials specific to the Australian context.

Emerging countries highlight the prevalence of social controversies, from human rights violations to labor rights concerns, underlining these regions' social complexities.

This multifaceted overview underscores the broad spectrum of ESG risks while illuminating the distinctive challenges faced by each region.

UNSDG Adverse Behaviors: Regional Breakdown

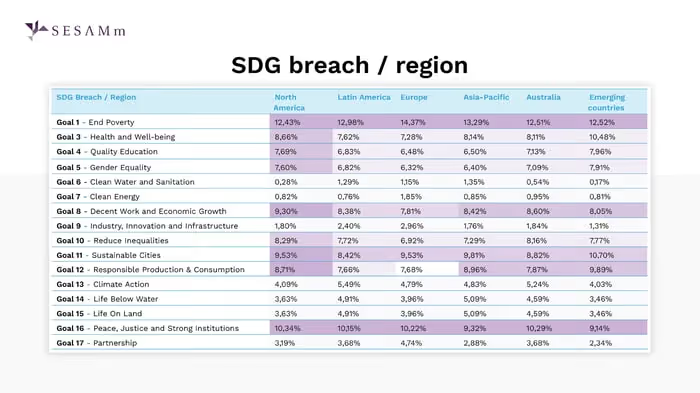
When looking at UNSDG adverse behaviors for the same regions, we find regional trends and more generalized ones. For example, Goal 1, “End Poverty,” displays one of the highest breach rates of all the goals. Whereas Goal 6 - Clean Water and Sanitation, displays interesting discrepancies, mainly exposing differences between developed and developing countries.

The table below provides a detailed comparison of SDG adverse behaviors across regions, categorizing them by specific goals to highlight regional differences in SDG challenges.

SDG breach per region
Fig 2: SDG breach/region

Goal 1, "End Poverty," is the most prevalent SDG issue across all areas. Europe is experiencing the most significant impact due to various factors, including labor rights issues, human capital concerns, governance challenges, anti-competitive practices, and tax controversies.

Similarly, Goal 16, "Peace, Justice, and Strong Institutions," underscores significant issues in North America related to human rights, labor, management integrity, anti-competitive actions, tax strategies, corruption, and shareholder matters, driven largely by flaws in the criminal justice system, including over-incarceration, racial bias, and police misconduct. These problems undermine public trust and equality, highlighting the need for governance improvements despite North America's strong institutional base.

Emerging countries face the greatest challenges with Goals 3 and 11, "Health & Well-being" and "Sustainable Cities," respectively, due to inadequate healthcare infrastructure, disease prevalence, limited healthcare access, poor sanitation, pollution, overcrowding, and substandard urban planning. Addressing these issues requires substantial healthcare, sanitation, and sustainable urban development investments to mitigate risks.

UNGC Controversies: A Regional Analysis

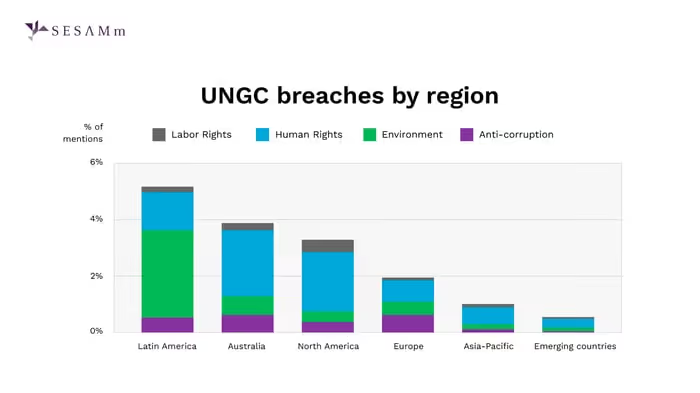
Our exploration extends to aligning ESG controversies with their respective regions and assessing the proportion of these risks aligning with breaches of the United Nations Global Compact (UNGC) principles.

UNGC breaches per region
Fig 3: UNGC breaches by region

Latin America emerges as the frontrunner in this evaluation, demonstrating a noteworthy prevalence of breaches, particularly within the environmental pillar. Notably, the focal point centers on environmental damages attributed mostly to mining and metals companies.

Australia is marked by a significant number of controversies surrounding human rights violations. These encompass various instances, ranging from privacy breaches and infringements on the right to security and dignity and diversity & inclusion. These incidents have garnered considerable attention, contributing to the heightened significance of regional human rights breaches.

In North America, despite a considerable share of human rights breaches, it distinguishes itself by exhibiting the highest prevalence of labor rights violations. In contrast to other regions, North America faces a substantial number of lawsuits related to employment, particularly concerning diversity and inclusion breaches, including harassment lawsuits and instances of racial bias.

European companies distinguish themselves through notable instances of Anti-corruption pillar breaches, including multiple failures in money laundering investigations, legal actions resulting in lawsuits and fines, as well as settlements for bribery allegations and accusations of kickbacks.

Latin America's environmental controversies, Australia's human rights challenges, North America's labor rights issues, and Europe's anti-corruption breaches each tell a part of the global ESG narrative, demonstrating the diverse facets of regional ESG controversies.

Leveraging SESAMm for Insightful ESG Analysis

SESAMm's technology identifies and analyzes potential risks and controversies through our advanced AI-powered text analysis tool, providing essential insights for stakeholders. This capability is invaluable for organizations, particularly private equity firms and financial institutions, aiming to navigate ESG complexities. By leveraging SESAMm's insights, businesses can adapt their ESG strategies to their regional contexts' unique challenges and opportunities, ensuring global sustainable and responsible operations.

Conclusion

To summarize, this analysis underscores significant regional differences in ESG factors, with social risks emerging as a common concern worldwide. Yet, regional distinctions are evident: Latin America is particularly impacted by environmental issues, Europe grapples with governance risks, and emerging nations face a surge in social controversies. The detailed analysis of SDG adverse behaviors, organized by goals for each region, highlights these differences further. It is imperative for companies to recognize and adapt to these regional nuances in their ESG strategies, ensuring approaches are finely tuned to address the distinct risks and challenges prevalent in their specific operational environments.

SESAMm’s AI Technology Reveals ESG Insights

Discover unparalleled insights into ESG controversies, risks, and opportunities across industries. Learn more about how SESAMm can help you analyze millions of private and public companies using AI-powered text analysis tools.

On 3 April 2025, the European Parliament voted to postpone the implementation deadlines of two major EU sustainability laws: the Corporate Sustainability Reporting Directive (CSRD) and the Corporate Sustainability Due Diligence Directive (CSDDD). The motion passed with an overwhelming majority of 531 votes in favor, 69 against, and 17 abstentions, supporting the European Commission’s “stop-the-clock” proposal. This vote, conducted under an urgent procedure, is part of a broader effort to streamline corporate sustainability requirements and reduce compliance burdens on companies. The Council of the EU had already endorsed the delay on 26 March 2025, citing the need to provide businesses with additional time to adapt to the directives. Final formal approval by the Council is expected shortly, after which the adjusted timelines will take effect.

Extended Deadline for Sustainability Reporting (CSRD)

The Corporate Sustainability Reporting Directive (CSRD) mandates companies to make extensive ESG disclosures. The approved delay affects the implementation timeline as follows:

  • Large companies' reports delayed by 2 years: Companies defined as “large” under CSRD will now begin reporting on the financial year 2027, with the first sustainability reports published in 2028. Previously, these companies were expected to commence reporting for the financial year 2025, with reports published in 2026.
  • Listed SMEs granted additional time: Listed small and medium-sized enterprises (SMEs) and other qualifying small companies will commence CSRD reporting one year later than initially scheduled, covering their financial year 2028 data in reports published in 2029. Under the original plan, these SMEs were to begin reporting for the financial year 2027, with an option to opt out until 2028.

Companies already within the scope of EU sustainability reporting (large public-interest entities under the previous Non-Financial Reporting Directive) are largely unaffected by this delay and have begun reporting for the financial year 2024 as planned. For the rest of the corporate sector, the CSRD’s effective start is deferred, providing additional time to build reporting systems and comply with the European Sustainability Reporting Standards (ESRS). The European Commission has tasked the European Financial Reporting Advisory Group (EFRAG) with simplifying and streamlining the reporting standards by late October 2025, enabling companies to adopt a more manageable set of disclosures when reporting begins.

One-Year Postponement for Due Diligence Rules (CSDDD)

The Parliament’s vote also extends the timeline for the Corporate Sustainability Due Diligence Directive (CSDDD), an EU law requiring companies to identify and mitigate human rights and environmental impacts in their operations and supply chains. The adopted delay includes:

  • Transportation deadline extended: EU Member States now have until 26 July 2027 to transpose the CSDDD into national law, a one-year extension from the original July 2026 deadline. This extension allows governments to pass national legislation implementing the due diligence requirements.
  • First corporate compliance phase delayed to 2028: The initial wave of companies subject to the CSDDD will have an additional year before the rules apply. Large EU firms with over 5,000 employees and €1.5 billion+ in turnover (and non-EU companies with equivalent EU turnover) must begin complying in July 2028 rather than 2027. Notably, this July 2028 phase will also cover companies with over 3,000 employees and €900 million turnover, effectively merging the directive’s first two implementation waves into one timeline.
  • Subsequent phase in 2029: The next set of in-scope companies, including those with ≥1,000 employees and €450 million in turnover, are expected to come under the CSDDD by July 2029 as previously scheduled. The overall phase-in period is compressed into two stages (2028 and 2029) rather than spanning 2027–2029. This compressed rollout means the largest companies gain a one-year reprieve, while the smaller large companies will enter only slightly later than initially planned.

Next Steps

While this vote confirms a delay in implementation, negotiations regarding bigger changes to the laws (updating the reporting standards and the scope of companies affected) are still in their early stages. Those negotiations include exempting an estimated 80% of the companies initially covered by only applying these regulations only to firms with more than 1,000 employees. We delve deeper into these developments in our recent summary of the Omnibus initiative.

About SESAMm

SESAMm is a global leader in ESG controversy data, using advanced Generative AI. We automate monitoring and due diligence on public and private assets, providing coverage of more than 5 million companies. Our clients include companies like Carlyle, Warburg, Natixis, RBI, Fitch, Oddo, and more. SESAMm has raised $50M from renowned investors and operates across 4 continents.
Discover how we can help your team uncover ESG and reputational risks in seconds. Reques a free trial here.

Sources

SESAMm’s AI Technology Reveals ESG Insights

Discover unparalleled insights into ESG controversies, risks, and opportunities across industries. Learn more about how SESAMm can help you analyze millions of private and public companies using AI-powered text analysis tools.

In recent years, consumers have become increasingly conscious about the impact of their purchases on the environment and society. As a result, many companies have jumped on the bandwagon of sustainability and green initiatives to attract consumers who prioritize ethical and environmentally friendly products. However, not all companies are authentic in their claims and practices, leading to a phenomenon known as greenwashing. In the first article of this two-part series, we gave an in-depth analysis of reputational laundering and greenwashing. In this article, we will explore the prevalence of greenwashing across various industries. We will also study the case of a company practicing greenwashing and a genuinely sustainable company.

Reputational Laundering by Industry

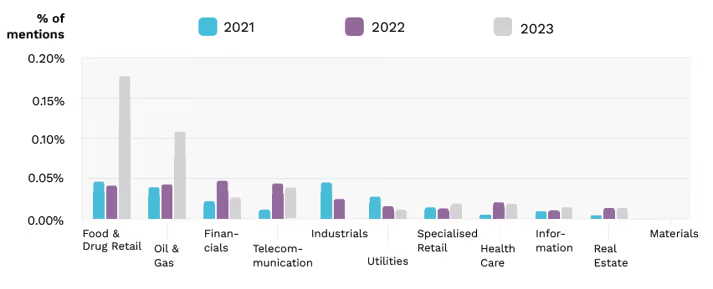
Reputational laundering is a common practice across various industries. Traditionally, the ‘Oil and Gas’ and ‘Financial’ industries have been identified as the main culprits. However, we have recently observed a substantial increase in the frequency of mentions in the ‘Food & Drug Retail’ industry, surpassing all other sectors by a significant margin. To evaluate this trend, we calculated the percentage of reputational laundering mentions in relation to the total number of mentions for each industry.

Reputational laundering over time

We looked at the last three years to find how each industry has evolved. Most industries have remained fairly static within a reasonable range. However, ‘Industrials’ have seen a significant decrease in mentions. Conversely, ‘Oil and Gas’ and ‘Food & Drug Retail’ significantly increased in 2023.

‘Food & Drug Retail’ more than tripled its mentions percentage due to a large number of mislabeled eco-friendly products (Walmart & Kohl’s) and green initiatives claims (Coca-Cola, Unilever, Amazon…).

The ‘Oil and Gas’ industry ranked second, and its recent spike can be associated mainly with greenwashing on actions such as their direct negative impact on the environment and the impact on local communities (TotalEnergies - Uganda & Tanzania). Another example is related to sportswashing with ‘Oil and Gas’ advertising heavily in sports events and even sponsoring sports clubs.

The financial industry has seen a decrease in mentions in 2023. However, its overall numbers are still significant. Most mentions we found were related to their investment activities in fossil fuels (HSBC to stop funding new oil and gas fields after greenwashing criticism. Goldman Sachs Facing SEC Probe of ESG Funds in Asset Management).

Figure 5 Reputational laundering by industry over time
Figure 1: Reputation laundering by industry over time.

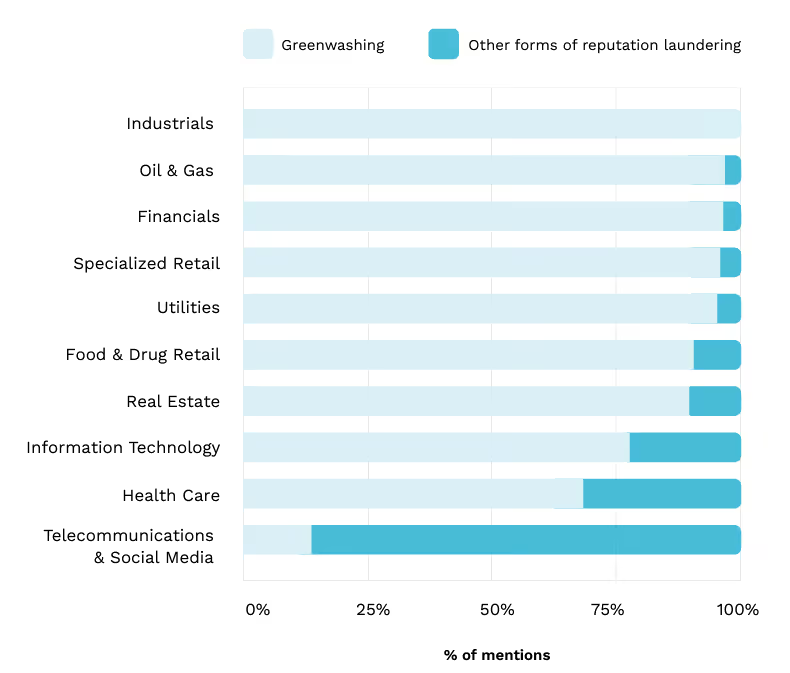
When examining the prevalence of reputational risks across sectors, greenwashing is the predominant concern in most industries. This is particularly evident in sectors like Industrials, Oil & Gas, and Financials, where greenwashing mentions are especially prominent. On the other hand, Telecommunications & Social Media stands out as an exception, with the bulk of its mentions skewing towards colorwashing, which encompasses specific practices such as blackwashing and sportswashing (Netflix accused of 'blackwashing' new docu-series Queen Cleopatra by casting black British actress).

Figure 6 Reputational laundering breakdown by industry
Figure 2: Reputational laundering breakdown by industry.

Use Case: Focus on the Financial Industry

The financial industry's footprint in reputational laundering might not be the most pronounced in terms of direct mentions, but its influence stretches wide via its investment activities in other sectors. This means the ripple effect of the financial sector's actions can be substantially more impactful than those in other industries. Our investigation into this phenomenon included a rigorous examination of the frequency with which financial institutions are cited in discussions of greenwashing. Additionally, we assessed their efforts in driving positive impact initiatives. We scrutinized a group of 144 financial entities, arranging them on a scale from the greatest to the least number of greenwashing mentions in proportion to their overall volume of mentions.

Top financial firms by greenwashing claims

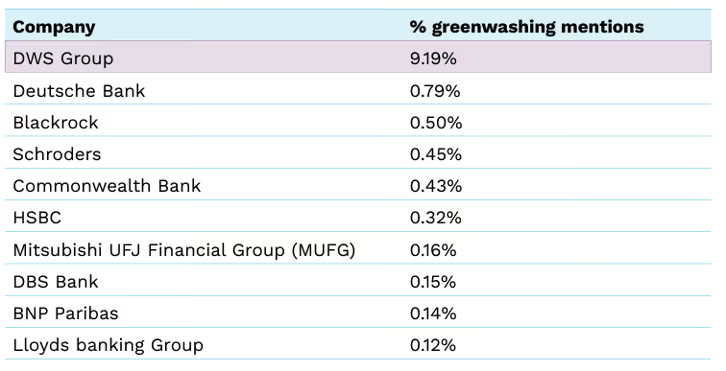
Below, we listed the financial firms with the highest relative volume of greenwashing mentions. Beyond the first two institutions on the list, which are related and had a big scandal in 2022, we can see many very recognizable names, such as Blackrock (investing in fossil fuels), JP Morgan (for fossil fuel investment policies), and HSBC (false advertising green claims) making our top ten list.

Table 1

Case Study: DWS Group

The DWS Group, previously known as Deutsche Asset Management, found itself in the spotlight for all the wrong reasons in 2022 and 2023. The scandal landed them at the top of our list, a position highlighted by the significant number of mentions they received — a figure that is an order of magnitude higher than that of any other entity on the list.

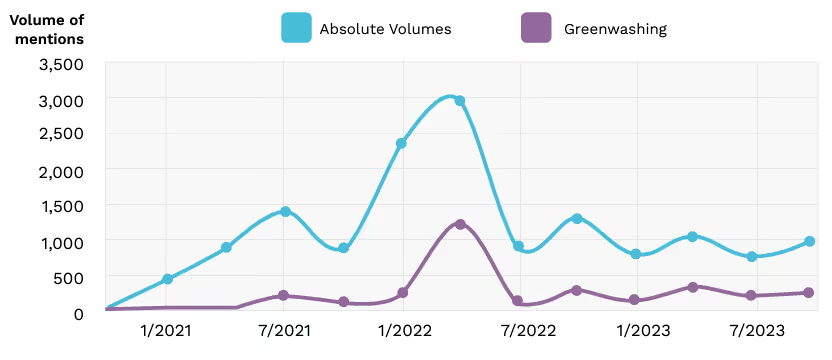
As a German asset management firm under the umbrella of Deutsche Bank, DWS was embroiled in severe greenwashing allegations. The last two years were marked by high-drama events: starting with greenwashing allegations at the end of 2021, their offices were searched in May 2022, which led to the resignation of the DWS chief in June 2022. The saga concluded with a substantial $25 million fine paid to U.S. regulators in September 2023.

The accompanying chart provides a visual representation of the timeline for these events, contrasting the number of absolute mentions with those specifically related to greenwashing. The alignment in the timing and scale of these mentions with the unfolding events is unmistakable.

Figure 7 DWS relative greenwashing mentions
Figure 3: DWS Group relative greenwashing mentions.

Best-in-class companies

In our effort to wrap up our study on an optimistic note, it's important to recognize that the heightened scrutiny of greenwashing and its associated initiatives ultimately serves a beneficial role by significantly raising our collective consciousness about crucial ESG issues.

While it's true that numerous companies have come under fire for greenwashing, it's equally important to highlight those that are genuinely advancing initiatives with positive environmental and social repercussions across the globe.

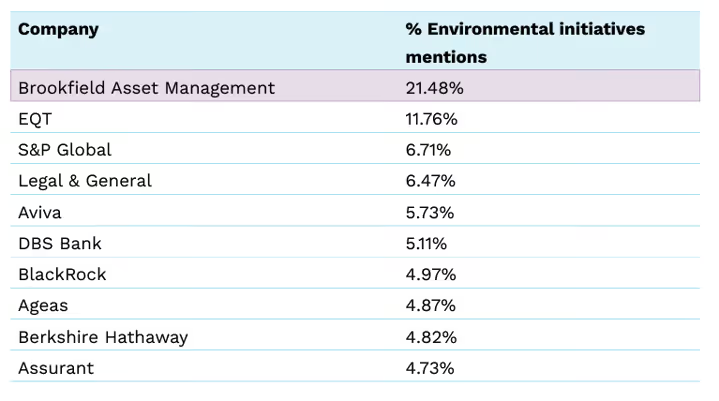
Employing the same method used to scrutinize financial firms implicated in greenwashing, we focused on the same group of 144 companies, honing in on the top 10 that stood out based on normalized mentions of their positive environmental actions.

The findings are quite encouraging: mentions of these positive initiatives dwarf those of negative impacts when viewed as a proportion of total mentions. Brookfield Asset Management (Brookfield) shines as the most notable, garnering almost double the mentions of its closest peer.

Also noteworthy is BlackRock's appearance on this list. Despite its presence on the greenwashing list, BlackRock has made strides in positive efforts, too. The company's initiatives—some counterbalancing the negative—have received more attention for their positive impact than for greenwashing, suggesting a complex but proactive ESG engagement.

Furthermore, companies like EQT, Berkshire Hathaway, and Standard & Poor's have actively engaged in initiatives that drive positive impact, earning them significant—and rightfully so—media coverage.

table 2

Case Study: Brookfield Asset Management

Brookfield's presence on our top 10 list is well-founded, reflecting the substantial conversation around their significant efforts in environmental sustainability. The company has undertaken numerous initiatives aimed at reducing its ecological impact. These include launching a $7 Billion Global Energy Transition Fund, collaboration on a sustainable neighborhood project in Texas, a commitment to planting thousands of trees, and the transition to zero-emission electricity in their offices.

Figure 8 Brookfield sentiment vs environmental initiatives
Figure 4: Brookfield sentiment vs environmental initiatives.

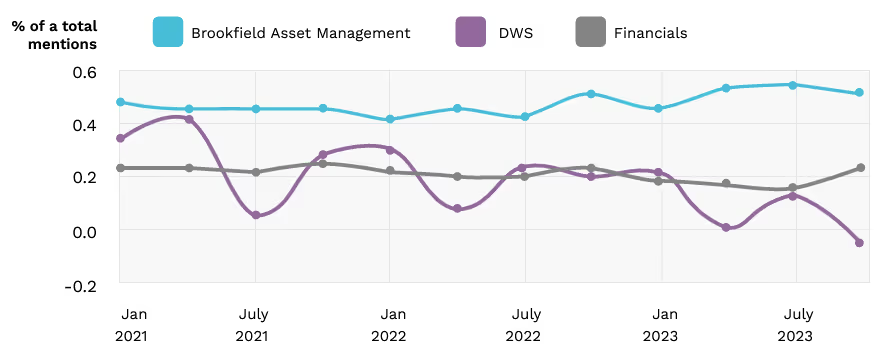
In terms of visibility, these environmental initiatives represent a significant portion of the company’s profile, surpassing 50% of total mentions in September 2022. This highlights the dominant role these actions play in the public discourse surrounding Brookfield.

The company’s polarity(1) — a measure of sentiment in mentions — shows a steady and positive trajectory beginning in late 2021. This trend points to a growing positive reputation and increased positive online discussions regarding the company.

Web Sentiment Analysis: Financial Industry vs. DWS & Brookfield

Figure 9 Sentiment over time
Figure 5: Sentiment over time.

When assessing the landscape of ESG engagement within the financial sector, we consider the comparative reputations of two key players: the leader in positive impact initiatives against the firm with the highest number of greenwashing mentions. How do they stack up against the broader sentiment within the financial industry?

The finance industry at large grapples with a challenging reputation shaped by various issues, including regulatory shortcomings, perceived corporate greed, opacity, and environmental impacts, among others.

Against this backdrop, we observe that:

DWS: The company's reputation trajectory is on a downward slope compared to the industry average, with the aftereffects of recent controversies culminating in a reputation low as of October 2023.

Brookfield: In contrast, Brookfield's commitment to the environment appears to buoy its reputation, maintaining a consistently positive trend that surpasses the market standard. Notably, from January 2023 onward, there is a discernible uptick in positive sentiment.

Conclusion

While the prevalence of greenwashing poses a considerable challenge within the corporate sphere, our study reveals a silver lining. The intensive scrutiny and debate surrounding environmental, social, and governance (ESG) issues have led to heightened awareness and, more importantly, action. Amidst the cacophony of claims, our analysis has found a discernible pattern of positive ESG initiatives overshadowing negative impacts, indicating a shift towards genuine sustainability efforts.

Particularly encouraging is the performance of certain frontrunners like Brookfield Asset Management, which has emerged as a beacon of positive action, outpacing its peers in driving meaningful change. This illustrates the potential for firms to lead by example and underscores the importance of rigorous analysis in distinguishing substantive ESG commitments from superficial ones.

Ultimately, this study underscores the transformative power of informed scrutiny and the pivotal role that advanced analytical tools play in propelling the ESG agenda forward. As the financial community continues to refine its approaches to evaluating ESG metrics, we can remain cautiously optimistic about the journey from mere green-tinted narratives to deeply rooted, impactful corporate practices.

(1) Polarity aggregates positive and negative sentiment (opinions, reviews) on a company. It ranges from -1 to 1. A 0 score means that positive and negative sentiment are equal. Well-regarded brands generally have polarity scores over 0.5.

At SESAMm, we used AI to study billions of articles and analyze greenwashing trends. Download this comprehensive ebook for an in-depth understanding of the evolving landscape of reputational laundering, notably greenwashing, and dive into its trends in the corporate world.

SESAMm’s AI Technology Reveals ESG Insights

Discover unparalleled insights into ESG controversies, risks, and opportunities across industries. Learn more about how SESAMm can help you analyze millions of private and public companies using AI-powered text analysis tools.

In a recent interview, Jose Salas, Head of Partnerships and Strategy at SESAMm, alongside Kiet Tran and Kat Tatochenko, shared how SESAMm is transforming the landscape of AI-powered text analysis. SESAMm excels in extracting valuable insights from diverse data sources, addressing key issues like ESG controversies and SDG impacts for clients, which include private equity firms and financial institutions.

Salas highlighted SESAMm's distinct approach to technology, emphasizing its role in identifying risks and opportunities for investors. The company's future plans involve embracing generative AI to refine our data analysis further, promising even sharper insights for our clients.
SESAMm's innovative strategies demonstrate our commitment to turning complex data into actionable intelligence, paving the way for smarter investment decisions in the financial sector.

Watch the full interview here:

SESAMm’s AI Technology Reveals ESG Insights

Discover unparalleled insights into ESG controversies, risks, and opportunities across industries. Learn more about how SESAMm can help you analyze millions of private and public companies using AI-powered text analysis tools.

Environmental challenges, such as climate change, biodiversity loss, and resource depletion, rapidly increase daily. The urgency for a coherent and actionable framework to promote sustainable investments has never been more important. With all of the terms and claims surrounding sustainability, it is a struggle for investors, companies, and consumers to identify which activities and projects are genuinely beneficial for the environment. This is where the EU Taxonomy is a guiding instrument to illuminate the path toward a sustainable economy.
Introduced by the European Union, the EU Taxonomy is a green classification system designed to provide criteria for identifying environmentally sustainable economic activities. Offering a common language and set of standards, the Taxonomy helps mitigate the confusion surrounding sustainability claims and enhances the transparency needed for informed investment decisions.

Understanding the EU Taxonomy

What is the EU Taxonomy?

The EU Taxonomy is a systematic framework that translates the European Union's climate and environmental objectives into specific criteria for economic activities. It assists investors and companies in recognizing which investments qualify as “green,” ensuring that capital flows toward activities with a positive environmental impact.

Main Objectives

The EU Taxonomy is built upon several objectives aimed at transforming the economic landscape:

  1. Supporting the transition to a sustainable economy: The Taxonomy enables businesses to align their operations with the EU's environmental goals by providing clear definitions and criteria for sustainable activities.
  2. Mitigating market fragmentation: The Taxonomy aims to provide uniform standards across EU member states, reducing inconsistencies arising from different national interpretations of sustainability.
  3. Protecting against greenwashing: In an environment where misleading claims about sustainability are prevalent, the Taxonomy offers a reliable benchmark, ensuring that companies cannot misrepresent their environmental practices.
  4. Accelerating financing for sustainable projects: By identifying what constitutes a sustainable activity, the Taxonomy directs investments toward projects that contribute to the EU’s climate and environmental objectives, promoting the development of green technologies and practices.

The EU Taxonomy in Sustainable Finance

The EU Taxonomy is a key component of the broader sustainable finance agenda. By providing a systematic approach to sustainability, it helps guide financial flows toward investments that will foster real environmental progress. This initiative is particularly significant as global investors increasingly seek to align their portfolios with sustainability goals.

Understanding the EU Taxonomy

What is the EU Taxonomy?

The implementation of the EU Taxonomy is facilitated through the Taxonomy Climate Delegated Act. This act sets the criteria for activities concerning climate objectives, recognizing those contributing to achieving climate neutrality and enhancing climate change resilience. It represents the first step towards establishing a comprehensive set of criteria applicable to various sectors.

Sectors Covered

The Taxonomy initially focuses on sectors with significant contributions to greenhouse gas emissions. These sectors include:

  • Energy: Emphasizing renewable energy production and energy efficiency improvements.
  • Forestry: Promoting sustainable forest management.
  • Manufacturing: Aiming for reduced emissions and efficient resource use in manufacturing processes.
  • Transport: Encouraging the adoption of lower-emission transport options.
  • Buildings: Focusing on energy-efficient design and construction methods.

Technical Screening Criteria

The Taxonomy includes strict technical screening criteria that define acceptable thresholds for sustainability. These criteria are based on scientific evidence and best practices, ensuring that activities meet established environmental standards.

Defining Green Economic Activities

The Six EU Environmental Objectives

At the core of the EU Taxonomy are six environmental objectives that guide the classification of economic activities:

  1. Climate change mitigation: Activities that significantly reduce greenhouse gas emissions.
  2. Climate change adaptation: Actions aimed at preparing for and adjusting to the impacts of climate change.
  3. Sustainable use and protection of water and marine resources: Strategies to ensure long-term viability and health of water resources and marine ecosystems.
  4. Transition to a circular economy: Practices that promote efficient resource use, waste reduction, and recycling.
  5. Pollution prevention and control: Efforts focused on minimizing pollution and managing waste effectively.
  6. Protection and restoration of biodiversity and ecosystems: Initiatives dedicated to conserving biodiversity and restoring ecological systems.

Conditions for Taxonomy-Aligned Activities

For economic activities to be recognized as taxonomy-aligned, they must fulfill four critical conditions:

  1. Make a substantial contribution: The activity must significantly contribute to at least one of the environmental objectives.
  2. Do no significant harm: It must not adversely impact any other environmental objective.
  3. Comply with minimum social safeguards: Activities must meet criteria protecting social and labor rights.
  4. Meet technical screening criteria: These are established through scientific methodologies, ensuring that activities genuinely contribute to sustainability goals.

Integrating the EU Taxonomy with Other Regulations

Corporate Sustainability Reporting Directive (CSRD)

The CSRD complements the EU Taxonomy by requiring companies to disclose comprehensive information about their environmental performance. This regulation aligns closely with the Taxonomy by mandating that organizations within its scope report on the extent to which their activities are taxonomy-aligned, promoting transparency and accountability in corporate sustainability efforts.

Sustainable Finance Disclosure Regulation (SFDR)

The SFDR mandates that financial market participants disclose how their financial products align with the Taxonomy standards. This regulatory framework aims to provide investors with insights into the sustainability impacts of their investment options, fostering greater trust and informed decision-making.

Implementation and Compliance

Corporate Mandatory vs. Voluntary Disclosure

  • Mandatory Disclosure: Large companies and financial market participants are obligated to disclose the alignment of their activities with the Taxonomy. This requirement enhances transparency and ensures stakeholders have access to key information regarding corporate environmental performance.
  • Voluntary Disclosure: Companies can also engage in voluntary reporting to highlight their sustainability strategies and progress. This allows businesses to strategically utilize Taxonomy criteria in their planning and investment decisions.

The Role of Member States and Financial Entities

Member States and the EU are expected to leverage the Taxonomy in their regulatory frameworks. This includes establishing public labels for green corporate bonds and financial products aligned with SFDR, thus fostering market acceptance and stimulating demand for sustainable investments.

Challenges and Opportunities

Market Fragmentation

While the EU Taxonomy aims to unify standards across the region, differences in implementation and interpretation among member states could lead to market fragmentation. The EU must maintain a cohesive approach and address any differences that may arise.

The Risk of Greenwashing

With the growing popularity of green investments, there is an increasing risk of greenwashing, where companies may exaggerate or misrepresent their sustainability claims. The EU Taxonomy provides a valuable tool to combat this risk by establishing clear and robust criteria for what constitutes a sustainable activity.

Benefits for Companies and Investors

For companies, engaging in taxonomy-aligned activities can attract institutional and retail investors, banks, and other financial entities that prioritize sustainability. Investors, on the other hand, benefit from improved clarity and assurance about the environmental impact of their investments, allowing them to align their portfolios with their sustainability values.

Future of the EU Taxonomy

Expansion of Coverage

The EU Taxonomy is not static; it is designed to evolve over time. While it currently focuses on sectors with the highest emissions, plans are in place to expand its coverage to include additional sectors and activities as the regulatory framework matures and new technologies emerge.

Adaptation to Technological Changes

As technological advancements grow, the EU Taxonomy must remain responsive to new developments in sustainability practices. This adaptability is crucial for ensuring that the criteria remain relevant and effective in guiding investments toward genuine environmental sustainability.

The Role of the EU Taxonomy in Achieving Sustainability Goals

The EU Taxonomy serves as a cornerstone for sustainable finance within the European Union. By providing clarity and consistency in defining what constitutes a sustainable activity, it empowers both companies and investors to make informed decisions that contribute to environmental preservation and climate goals.

Conclusion

The EU Taxonomy is an initiative aimed at redirecting investments toward environmentally sustainable activities. By establishing clear criteria and creating a common understanding of sustainability, the Taxonomy not only assists companies in navigating their transitions to greener practices but also safeguards the integrity of the environmental finance market.

SESAMm’s AI Technology Reveals ESG Insights

Discover unparalleled insights into ESG controversies, risks, and opportunities across industries. Learn more about how SESAMm can help you analyze millions of private and public companies using AI-powered text analysis tools.

Stay ahead with the latest in ESG and AI intelligence

Join our mailing list to receive new reports, event invites, and updates from SESAMm directly to your inbox.